The enemy of knowledge is not ignorance, it’s the illusion of knowledge (Stephen Hawking)

It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so (Mark Twain)

Invest with smart knowledge and objective odds

YOUR DAILY EDGE: 1 October 2026

The U.S. Economy Is Accelerating Evidence keeps coming that investment and growth are picking up.

The WSJ Editorial Board:

(…) the Commerce Department on Wednesday made an unusually large upward revision in its economic growth estimate for the first half of the year. Might rising yields on the 10-year Treasury reflect accelerating economic growth?

The Commerce Department raised its GDP growth estimate for the first quarter to 2.5% from 2.1%, as well as for the second to 2.2% from 1.5%. These large revisions reflect newly available data as well as updates to annual benchmarks that include refinements in methodology since 2021.

The upward revisions to real GDP growth stem partly from reduced inflation estimates. But the bigger story is that business investment and consumer spending have been stronger than economists thought.

Business investment was revised up half a percentage point to 9% thanks to higher spending on intellectual property and structures tied to AI. Commerce says data centers drove the increase, while information processing equipment contributed to stronger consumer spending.

Admissions to spectator amusements also buoyed consumer spending during the second quarter. A World Cup dividend? Regardless, higher gasoline prices don’t seem to be restraining consumers. Consumer spending has been growing faster than personal incomes in recent quarters, perhaps in part owing to the wealth effect from a booming stock market. Fidelity recently reported that the number of Americans with more than a $1 million in the company’s 401(k)s surged 19% during the second quarter to a record 769,000.

Americans can thank the AI boom, assisted by the GOP tax bill, for lifting corporate profits and equity prices. Corporate profits in the second quarter rose 20.8% from a year earlier. Even if some company valuations are stretched, increases in stock prices are broader than a couple of years ago when indexes were driven by the so-called Magnificent Seven.

Net exports subtracted 1.1 percentage points from GDP in the calculation, as AI companies imported more chips and equipment for their data center build-out. But this is a positive for U.S. domestic investment and growth. Imports aren’t a sign of economic weakness. (…)

By the way, faster economic growth has buoyed tax revenue, which increased 3% during the first 11 months of this fiscal year. Declines in corporate tax revenue owing to the tax bill were more than offset by income tax revenue, which increased 8% ($189 billion) after accounting for carve-outs for tips, overtime, etc.

The press has been in a panic over the rising yield on the 10-year Treasury, which has crept up 100 basis points this year to 5.29%. The conventional wisdom is that higher energy prices and expectations of more debt issuance are the culprit, but faster growth and competition for capital are contributing. Estimates for third quarter GDP growth have also been rising as September looks strong. (…)

(…) A key metric of underlying growth trends, real final sales to private domestic purchasers, was also tweaked higher, to 4.6%.

Meanwhile, the inflation metric known as the personal-consumption expenditures price index rose by 3.4% over the past 12 months, the Commerce Department said in a separate report Wednesday, level from a month earlier.

In August alone, price increases accelerated. The overall index rose by 0.3%, and the core version that excludes food and energy prices rose by 0.2%, faster than the July readings.

That acceleration came despite a tweak to the PCE inflation formula that otherwise pulled down annualized inflation readings recorded in recent months. To address mismeasurement concerns, the Bureau of Economic Analysis changed how three price categories are tabulated—legal services, investment services and computer software—and applied the change retroactively. (…)

Upward revisions to the investment category—which includes construction—emphasize how important the build-out of AI infrastructure has been to economic growth. And an increase in estimates of second-quarter consumer spending underscores that with a solid labor market and strong stock returns, household finances have remained in good shape. (…)

Wednesday morning’s data also brought evidence that American shoppers are still in sound financial shape. Consumer spending increased by 0.9%, a fast climb partly driven by more spending at gas stations as gasoline prices rose. Income growth cooled a bit to 0.2%, from 0.3% a month earlier.

A top Federal Reserve official suggested Tuesday that the central bank could wait until December before raising interest rates again, pushing back against market bets on a follow-up increase next month.

The remarks from New York Fed President John Williams carry particular weight because as vice chair of the Fed’s rate-setting committee, he has typically sought to reflect the views of the committee’s center of gravity rather than stake out his own position.

Inflation remains too high, and another rate increase “late this year” might be appropriate, Williams said. But for now, the Fed can likely take time to review additional data before tightening policy further, he said.

“With the policy action we took at our September meeting, there is no need for urgency,” Williams said in a speech in Buffalo, N.Y. (…)

Williams’s relatively precise signals were notable because Warsh has renounced the kind of verbal cues his predecessors used to shape investors’ expectations ahead of policy meetings. That approach carries a risk: If markets come to expect a move officials aren’t prepared to make, the Fed must choose between surprising investors and following through on an increase it might think isn’t necessary. Williams’s comments Tuesday could help the central bank avoid that bind. (…)

Other Fed officials who, like Williams, typically vote with the Fed’s policy consensus, have signaled in recent days that they think rates should rise further, without laying out a particular timeline.

In a speech Tuesday, Fed governor Michael Barr said “further policy adjustments are likely to be needed to ensure inflation comes down to target in a timely fashion,” but didn’t specify his view of the urgency of a further rate increase. Governor Lisa Cook outlined a similar perspective in a speech Monday.

By the time they meet in October, Fed officials will have one more month of labor-market data in hand—the September jobs report, due Friday—and a September inflation update coming in two weeks.

Goldman Sachs: “We are pushing back the second hike in our forecast to December, and we see a strong chance that the FOMC will ultimately conclude that additional rate hikes are unnecessary.”

But Ed Yardeni points out that the 2Y Treasury yield remained 100bps above the federal funds rate today and that Federal funds futures are pricing in three to four 25bps rate hikes over the next 12 months, including roughly two over the next six months.

Ed argues that the inflation genie is not about to find its bottle yet:

The key point is that much of the recent decline in core PCED inflation reflects revised measurement procedures rather than a genuine improvement in underlying inflation.

Indeed, despite the methodological changes, the report’s details point to sticky underlying inflation. Goods PCED inflation rose to 3.6% y/y in August from 3.3% in July, partly reflecting a 4.1% m/m jump in gasoline prices. Tariffs and the AI buildout added further pressure: prices for computers and peripherals surged 3.8% m/m, while toy prices rose 2.0%.

Looking ahead, tariff pass-through and AI-related demand should keep goods inflation elevated, while the renewed rise in oil and refined-product prices in September adds another source of upward pressure.

The supercore inflation rate isolates some of the stickiest and most wage-sensitive parts of the inflation basket. The measure remains well above a pace consistent with the Fed’s 2% target. More importantly, it has been moving higher since October 2025.

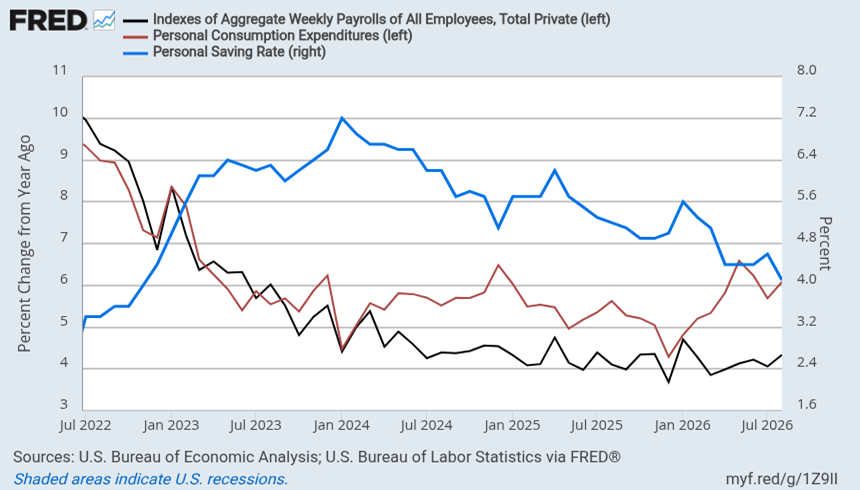
Spending growth accelerated since March 2026, not because income grew faster but because Americans strongly dissaved:
image

Ed expects this to continue:

The surge in household net worth relative to disposable income is causing consumers, especially Baby Boomers, to reduce their savings rate. August’s saving rate was revised meaningfully higher, but still fell to 4.1%, the lowest since November 2022. We expect it to decline further as more Boomers retire. Their labor income drops to zero when they do so, but their sizable accumulated wealth lets them keep spending.

  • The AI wealth effect (Axios)

Americans’ wealth jumped by $12.8 trillion in the second quarter, led by a nearly $11 trillion gain in stock holdings and other financial assets, Axios Markets author Emily Peck writes from new Fed data. That’s the biggest single quarterly increase, in dollar terms, on record.

The AI boom-fueled wealth surge is propelling spending in the U.S. economy. Half of all growth in consumption is being driven by those effects, says Krishna Guha, head of economics at Evercore ISI.

A column chart that shows quarterly changes in U.S. household corporate equity holdings from Q1 2017 to Q2 2026. Values range from minus $7.78 trillion in Q2 2022 to $10.71 trillion in Q2 2026. Losses cluster in 2018, 2020 and 2022, while gains dominate 2023 to 2026.Data: Federal Reserve. (Includes securities held indirectly through mutual funds, defined-contribution pension plans and variable life insurance/annuity products.) Chart: Emily Peck/Axios

AI is the main driver of this reacceleration.

Inflation?

Core PCE rose 0.25% MoM), +3.1% a.r. and 3.0% YoY. The SuperCore PCE (Services ex-shelter) reversed its recent drop on a YoY basis, surging 0.4% MoM to 3.45% YoY.

Some also argue that higher diesel costs will shortly hit consumer inflation.

Diesel prices will not return to normal for more than a year, according to US oil and gas executives surveyed by the Federal Reserve Bank of Dallas. Almost half of those polled expect diesel prices will take more than four quarters to return to 2025 levels, according to the anonymous survey of 100 oil and gas companies. (…)

“Diesel is the mother’s milk of the economy,” said one respondent from an oil and gas support services company. “We are just starting to see the impact on the wider economy.”

Chinese fuel exporters have canceled some oil-product cargoes slated for export in October, as Asia’s top consumer prioritizes domestic supply during an extended period of upheaval in global energy markets.

Shipments including gasoline and diesel have been affected, according to people involved in shipping and purchasing the cargoes, who asked not to be identified as they aren’t authorized to speak publicly. The prompt spread for gasoline and diesel in Asia — the gap between immediately available cargoes and those for purchase next month — stretched higher late Wednesday as traders learned the news, indicating a tighter market.

(…) any interruption to Chinese exports is closely monitored by buyers and traders at a time when the world is grappling with a supply crunch, thanks to disruptions in Russia and the Middle East. (…)

China’s focus has only increased as the Northern Hemisphere heads into winter, with little sign of fuel exports returning to normal in the Persian Gulf or Russia, which has just extended a diesel export ban. (…)

FYI, from Ian Harnett, co-founder and chief investment strategist at Absolute Strategy Research in the FT:

(…) Take a look at the gap between US Treasuries and US markets earnings yield — the earnings per share of companies divided by the share price. While the US 10-year yield is up to more than 5 per cent, the equity market has an earnings yield of only 3.9 per cent, and the dividend yield is back to its 2000 lows at 1.1 per cent.

Even if you include buybacks alongside dividend income, the total equity yield is just 2.6 per cent — again, close to the 2000 lows.

But it is also this divergence in relative valuations where the investment opportunities arise for longer-term investors with patient capital. While bondholders can now get a 5 per cent return if they hold their 10-year Treasuries to maturity, the kind of returns that equity holders might expect over the same 10-year period is close to zero, based on historic precedent as indicated by the cyclically adjusted price-earnings model developed by economist Robert Shiller.

While this still may not be enough of a return premium for some investors, given the excitement surrounding the prospects for AI-related stocks, it does create more optionality for long-run asset allocators to invest in something other than equities.

image

AI is driving the economy and the stock market, both driving consumer spending but also inflation and bond yields and, perhaps, Fed funds rates. We sure need strong earnings.

But the stock market has also become K shaped as David Rosenberg explains: “The median S&P 500 stock is down more than -15% from the 52-week highs, and yet everyone thinks the stock market has become invincible and impervious to the bond market shock. More than 70% of the S&P 500 is at least -10% below its highs. (…) The KBW Bank Index sagged -1.0% [yesterday] and is down -12.4% from the summertime high.”

Consumer Discretionary, Industrials, Financials, Retail, and Real Estate sub-indices combined are down 8.6% since early August.

MarketWatch concurs:

According to MarketWatch calculations, 80% of S&P 500 companies are at least 10% below their 52-week high — in other words, they’re in a correction — and 39% are at least 20% below.

“So there’s all this rot that’s in the S&P 500, but it’s not in plain sight, [and] you’ve got to wait for the branch to fall off to figure out that the market’s hollow, just like the tree was hollow,” said Gundlach, who is also worried that investors may be facing contagion from a separate set of assets.

“I feel like there’s a direct parallel to all of this in the private markets,” said the investor best known for calling the U.S. housing bust in 2007.

He explained a growing circular investment, in which private-equity firms buy a private-credit unit and then buy an insurer, which in turn buys the loans from the affiliated private-credit company.

Gundlach said those private-equity and private-credit firms keep assuring investors there are no problems, and their quarterly figures often won’t reveal any issues. However, he pointed to one private-credit fund that held assets marked at $100 late last year, then lowered them to between $77 and $78 by the first quarter, meaning the underlying portfolio had dropped in value by nearly 23%. And those funds hold thousands of diversified loans, therefore revealing major, but hidden, losses, he said.

“I think that all these things are creating an awareness that’s building that everything isn’t just fine,” Gundlach said. (…)

He noted that over a dozen prior S&P 500 pullbacks since 2000, the ICE Dollar Index has gained 8% to 10% each time, but after the April correction of 2025 the dollar went down for the first time. “That’s because people realize that we’re in a different regime and so the dollar will not go up in the next recession,” he said. “[I]t will go down.”

Korea Disputes Trump’s Claim It Agreed to Invest in Alaska LNG

South Korea has pushed back on the Trump administration’s announcement that the country would invest $54 billion in a liquefied natural gas project in Alaska, saying it had agreed to do so only if the long-stalled venture proves economically feasible.

“What the Korean government agreed with the US is that the Alaska project will proceed only if it is commercially viable,” Industry Minister Kim Jung-kwan said in a televised briefing on Thursday. Seoul had expressed its regret to US Commerce Secretary Howard Lutnick “that what was reported today went beyond what had been agreed,” he said.

President Donald Trump had earlier said Korea would invest in the Alaska project at a White House event on Wednesday. It was part of a pledge by Seoul to invest $200 billion in American energy projects following last year’s US-South Korea trade deal.

The Alaska LNG venture has struggled for decades to secure the binding long-term contracts and investments needed for it to move forward. The project is massive in scale, requiring the construction of an 800-mile (1,287 kilometer) pipeline across the state. Alaska LNG has, however, signed non-binding sales agreements with companies in countries including South Korea, Japan and Taiwan. (…)

If South Korea does participate in the project, the US has agreed to offer it LNG at favorable prices, Kim said.

Under the broader investment agreement, South Korea has insisted that projects meet a commercial viability test before funds are deployed. The test was a central issue in negotiations over how Seoul’s $350 billion US investment pledge would operate. As well as investing in the American energy sector, Seoul agreed to put $150 billion into US shipbuilding.

YOUR DAILY EDGE: 30 September 2026

OIL WATCH

JPMorgan and Goldman See Mideast Oil Flows Near Pre-War Levels

(…) Shipments of crude oil have rebounded to 17.5 million barrels a day, or 98% of pre-war levels, while flows of products such as diesel and gasoline were at 3 million barrels a day, or 58%, according to JPMorgan. (…)

Flows through Hormuz have almost “returned to late-June highs of nearly 13 million barrels a day, led primarily by Saudi Arabia,” JPMorgan said. “But higher crossings should not be mistaken for improved safety — rather, they reflect the industry’s increasing ability to operate under sustained risk.”

Goldman Sachs, meanwhile, said oil exports from the Persian Gulf — including so-called dark flows moved clandestinely — had recovered to 23.3 million barrels a day over the last week, a level in line with the 2025 average. (…)

This month, Treasury Secretary Scott Bessent said 17 million barrels of oil a day “sometimes” transited, while TotalEnergies SE Chief Executive Officer Patrick Pouyanne saw 10 million barrels a day of crude and products getting out. (…)

Why Is Oil at $100 If Trump Is Winning the Battle in Hormuz?

(…) Crude oil exports from regional US allies via the waterway, plus bypass routes, have risen to about 80% of prewar levels. Iran, meanwhile, has seen its own oil exports plunge to zero. (…)

image

Many in the oil market think Trump has been so successful at opening Hormuz that a cornered Tehran would have no other option but to escalate militarily. If attacks on tankers — which still happen daily — aren’t enough to close Hormuz, then Iran would have to go after the source of the shipments: ports, pipelines and, ultimately, the oilfields themselves. (…)

Iran now faces two choices: Either it softens its negotiating position, or it escalates in a way that renders Hormuz irrelevant. The oil market is convinced Iran will choose the latter.

The clock is ticking for Tehran to decide because every day its economy deteriorates further under the American economic blockade.

What’s clearer is that the oil market would be more vulnerable to renewed conflict now than back in March because the US and its allies have already used significant chunks of their strategic reserves and commercial stockpiles of crude and refined products have fallen.

But Trump has demonstrated he has a higher threshold for economic punishment than many, myself included, had expected. Presumably he’s willing to absorb still more pain to force the hand of the Islamic Republic. (…)

Excluding Iranian exports, the countries on the shores of the Persian Gulf were exporting just over 17 million barrels of crude a day before the war broke out on Feb. 28. (…)

Oil bulls remained incredulous about the flows and suggested the US government was inflating the numbers. But over the last few weeks, most have accepted that Hormuz is witnessing a huge tanker flow. Last week, crude shipments rose to a six-month high of 14 million barrels a day, according to Vortexa, an energy markets analytics firm. Other tanker trackers, oil traders and government officials have arrived at similar figures.

The convoys have a huge cost. Putting aside the military expenses, chartering the supertankers costs an average $30 million per crossing, equal to roughly $15 per barrel. To make the convoys work on pure economics, Persian Gulf nations must discount their crude, at times by $20 to $30 below market levels, just to get traders into the game. Is that sustainable? Not likely. (…)

Shipments of gasoline, diesel and jet fuel remain at 50% of normal. The reason? Moving refining products is more expensive than moving crude. On top of that, some of the refineries inside the Persian Gulf that were attacked in the early days of the war have yet to resume operations fully.

image

Put it all together and the oil market is in wait-and-see mode: Either Iran comes to the negotiation table and prices decline a lot; or Tehran escalates attacks on physical energy infrastructure, sending prices a lot higher. Whatever happens, the status quo isn’t sustainable. That’s the price of winning in Hormuz.

Windward’s assessment:

Is Iran Losing Its Grip on Strait of Hormuz Traffic?

Iran has demanded that all Strait of Hormuz transits use the northern corridor through its territorial waters. Rising volumes of Saudi, Iraqi, and Kuwaiti crude, along with UAE volumes that cannot reach Fujairah by pipeline, are instead moving through the southern corridor, which remains under USCENTCOM air defense and naval support.

Windward MIOC assesses that Iran is less able to constrain southern-corridor traffic than it was in mid-summer, as rising crude flows continue despite the threat to individual vessels.

Windward recorded 55 AIS-visible transits from 16 to 23 September, about 94% below pre-war traffic of roughly 910 a week. That count combines AIS detections with at least one satellite imagery pass per day, meaning the true number of transits is almost certainly higher.

Tankers are sailing with AIS switched off, as permitted under maritime conventions when a vessel’s safety or security is at risk.

Exports out of the Arabian Gulf now rely heavily on a “tanker shuttle”. Tankers run through the Strait with AIS off, discharge their cargo via ship-to-ship transfer in the Gulf of Oman, then return inside the Gulf.

With few VLCCs willing to enter the Gulf, exporters are maximizing the volume carried on each crossing, then splitting those cargoes via ship-to-ship transfer onto Suezmaxes in the Gulf of Oman for onward delivery. This reduces the number of vessels that need to make the higher-risk Strait transit.

Tankers are exiting the Gulf in convoys. Between 20 and 22 September, MIOC satellite detections and Vortexa cargo data show 26.72 million barrels of crude exited through the Strait.

Roughly two-thirds of that volume was subsequently moved through ship-to-ship transfers. Spread across those three days, the flow was equivalent to about 8.9 million bpd, although convoy days represent peaks rather than a sustained export rate. For comparison, Vortexa puts Saudi Gulf loadings across 1–27 September at 105.6 million barrels, or 3.9 million bpd.

Saudi tankers are still loading crude at Ras Tanura and Juaymah. Most are doing so with their AIS switched off.

Between January 10 and 16, 35 crude tankers called at the two terminals with AIS on. By September 10–16, that number had fallen to just 2. Vortexa’s cargo data, which does not rely on AIS, shows that loadings over the same periods fell from 52 to 16 per week.

Actual loadings are down, but AIS-visible tanker activity has fallen far more sharply. The gap indicates that much of the apparent collapse in tanker traffic reflects vessels switching off AIS rather than crude movements stopping.

The last visible surge came between 1 and 10 July, as the Memorandum of Understanding period closed. Eight crude tankers left Ras Tanura and Juaymah in that window, declaring voyages to China, South Korea, Duqm, and Fujairah. Seven were VLCCs, six of them operated by Bahri, Saudi Arabia’s national shipping company.

After 10 July, the crude tankers still transmitting AIS were mostly smaller vessels moving between Saudi ports, plus a single VLCC, which called at Juaymah on 15 and 16 August. Across all Saudi Gulf ports, visible crude tanker calls fell from 17 in July to 5 in August and 4 in September, with no VLCC calls at all in September.

Vortexa’s cargo data shows the loadings continued. Crude tanker loads at Saudi Middle East Gulf ports rose from 8 in June to 19 in August and 55 in September (per Vortexa). Fifty of the September loads were VLCCs, including 21 operated by Bahri and 14 by Sinokor, the South Korean shipping group. Almost all loaded with AIS off. We assess that Saudi crude is moving through the Strait on AIS-dark tankers.

Is Iran Losing Its Grip on Strait of Hormuz Traffic?

With East-West pipeline flow reduced after the Petroline attack, less Saudi crude can reach the Red Sea, and Saudi Arabia has shifted exports back to its Gulf terminals. Vortexa puts Saudi Gulf loadings at 3,911 kbpd for 1 to 27 September, more than four times August’s 933 kbpd and 39% below January’s pre-war 6,385 kbpd.

Even so, Gulf loadings remain well below pre-war levels. Middle East Gulf crude exports have recovered sharply since August, but VLCC availability remains constrained. As the East-West pipeline recovers, Saudi Arabia is likely to shift more crude back to Yanbu while tensions persist in the Strait of Hormuz.

Vortexa tracks 33 September cargoes from Saudi Gulf terminals, about 58 million barrels, bound for China and India, more than three times August’s 17 million barrels. Some of the 33 were shuttled via ship-to-ship transfer off Fujairah and Oman, so the vessel that loaded the crude is not always the vessel delivering it, and the final destination can change.

Windward Maritime AI™ platform data identifies declared destinations for 13 of the 33 cargoes. Eight are broadcasting destinations in China, with ETAs between 4 and 15 October. Five are broadcasting destinations in India, and most had already arrived at Vadinar and Sikka as of 28 September.

Iran retains the ability to strike individual vessels. AL MARYAH (IMO 9393682) and LR STEPHANIE (IMO 9282625) were hit between 20 and 22 September, the same three-day period in which 26.72 million barrels of crude exited through the Strait. Laden Gulf exits continued despite the strikes. MIOC assesses that, under current conditions, such attacks are more likely to cause short-lived disruptions than a sustained reduction in exports.

The recovery in crude flows is real, but remains vulnerable to further escalation.

Confused smile A lot of confusing numbers, some days or weeks being better than others. Windward’s 8.9Mb/d “peak” volume seems more credible, roughly in line with Total’s assessment but much lower than JPM and GS.

Chinese buying has returned but will it continue at current prices/costs?

image image

What will Iran do in October, just before the midterms?

What about other key products normally flowing through Hormuz?

Speaking of midterms:

The US ordered another release of oil from emergency reserves — and urged European nations to do likewise — as the Trump administration grapples with fuel prices that are surging less than two months before the midterm elections.

The US will offer up to 40 million barrels from the Strategic Petroleum Reserve, according to a statement from the Department of Energy, in what will be the last of the nation’s 172-million-barrel contribution to the coordinated release of oil from reserves around the world since the start of the Iran war. (…)

The SPR is projected to fall to its lowest level since 1982 once the latest release is completed. Federal law bars non-emergency drawdowns once inventories fall below 252.4 million barrels, while a 1981 report from the US Government Accountability Office advised against releases below 250 million barrels except in a “very severe emergency.” (…)

Russia Extends Diesel-Export Ban as Global Supply Squeezed

Russia extended a ban on most diesel exports through October, further tightening the global market just as demand rises ahead of the Northern Hemisphere winter and the US considers its own restrictions on exports.

Moscow enacted the ban on diesel exports for producers in July as a wave of Ukrainian strikes against its refineries dragged oil-processing rates to multiyear lows. The export curbs, initially envisaged to last just a matter of weeks, were subsequently extended through August and then to the end of September as the attacks continued.

Prior to the restrictions and Ukraine’s intense attacks on refineries, Russia accounted for roughly 10% of global seaborne diesel supplies. Withdrawing those volumes from the market compounded the effects of the disruption to flows in the critical Strait of Hormuz, driving up prices of the fuel that’s used to power trucking, farm equipment and industry around the world. As pump costs hit records in America, President Donald Trump has mulled a ban on US exports.

Analysts have warned that such a move could supercharge overseas prices, especially in Europe.

The fuel’s premium over crude oil is currently at around $82 a barrel in Europe, fair-value data compiled by Bloomberg show. That compares with about $28 a barrel at the end of February, before the US and Israel launched the war on Iran and Ukraine stepped up its attacks on Russian refineries. (…)

China’s Economic Activity Rebounds With Stimulus Lifting Outlook

The official manufacturing purchasing managers’ index was 50.1 in September, up from 49.8 in August and in line with the forecasts of economists surveyed by Bloomberg.

The non-manufacturing measure of activity in construction and services unexpectedly returned to positive territory at 50.2, the National Bureau of Statistics said Wednesday. Private surveys of manufacturing and services also showed a bigger-than-forecast improvement in September.

image

In a sign of stronger momentum for the country’s export-oriented firms, the RatingDog China manufacturing PMI rose more than forecast to 52.1 in September, its highest in five months.

The private survey results are based on a smaller sample and have tended to be stronger than those from the official poll as exports stayed strong.

The RatingDog China services PMI rose to 51.6 from 51.4 in August, according to a statement published Wednesday. (…)

More details from RatingDog:

An improvement in client demand, driven partly by interest among some companies in accumulating safety stock, had reportedly supported the latest expansion in overall new orders among Chinese manufacturers. This was accompanied by growth in new work from abroad amid reports of robust market conditions overseas.

Notably, total new work rose at the fastest rate in five months, while the upturn in new export orders was the best seen since February, with both respective indices signalling solid growth overall.

Among the three monitored sub-sectors, consumer goods makers recorded the strongest increases in new orders and output.

Turning to prices, average cost burdens continued to rise among manufacturers during September. The rate of input price inflation was the strongest seen in four months and solid. According to firms, higher raw material prices, particularly for metals and oil, were the main drivers of inflation.

As a result, Chinese manufacturers lifted their selling prices slightly in September, following a marginal reduction in August. Export charges likewise rose slightly.

Higher service sector activity across China was driven by greater inflows of new business in September. Total new orders expanded at a solid rate that was the quickest since June, supported by successful business development efforts among firms and a broad improvement in demand conditions.

The survey data also pointed to stronger external demand, as growth of new export business accelerated for the first time in three months. The latest increase in new work from abroad also extended the current sequence of expansion to five months; the longest since 2024.

image

AI CORNER
Biggest US Grid’s Data-Center Plan Accepted With 5-Month Pause

The Federal Energy Regulatory Commission said Tuesday that it would accept the filing of grid operator PJM Interconnection LLC’s plan to procure new capacity but would suspend it until Feb. 28 and establish a paper hearing on unresolved issues. The regulator also encouraged PJM to submit a new filing that answers the issues it raised, which could shorten the delay.

The artificial intelligence boom is driving the fastest growth in power demand in decades for PJM, which is home to the biggest US concentration of digital warehouses. The regulator agreed PJM needs more generation quickly and approved many parts of the operator’s plan, but said cost allocation, collateral and exit-rule issues need to be fixed before it can proceed.

“This Commission will not be forced into accepting a deeply flawed, 11th-hour procurement mechanism with billion-dollar implications for consumers,” Commission Chairperson Laura Swett said in the order. “We are prepared to promptly act on a subsequent proposal that addresses the concerns raised in this order and meets the standards of the Federal Power Act. The region’s reliability hangs in the balance.” (…)

Meanwhile

OpenAI’s annualized recurring revenue (ARR) is approaching $70B, surging from $40B in July (Bloomberg) and from around $20B at the end of 2025.

Anthropic’s ARR reached $65B as of late July 2026, up from $47B in May 2026 and $9B at the end of 2025. Some trackers evaluate its total run rate as high as $74-$76B by late Q3.

Combined revenues went from ~$30B end of 2025 to ~$145B currently!!!

Meanwhile

Trump and House Speaker Mike Johnson yesterday said that AI-related CEOs had signed a statement pledging to keep AI technology safe. The document includes voluntary principles such as internal controls to monitor model development, external model reviews and notifications to the board of directors about those safety efforts.

Everything “voluntary” while all in an existential race…

But no worries: “Trump called it a “constitution” that he thinks is “morally binding.”

Respecting the constitution? Morally binding? Trump?