The enemy of knowledge is not ignorance, it’s the illusion of knowledge (Stephen Hawking)

It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so (Mark Twain)

Invest with smart knowledge and objective odds

THE DAILY EDGE: June 27, 2023

Bank of England Outpaces Peers With Rate Rise of Half Percentage Point Lending rate rises to highest level [5%] since April 2008

(…) Norway’s central bank also increased its core lending rate by half a percentage point Thursday, while Switzerland hiked its benchmark rate by a quarter point. Both warned of further increases in the coming months.

The European Central Bank, the Bank of Canada and the Reserve Bank of Australia have all raised rates by a quarter percentage point in recent weeks. The Federal Reserve kept its key rate unchanged but also signaled it isn’t done raising rates. (…)

Policy Error?

Source: BCA Research via The Daily Shot

Three Uncomfortable Truths For Monetary Policy (IMF)

Excerpts from Gita Gopinath’s yesterday speech at the European Central Bank’s annual conference. You can jump to the last paragraph for the clear message.

(…) Uncomfortable Truth #1: Inflation is taking too long to get back to target.

Inflation forecasters have been optimistic that inflation will revert quickly to target ever since it spiked two years ago. (…) inflation sits well above previous forecasts. (…)
Despite repeated forecast errors, markets remain particularly optimistic that inflation in the euro area and most advanced economies will recede to near-target levels relatively quickly.

These disinflation hopes—likely fueled by the sharp drop in energy prices—underpin expectations that policy rates will decline soon, despite central bank guidance to the contrary. Surveys of market analysts paint a similar picture and suggest that inflation is likely to come down without much of a hit to growth. It is useful to bear in mind that there is not much historical precedent for such an outcome.

Setting aside forecasts, the fact is that inflation is too high and remains broad-based in the euro area, as in many other countries. While headline inflation has eased significantly, inflation in services has stayed high, and the date by when it is expected to return to target could slip further. (…)

The combination of tight labor markets with a still solid stock of household savings and residual pent-up demand may be behind the resilience in activity we have seen so far.

Second, despite the large increase in the nominal policy rate, financial conditions may not be tight enough which impedes monetary policy transmission. (…) real rates using market-based measures of inflation expectations are still quite low, and near-term real rates using household measures are likely negative.

Lastly, the pandemic has likely lowered potential output and productivity, which would also help explain some of the upward pressure on inflation.

What is worrisome is that sustained high inflation could change inflation dynamics and make the task of bringing inflation down more difficult. Given the massive decline in real wages since the pandemic, some wage catchup is to be expected. All else equal, if inflation is to fall quickly, firms must allow their profit margins—which have shot up during the past two years—to decline and absorb some of the expected rise in labor costs. But firms may resist this, especially if the economy remains resilient, while workers may demand payback for their real wage losses. Such dynamics would slow inflation reduction and likely feed into expectations and increase susceptibility to further upside cost or resource pressures. (…)

Ultimately, it is up to central banks to deliver price stability irrespective of fiscal stance. With underlying inflation high and upside inflation risks substantial, risk management considerations in the euro area suggest that monetary policy should continue to tighten and then remain in restrictive territory until core inflation is on a clear downward path.

The ECB—and other central banks in a similar situation—should be prepared to react forcefully to further upside inflation pressures, or to evidence that inflation is more persistent, even if it means much more labor market cooling. The costs of fighting inflation will be significantly larger if a protracted period of high inflation boosts inflation expectations and changes inflation dynamics.

There are also some downside risks to inflation that could arise, for instance, from the recent unwinding of supply chain disruptions and fall in energy prices. The effect of the recent tightening in monetary policy is still working through the system. While central banks must be vigilant about not easing prematurely, they should be prepared to adjust course if a chorus of indicators suggest that these downside inflation risks are materializing.

Uncomfortable Truth #2: Financial stresses could generate tensions between central banks’ price and financial stability objectives.

If inflation persists and central banks need to tighten much more than markets expect, today’s modestly tight financial conditions could give way to a rapid repricing of assets and a sharp rise in credit spreads. We’ve seen during the past year how, under some circumstances, policy tightening can come with significant financial stresses, including in Korea, the UK, and more recently in the US.

For the euro area, tighter monetary policy may also have diverse regional effects, with spreads rising more in some high-debt economies. Higher rates can also amplify other vulnerabilities arising from household indebtedness and a large share of variable rate mortgages in some countries.

This brings me to the second uncomfortable truth:, Financial stresses could generate tensions between central banks’ price and financial stability objectives. This is because, while central banks can extend broad-based liquidity support to solvent banks, they are not equipped to deal with the problems of insolvent borrowers. (…)

While central banks must never lose sight of their commitment to price stability, they could tolerate a somewhat slower return to the inflation target to avert systemic stress. (…)

Such a shift in the reaction function could leave the central bank behind the curve in fighting inflation – as, for instance, happened when the Federal Reserve decided to ease policy in the mid-1960s on fears of a credit crunch, even as inflation pressures were building.

Put simply, while separation is achievable in principle, it is challenging in practice, and must not be taken for granted. (…)

Uncomfortable Truth #3: Central banks are likely to experience more upside inflation risks than before the pandemic.

(…)
Looking forward, central banks are likely to experience more upside inflation risks than before the pandemic for two sets of reasons. Some of the upside risk reflects structural changes affecting aggregate supply—heightened by the pandemic and the war in Ukraine—and that may result in larger and more persistent shocks. In addition, we have also learned the lesson that the Phillips Curve is not reliably flat.

Turning first to structural changes, there is a substantial risk that the more volatile supply shocks of the pandemic era will persist. Despite a considerable easing of pandemic-related supply pressures, the restructuring of global supply chains that was intensified by the pandemic and war, coupled with geo-economic fragmentation, may cause ongoing disruptions to global supply.

Many countries are turning to inward-looking policies, which raise production costs, and, ironically, make countries less resilient and more susceptible to supply-side shocks (WEO, April 2022). (…) the number of new restrictions on trade and foreign direct investment (FDI) imposed on EU countries ratcheted up markedly during the pandemic. EU countries have also increased their own restrictions on in-bound trade and FDI.

The increasing physical and transition risks from climate change are also likely to amplify short-term fluctuations in inflation and output. Delays in achieving Paris Agreement goals increase the risk of a disorderly transition and serious disruptions to energy supply, which could boost inflation sharply and create more difficult tradeoffs for central banks.

The pandemic has also taught us more about the Phillips Curve. Evidence increasingly shows that nonlinearities may become pronounced at high levels of resource utilization, so that inflation is more sensitive to resource pressures. Difficulties in measuring economic slack may also make it harder for policymakers to gauge the point at which inflationary pressures will escalate.

(…) Central banks may need to react more aggressively if the supply shocks are broad-based and affect key sectors of the economy, or if inflation has already been running above target, so that expectations are more likely to be dislodged. They may also need to react more aggressively in a strong economy in which producers can pass on cost hikes more easily and workers are less willing to accept real wage declines. And they should be confident that the shocks are mainly supply-driven, rather than fueled by strong demand.

While the focus now is on high inflation, what we’ve learned about the Phillips Curve also has important implications for the monetary policy response to future periods of below-target inflation. Some refinement may be needed to the “lower-for-longer” strategies—used widely after the Global Financial crisis—that typically involved maintaining policy rates at the effective lower bound until inflation reaches or overshoots its target. Lower-for-longer strategies may still be desirable under some conditions, particularly for an economy in deep recession and facing chronically low inflation.

But the pandemic experience suggests that policymakers should be more cautious about calibrating policy to generate a persistent fall of unemployment below the natural rate U* when inflation is running only modestly below target—say between 1.5 percent and 2 percent. And there could well be a case for preemptive tightening under these conditions if resource pressures appear tight and there is a material risk that new shocks—such as fiscal expansion—could push the economy to overheat.

By allowing for a more gradual pace of tightening, a preemptive approach would also reduce the financial stability risks likely to accompany a rapid exit from low rates (the second uncomfortable truth).

Refining monetary policy strategies also calls for adjusting the use of tool. Forward guidance is a helpful tool, and conditional promises can enhance its impact. But such promises should be tempered by escape clauses if developments unfold much differently than expected. The forward guidance provided by central banks during the pandemic may have been too much of a straitjacket and prevented a faster reaction to inflation surprises.

The costs and benefits of quantitative easing (QE) should also be reconsidered. QE will likely remain a critical tool should central banks face circumstances like the post-GFC period in which unemployment runs high and inflation low even though policy rates have hit their floor. But there should be more wariness of using QE—and accompanying it with forward guidance promising low policy rates—when employment has largely recovered, and inflation remains only modestly below target. Maintaining QE in such circumstances increases the risk that the economy will overheat and that policy will be forced into a sharp U-turn.

So, when we consider the monetary policy of tomorrow, it is important to recall today’s lessons: First, take a closer look at supply shocks before deciding to simply “look through” them. Second, be careful about running the economy hot, and be ready to act preemptively if it does—even if inflation isn’t yet burning brightly. Third, make sure that forward guidance is coupled with escape clauses; and fourth, be more cautious about deploying QE outside of a recession.

To conclude, now is the time to face the three uncomfortable truths that I’ve outlined. Inflation remains sticky; financial stresses could make price and financial stability a difficult balancing act; and more upside inflation risks will likely come our way. I am heartened by the actions that the ECB—and many other central banks—have taken to tackle inflation. But the battle won’t be easy—financial stresses may intensify, and growth may have to slow more. Even so, we know that we can’t have sustained economic growth without a return to price stability. The good news is that while low inflation may seem elusive, it is certainly no stranger, and central bank actions can deliver it. Unlike the characters in Godot, we are not waiting for a potential stranger to arrive; we are inviting an old friend to return.

Not waiting for Godot, fixed income investors are already in risk management mode as Almost Daily Grant’s reports:

Full faith in credit?  Nearly two-thirds of this year’s junk bond supply has been backed by specific collateral, PitchBook-tabulated data from last week show. That’s far and away the highest proportion since at least 2005, surpassing the 37% share seen in 2009 following the acute phase of the financial crisis. With post-pandemic policy tightening pushing benchmark borrowing costs to decade-plus long heights, investors “want to be a little more defensive in an uncertain environment, so they’re buying this secured paper,” Randy Parrish, head of public credit at Voya Investment Management, commented to The Wall Street Journal.

Risk aversion is similarly on display in the floating-rate realm. Issuance of syndicated leveraged loans registered at just $31.3 billion from January through May, marking the weakest primary activity since 2009, when the loan market stood at less than half of its current $1.4 trillion size.

Underscoring the changing market dynamics: only a solitary single-B-minus rated loan backing a leveraged buyout has priced in 2023, compared to 14 such issues in the same period last year.  That comes as the share of single-B-minus issues within the Morningstar LSTA Leveraged Loan Index has ballooned to nearly 30% from 14% on the eve of the pandemic. Meanwhile, borrowers looking to refinance are paying a pretty penny to do so, with the market-wide 9.68% average effective yield representing the highest since Y2K.

Accordingly, it is perhaps no surprise that fewer than 13% of loans outstanding in the Morningstar gauge in April 2022 had been repaid 12 months later, half of the ratio seen last year and the lowest such share since 2009.  The raft of aging vintages may portend building distress, PitchBook notes, as loans have historically defaulted at a 1.4% rate within one year of origination but at a 5.4% clip by year four.

(…) UBS strategist Matthew Mish wrote Wednesday that he anticipates private credit defaults will reach as high as 10% early next year, compared to 8% and 6% for leveraged loans and junk bonds, respectively, as the impact of higher rates takes hold within the opaque asset class (the Proskauer Private Credit Default Index reached 2.15% in the first quarter, up from 1% in the last three months of 2021).  A recession-induced easing cycle could help bring private credit defaults to 5% by late 2024, Mish reckons, though “if rates stay higher for longer and ultimately lead to a less mild recession, we could see a longer cumulative default scenario.”

Analysts at Moody’s express similar concern, warning on Friday that private credit now faces its “first serious challenge.” Loan vintages from the euphoric 2021 era, “when optimism was high, the credit market was most frothy and there was greater tolerance for looser covenants,” could prove particularly problematic, the rating agency believes, as its in-house liquidity stress indicator has risen markedly from a year ago.  Lenders can likewise expect lower recovery rates in the case of future defaults, owing to the steady erosion of covenant strength during the lengthy post-crisis bull market.

FYI:

  • Almost half of market participants in a Bloomberg survey expect at least two more rate hikes. That’s a remarkable shift for a market that was pricing in cuts in 2023 as recently as this month.
  • A soft landing now appears elusive, though the US may be stuck in a pre-recession limbo for the rest of the year. That’s probably why many investors see fixed-income outperforming commodities and stocks. (Bloomberg)

  • Ford plans to fire hundreds of salaried US workers—mostly engineers—this week, people familiar said. 
  • Goldman Sachs has started cutting managing directors across its global operations as part of a cost saving drive amid a dealmaking slump. It’s slashing around 125 positions, including some in investment banking, after deal values fell more than 40% this year to $1.2 trillion. These cuts follow reports of similar cost saving exercises at other banks. JPMorgan cut around 40 investment bankers, according to reports last week, while Citigroup is planning hundreds of cuts across the company this year.
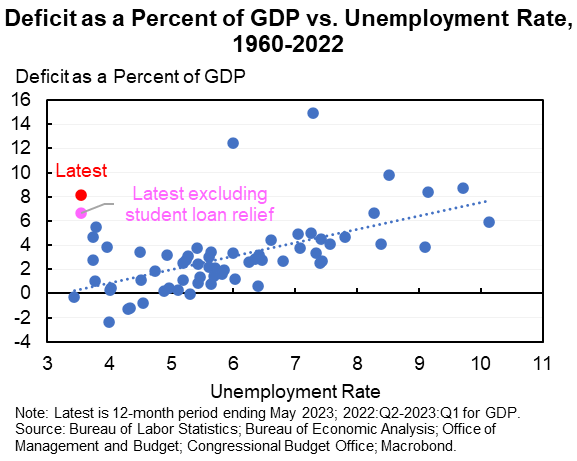
  • Over the last 12 months the budget deficit has been 8% of GDP (6% ex student loans) while the unemployment rate has averaged 3.6%. Historically this low an unemployment rate is associated with a balanced budget. @jasonfurman
Image

TECHNICALS WATCH

It has now been more than three months since the S&P 500 has pulled back at least 3%, one of the longest such stretches since World War II, Deutsche Bank research shows. The average weekly move for the benchmark has been less than 1% in either direction since the end of March, according to FactSet. In late 2022, the index averaged swings of roughly 2.6% each week.

Others say technical dynamics in the stock and options market have pushed volatility lower. One measure of how tightly stocks within the S&P 500 are moving together, known as correlation, has fallen to some of the lowest levels on record in the past three months, according to Deutsche Bank, a sign that stocks and sectors are moving in dramatically different directions.

This “has been a key driver of lower index [volatility] and suggests a decline in the pricing of macro concerns,” the firm’s analysts wrote in a recent note to clients.

Correlations within stocks haven’t been this low since late 2017 and early 2018, around the time a burst of volatility known as “Volmageddon” jolted markets. If stocks across the S&P 500 start moving in lockstep once again, that would drive volatility higher. (…) (WSJ)

THE DAILY EGE: June 26, 2023: Unfinished Business!

Note: I will be traveling until June 27, with limited posting whenever possible given limited time, equipment and time zone constraints.

Flash PMIs

US economic upturn slows in June as dependence on services grows

US companies signalled a further expansion of business activity at the end of the second quarter, although the rate of growth slowed to a three-month low. Manufacturers reported a renewed contraction in production while service providers saw a slower, but still solid, upturn in output. Jobs growth meanwhile sank to the slowest since January. Although higher wages added to firms’ costs, selling price inflation for goods and services hit a 32-month low.

At 53.0 in June, the headline S&P Global Flash US PMI Composite Output Index indicated a fifth successive monthly increase in activity across the private sector. The latest index figure was below the 54.3 seen in May and signalled the slowest upturn in output since March. Manufacturers weighed on the overall expansion, as goods producers recorded a solid decline in production after three months of growth.

image

Factory production fell at the steepest rate since January. Robust growth continued to be recorded in the service sector, albeit with the rate of expansion cooling from May’s 13-month high.

Driving the trend in output was a further rise in new orders at firms. Although slightly softer than that seen in May, the rate of growth remained solid and was the second-fastest in just over a year. The upturn was entirely driven by service providers, however, as manufacturers reported the sharpest drop in new orders since December, citing weak customer confidence and destocking by clients. Service sector firms noted that strong demand conditions and referrals contributed to growth of new business, which rose at a rate only marginally below May’s 13-month peak.

A similar trend was seen for international demand, as manufacturers saw a sharp fall in new export orders while service sector firms recorded another marked monthly upturn in new business from abroad.

Following a loss of momentum in May, price pressures gained intensity in June. The rate of cost inflation across goods and services picked up to a robust pace. The reigniting of cost inflationary pressures was driven by the service sector amid increased wage bills. Although quicker than the series trend, the rate of increase was much softer than the average seen over the last two years as manufacturing firms recorded a further decrease in input prices amid falling raw material prices, which fell at the fastest rate since May 2020.

Despite a sharper rise in cost burdens, US firms raised their selling prices at the slowest pace since October 2020. The increase in manufacturing factory gate charges was the softest for three years, as firms sought to boost sales and pass on supplier price falls. While service sector charges continued to rise at a pace above the survey’s pre-pandemic average, the rate of inflation cooled further from April’s recent peak to the slowest since January.

Firms continued to see an increase in employment in June, extending the current sequence of job creation that began in July 2020. Success in hiring for long-held vacancies and greater new orders reportedly spurred the rise. The pace of employment growth nevertheless eased to the softest since January, reflecting a combination of lower demand for staff and poor candidate availability.

Weak demand conditions led to a further marked decrease in backlogs of work at manufacturing firms, though service providers registered a renewed (though marginal) rise in work outstanding.

Diverging trends in demand conditions across the manufacturing and service sectors were reflected in respective degrees of confidence in the outlook for output over the coming year in June. Confidence dipped to a six-month low among manufacturers amid concerns regarding inflation and lower sales. Services firms, however, reported the strongest level of positive sentiment since May 2022.

At 54.1, the S&P Global Flash US Services Business Activity Index indicated a further solid expansion in output at services firms in June. The upturn was reportedly led by strong customer confidence and new client acquisitions. The rate of growth was slower than that seen in May (index at 54.9) but was the second-fastest since April 2022.

Demand conditions at service providers remained robust, as new orders increased at a strong rate in June. Firms noted a greater inclination to spend among customers, with client referrals also rising. The pace of expansion was broadly in line with May’s 13-month high. New export orders also rose, signalling back-to-back monthly increases in external client demand.

Service sector firms registered a quicker rise in input prices at the end of the second quarter. The rate of cost inflation was the steepest for five months, as companies stated that greater wage bills in particular placed further pressure on business expenses. Conversely, companies sought to remain competitive and drive sales which led to a slower uptick in output charges during June.

Services firms continued to hire amid greater new orders. That said, the rate of job creation eased to the weakest since January amid challenges replacing voluntary leavers.
In response to problems hiring sufficient new staff, the level of outstanding business at service providers increased in June. The upturn followed a decline seen in May, though was only marginal overall.

Strong demand conditions helped support an uptick in business confidence in June. Firms were upbeat in their expectations for output over the coming year, with the level of optimism the highest since May 2022.

The S&P Global Flash US Manufacturing PMI posted 46.3 in June, down from 48.4 in May, to signal a sharper deterioration in operating conditions across the manufacturing sector. The decline in the health of the sector was the most severe in 2023 to date and stemmed from a marked reduction in new orders.

Manufacturers recorded the fastest rate of contraction in new orders since December 2022, with weak demand linked to muted customer confidence. Some firms also noted that sufficient stock levels at clients had led to lower new orders. Similarly, foreign client demand remained subdued. Although easing from that seen in May, the pace of contraction in new export orders was steep overall.

Cost pressures continued to dwindle across the manufacturing sector, as suppliers sought to boost their sales and offer reduced prices. The pace at which input prices fell was the quickest since May 2020.

The pace of selling price inflation was only fractional and the slowest in the current sequence of inflation that began just over three years ago. Weighing on firms’ ability to hike prices was weak demand and efforts to stay competitive.

In line with subdued demand, firms sought to run down their stocks and reduce input purchasing in June. Input buying fell at the steepest rate since January, and both pre- and post-production inventories declined sharply.

Greater success in finding suitable candidates allowed firms to expand their workforce numbers in June, despite concerns surrounding future demand conditions. The rate of job creation slowed slightly but remained among the fastest in a year. Increased employment and lower new orders led to a substantial decline in backlogs of work.

Although strongly upbeat in their expectations, manufacturers moderated their confidence regarding the outlook for output over the next year in June. The degree of optimism was the weakest in 2023 so far, amid customer hesitancy and inflationary concerns.

Commenting on the US flash PMI data, Chris Williamson, Chief Business Economist at S&P Global Market Intelligence said:

“The overall rate of expansion of business activity in the US remained robust in June, consistent with GDP rising at a rate of 1.7% to put second quarter growth in the region of 2%.

“Growth remains dependent on service sector spending, however, with manufacturing slipping back into decline after three months of growth. While improving supply conditions had helped boost manufacturing production in prior months, an increasingly severe downturn in new orders mean factories are running out of work.

“The situation is brighter in the service sector, where demand is proving resilient and the recent pause in rate hikes appears to have helped boost business optimism for the year ahead.

“The question remains as to how resilient service sector growth can be in the face of the manufacturing decline and the lagged effect of prior rate hikes. Any further rate hikes will of course have a further dampening effect on this sector which is especially susceptible to changes in borrowing costs.

“The tightness of the labor market remains a concern, and upward wage pressure remains a key driver of higher costs in the service sector. However, it is encouraging to see the overall rate of selling price inflation for goods and services drop to the lowest since late 2020 in a sign that the Fed is winning its fight against inflation.”

Eurozone: Inflation pressures cool as economic upturn fades

Eurozone business output growth came close to stalling in June, according to the latest HCOB flash PMI survey data produced by S&P Global, pointing to renewed weakness in the economy after the brief growth revival recorded in the spring. Inflows of new orders fell for the first time since January, employment growth slowed and future output expectations also deteriorated. More encouragingly, the slowdown was accompanied by a marked cooling of inflationary pressures. Input costs rose at the slowest rate since December 2020 and average selling prices for goods and services rose at the weakest rate since March 2021

The seasonally adjusted HCOB Flash Eurozone Composite PMI Output Index, based on approximately 85% of usual survey responses, fell from 52.8 in May to 50.3 in June, its lowest since January. Although recording an expansion of output for a sixth consecutive month in June, the latest increase was only marginal and far weaker than the gains seen in the previous four months to signal a considerable loss of growth momentum. The 2.5 point drop in the index was the largest recorded for a year.

image

The slowdown had been signalled in advance by a near-stagnation of new business inflows in May. With the new business trend measured across goods and services worsening further in June, as new orders dropped for the first time since January, the deteriorating demand environment signals downside risks to output in July.

Manufacturing remained the principal area of weakness, with factory output falling for a third straight month and at the fastest rate since last October. The resulting steep production decline was driven by an increasingly sharp downturn in new orders for goods, which fell to the greatest extent since last October.

Growth of service sector output meanwhile slowed sharply as the recent resurgence in spending on services lost momentum. Business activity in the service sector grew at the slowest rate since January, down sharply from April’s recent peak, with growth of new business dropping to register only a modest increase in demand, contrasting with the strong gains seen in the three months to May.

Backlogs of work fell at the steepest rate for seven months, reflecting the sustained (albeit moderating) output growth at a time of falling inflows of new work, and have now fallen for three successive months. Backlogs fell at the sharpest rate for three years in manufacturing and slipped into decline in the service sector for the first time since January.

Falling backlogs tend to signal excess capacity, and are hence typically a precursor to downward pressure on payroll numbers. Hence employment growth slowed for a second consecutive month in June, with the rate of job creation down to its lowest since February. Manufacturing headcounts were cut for the first time since January 2021 and jobs growth in the service sector waned for a second month in a row to sit at the lowest since March, albeit remaining strong by historical standards.

Manufacturers notably also adjusted to the prospect of lower production in the coming months by greatly reducing their purchases of inputs. Barring the COVID-19 lockdowns of early-2020, June saw the largest reduction in input buying by factories since 2009. Reduced purchasing of inputs by manufacturers took pressure off supply chains, which in turn led to faster supplier delivery times, which have improved in recent months to a degree not seen since 2009.

Falling demand led to increasing discounting in manufacturing, resulting in average input prices dropping in the factory sector for a fourth successive month and at the steepest rate since July 2009. While service sector input costs continued to rise at a rate well above the survey’s long-run average, buoyed in particular by wage pressures, the rate of increase moderated to the lowest since May 2021. Measured across both sectors, the rate of input cost inflation sank sharply in June, down for a ninth straight month to its lowest since December 2020.

Slower cost growth fed through to lower selling price inflation. Average prices charged for goods and services rose at the slowest rate for 27 months in June, having been on a broad easing trend over the past year but showing an especially large drop in momentum in June (one of the largest points falls in the index since 2008 excluding the early-2020 pandemic lockdown months). Prices charged for goods leaving the factory gate fell for a second successive month, showing the largest decline for three years. Average rates levied for services rose sharply again, though the rate of inflation cooled by the greatest extent since 2008 barring the early-2020 lockdown months.

Optimism about the year ahead fell in June to the greatest extent since last September, sliding to its lowest level so far this year. Expectations for the year ahead have deteriorated especially markedly in manufacturing, down to a seven-month low in June, but have also sunk to a six-month low in the service sector. The overall degree of confidence has dropped far below the long-run average in both sectors. Although energy and supply chain worries have eased since late last year, June has seen a further escalation of concerns over demand growth, and in particular the impact of higher interest rates, and the resulting possibilities of recessions both in domestic markets and further afield.

Looking at growth across the euro area, the weakness was led by France, where output fell for the first time since January as strikes reportedly added to the economy’s headwinds. The resulting drop in output was the steepest since February 2021 and broad-based across manufacturing and services. However, growth also came close to a stand-still in Germany, contrasting with robust expansions in the three months to May, as an increasingly severe manufacturing downturn was accompanied by slower service sector growth. The rest of the region as a whole meanwhile reported the slowest output growth for five months, the expansion continuing to lose momentum from the solid gains seen in March and April due to a combination of marked factory output losses and weaker service sector growth.

Commenting on the flash PMI data, Dr. Cyrus de la Rubia, Chief Economist at Hamburg Commercial Bank, said:

“If the ECB only had to control goods prices, then Frankfurt would toast the end of inflation, because even in June the PMI survey shows that purchasing and selling prices have fallen significantly. Moreover, given the recession in manufacturing indicated by the PMI, one would start with interest rate cuts. But this picture is incomplete. In the more important part of the economy, the private services sector, prices continue to rise, and that’s why the core rate of inflation has been so slow to decline.”

“In addition to the persistent discrepancy that has already been observed for several months between manufacturing on the one hand and services on the other, there are also clear regional differences. In France, for example, activity in the service sector contracted in June according to the PMI survey, whereas in Germany it continues to expand, albeit at a slower pace. This is also reflected in new orders, which are falling in France but rising in Germany – again at a declining rate. High inflation and more difficult financing costs are cited as reasons for this weakness in France, which may also have suffered economically from intense strike and protest activity in spring.”

“After Eurozone GDP fell for the second time in a row in the first quarter, the probability has increased somewhat that the GDP change will again carry a negative sign in the current quarter, due in part to weak services activity in France. Even if our baseline scenario of slightly positive Eurozone growth in the second quarter still becomes reality, the downward trend in the Composite PMI points to a difficult second half of the year as companies across all sectors face deteriorating order books.”

Japan: Business activity growth slips to four-month low in June

The headline au Jibun Bank Flash Japan Manufacturing Purchasing Managers’ Index™ (PMI)® fell from 50.6 in May to 49.8 in June, pointing to renewed deterioration in the health of the sector. Japanese goods producers signalled fresh declines in output and new business, though rates of contraction were only mild. New export orders fell at a solid pace that was the steepest since February.

image

Amid the subdued demand environment, average supplier performance improved further in June. Though only slight, the rate at which delivery times shortened was the quickest recorded since March 2016.

Inflationary pressures remained on a downward trajectory at the end of the second quarter. Input costs rose at the softest pace since February 2021, while selling price inflation cooled to a 21-month low.

The au Jibun Bank Flash Japan Services Business Activity Index slipped from a record-high of 55.9 in May to 54.2 in June, signalling the softest upturn in activity for four months but one that was still strong overall. The respective indices for total new business and new export orders also moderated from their all-time highs in May but remained consistent with solid growth. The sustained improvement in demand conditions was often linked to a further revival in customer numbers and spending as the impact of the COVID-19 pandemic continued to wane.

Prices data meanwhile showed a further sharp rise in average input costs, despite the rate of inflation dipping to a 15-month low. Prices charged inflation meanwhile moderated to the weakest since January.

image

To summarize:

  • The Goods economy remains in a worldwide recession that is gathering pace. On manufacturing new orders, June saw a ‘marked reduction” in the U.S., a “sharp downturn” in the Eurozone and Japan new export orders falling “at a solid pace”. The North American Covid splurge on goods is correcting and impacting worldwide as Chinese demand is no offset.
  • Goods disinflation continues: “Weighing on firms’ ability to hike prices was weak demand and efforts to stay competitive.” While actually deflating in the Eurozone, goods prices are still rising, albeit very slowly, in the USA.
  • Importantly, S&P Global’s June Services PMI only slipped from 54.9 to 54.1 and “was the second-fastest since April 2022”, confirming its buoyant May survey which was much stronger than the ISM’s 50.3 print that most people elected to focus on. “Demand conditions at service providers remained robust, as new orders increased at a strong rate in June. The pace of expansion was broadly in line with May’s 13-month high.”
  • U.S. services inflation seems to be slowing but “continued to rise at a pace above the survey’s pre-pandemic average”.

While many people are focusing on used car prices, purchasing managers, right on the front line of the economy, are experiencing “the steepest rate of cost inflation for five months as companies stated that greater wage bills in particular placed further pressure on business expenses” and are able to boost their own prices amid “robust demand condition”.

BTW, the Cleveland Fed’s Inflation Nowcast, updated June 23rd, sees June core CPI up 0.43% (+5.2% a.r.) and core PCE unchanged at +0.38% (+4.6% a.r.).

image

The next FOMC is July 26-27 but participants and others will enlighten us with their respective readings of the economy, wages and inflation for another 3 weeks.

Yes, used car prices will keep deflating as higher interest rates make them increasingly prohibitive and supply of new vehicles improves…

… but, given policymakers’ avowed focus on services inflation, the more important chart is one that plots services inflation with wages: since the start of the pandemic, wages are up 19.6% while services prices are up 14.8%. Historically, these 2 series are so much in sync, yet nobody seems to care as all eyes are on rentflation…

fredgraph - 2023-06-25T022215.750

… itself also generally linked to wages:

fredgraph - 2023-06-26T002725.130

Hardest hit during the pandemic, service providers are back in charge as spending switched back from goods to services. Services prices have outpaced wages in 14 of the past 17 months.

fredgraph - 2023-06-25T023151.292

One good news is that May was the first of the last 10 months when prices rose more slowly than wages (+0.40% vs +0.45%). But May also broke a 3 months trend of slowing wages, resuming their 5%+ pace of the past 12 months.

To quote again the U.S. flash PMI: “The rate of cost inflation across goods and services picked up to a robust pace. The reigniting of cost inflationary pressures was driven by the service sector amid increased wage bills.”

Unfinished business!

One reason for the June Fed pause was to see if a credit crunch is developing. Bloomberg’s Tracy Alloway talked about a “slow-moving credit crunch”:

Put it all together, though, and bank credit has been on the longest downward trajectory since the 2008 financial crisis. That’s a pretty remarkable development and one that’s gone largely unnoticed as a big portion of financial markets obsesses over things like AI and growth stocks.

Source: St Louis Fed FRED

Interestingly, the credit decline is coming from both small and large banks, which suggests that whatever’s happening is rather broad in scope.

Here’s the same chart since 1999 with bank credit and real GDP indexed at January 2020 = 100 and, on the right scale, nominal GDP/bank credit. Since 2014, bank credit jumped 80% while real GDP only grew 18%. There is way too much credit out there than needed by the real economy. The Fed’s QEs have actually fed the financial economy, what Bernanke wanted. But it needs to normalize.

fredgraph - 2023-06-25T032531.833

image

Meanwhile, the credit crunch, however slow, is not obvious, even among small banks (through last Friday):

fredgraph - 2023-06-25T030657.913

Light bulb Why Economies Haven’t Slowed More Since Central Banks Hit the Brakes Pandemic effects and government aid are blunting impact of higher rates, for now

Nick Timiraos lists many of unintended or unanticipated stuff the Fed is gradually understanding. I offer my two cents along the way:

(…) Much of the explanation lies in the pandemic’s weird effects and the time it takes for central-bank rate increases to curb economic activity. Additionally, historically tight labor markets have fueled wage gains and consumer spending.

First, the unusual nature of the pandemic-induced 2020 recession and the ensuing recovery blunted the normal impacts of rate hikes. In 2020 and 2021, the U.S. and other governments provided trillions of dollars in financial assistance to households that were also saving money as the pandemic interrupted normal spending patterns. Meanwhile, central banks’ rock-bottom interest rates allowed companies and consumers to lock in low borrowing costs. (…)

“There are just a lot of embedded pandemic-era forces that are working against this tightening,” Tom Barkin, president of the Federal Reserve Bank of Richmond, told reporters last week.

Barkin conveniently omitted the embedded QE-era forces “that are working against this tightening”.

Two industries traditionally sensitive to interest rates—autos and construction—offer examples.

Pandemic-related shortages of semiconductor chips limited the supply of cars for sale, leading eager buyers to pay higher prices for the vehicles available. Although U.S. construction of single-family homes tumbled last year, construction employment grew over the past 12 months. Fueling job growth were supply-chain bottlenecks that extended the time needed to finish homes and a record amount of U.S. apartment construction, which takes longer to complete.

U.S. single-family housing construction has rebounded recently thanks to historically low numbers of homes for sale. Many households refinanced during the pandemic and locked in low mortgage rates—a good reason to stay put. “I didn’t fully anticipate how much the move in interest rates would convince people not to put their houses on the market,” Barkin said.

Ten years of ZIRP have consequences. What normal biz people would not invest at near zero borrowing costs?

Superimpose the pandemic and the U.S.-China conflict and you get reshoring and nearshoring plus chip spending. U.S. construction spending is up 30% since the end of the pandemic. It rose 8% since the Fed started to tighten in the spring of 2022, even accelerating to +11.3% annualized in the past 6 months and to +16% in the past 3 months.

The historically most sensitive economic sector to Fed tightening is actually accelerating. And the Fed pauses to allow for the lag effects…

Normally, the Federal Reserve’s rate increases force heavily indebted consumers and businesses to rein in spending because they have to pay more to service their loans. But consumers haven’t overextended themselves with debt over the past two years; household debt service payments accounted for 9.6% of disposable personal income during the first quarter, below the lowest levels recorded between 1980 and the onset of the pandemic in March 2020.

“A lot of the imbalances you might anticipate at this point in the cycle just have not had the time to build up,” said Matthew Luzzetti, chief U.S. economist at Deutsche Bank.

Second, government spending has continued to bolster growth, cushioning economic shocks that proved less catastrophic than expected. While Europe’s energy crisis helped to tip the region into a shallow recession over the winter, the region skirted the deep downturn that some analysts had forecast. European governments pledged up to $850 billion to support spending. (…)

Money Nick forgot the other side effect of rising interest rates: personal interest income increased 9.1% in the last 12 months, benefitting baby boomers who are now eating out and travelling after years of financial repression and a pandemic, fueling demand for services and associated employment and wages. Not to mention the jump in asset values thanks to very expansive monetary policies since the GFC.

House prices (Case-Shiller) have turned back up since January as supply remains very low. Mortgage holders don’t want to sell and lose their low 30-y rates. That was also not in the tightening playbook…

Granted, nobody anticipated the very mild winter which kept energy costs low amid the Ukraine war.

Central banks in Norway and the U.K. announced half-point interest-rate increases last week to address persistent inflation. Central banks in Canada and Australia recently resumed rate increases after pausing, pointing to higher service-sector inflation and tight labor markets.

The Switzerland-based Bank for International Settlements, a consortium of central banks, warned in a report released Sunday that reducing inflation to many central banks’ 2% target could be harder than expected.

Easy gains from lower energy- and food-price inflation have been banked. The longer high inflation lasts, the more likely it is that people will adjust their behavior and reinforce it, the BIS said. In that scenario, central banks might find they need to cause a sharper downturn to force inflation down to their goal.

“The ‘last mile’ may pose the biggest challenge,” the BIS said.

FYI:

From Callum Thomas:

  • All Just AI Hype? If we look at the S&P500 excluding the AI Boom stocks, it looks much less gainy, on first glance on this window of time it does not look at all like a bull market, at the very best maybe a “crab market” that moves in a sideways range-trade.

Source:  @TheIdeaFarm @johnauthers

  • Equal-Weighted Evenly-Balanced: Indeed, looking at the equal-weighted version of the S&P500, it’s a wash, no new lows since October, but basically a sideways moving range trade since early-2022 (and well, basically going no where since mid-2021). And since the Oct/Nov rebound, market breadth for the S&P500 has likewise been drifting between average and mediocre (much like my high school grades).

Source:  MarketCharts

  • Relative Value?  Depending on your perspective, you might say big tech is stretched expensive, or you might say the rest of the S&P500 is cheap on a relative basis, and hence has catch-up potential.

Source:  @ISABELNET_SAs