Job Gains Slow as Layoffs Persist Hiring gains slowed sharply headed into the fall as more layoffs turned permanent, adding to signs that the U.S. economy faces a long slog to fully recover from the pandemic.
Employers added 661,000 jobs in September, the Labor Department said Friday. The increase in payrolls showed the labor market continued to dig out of the hole created by the pandemic, but at a much slower pace than over the summer.
The U.S. has replaced 11.4 million of the 22 million jobs lost in March and April, at the beginning of the pandemic. Job growth, though, is cooling, and last month marked the first time since April that net hiring was below one million. (…)
The unemployment rate fell to 7.9% in September from 8.4% the prior month. Though the jobless rate is down sharply from a pandemic high of near 15% in April, last month’s drop partially reflected an increase in permanent layoffs and more people leaving the labor force. That could stem from more workers quitting their job searches due to weak employment prospects or child-care responsibilities. (…)
The recent layoff announcements aren’t reflected in the September jobs report, which includes data gathered in the first half of the month. (…)
The WSJ editorial board, clearly rooting for Trump’s re-election, displays an upbeat view in More Jobs Momentum:
The private U.S. economy added 877,000 new jobs in September, but you’d think from the coverage that this was bad news. While the pace of hiring has slowed since the summer, the economy and labor market still have plenty of growth momentum. (…) In any normal period, this report would have been hailed as outstanding. (…)
Local governments shed 231,000 workers in public education. This is no surprise as schools that are closed need fewer workers. Local governments added 96,000 non-education jobs last month so they don’t seem starved for cash. (…)
“Growth momentum”?


Data: Bureau of Labor Statistics. Chart: Axios Visuals
Axios: “When the first waves of layoffs hit in March and April, most of the newly unemployed believed their job losses would be temporary, and reported they were not looking for work. Without a mass surge of hiring significantly above the levels seen in September, the “tsunami” of unemployment that economists warned Dion about in early August is poised to hit in the next couple months.”
Unlike corporations trying to preserve margins and profits during downturn, governments try to protect jobs, caring after the financials after the economic rebound. In 2008-09, local government employment rose during the first half of the crisis, stabilized during the second half and quickly declined during the following 4 years.
This time, lockdowns obliging, local government jobs cratered 1.3 million in April and May. Some 25% of these lost jobs came back in the past 3 months but it is a big stretch to claim that the worst is over. Almost Daily Grant is one of the bad news bearers:
As state and local governments are required to balance their budgets and lack Uncle Sam’s handy access to the Federal Reserve printing press, the prospect of further bloodletting across municipal payrolls appears likely. During a recent Economic Policy Institute teleconference, Moody’s Analytics chief economist Mark Zandi projected that the aggregate state and local governments budget shortfall could approach $500 billion by fiscal 2022, along with an additional 3 million lost jobs over the next 12 to 18 months.
Three million lost jobs? That would bring local government employment below 11 million, a level last seen in 1989. Even if the Defund Police movement succeeds in eliminating all 800,000 police officer jobs in the U.S., another 2M+ cuts will be needed, likely requiring wide cracks along a certain wall in order to maintain local government operations…
High frequency data from Homebase is not displaying “plenty of growth momentum” as suggested by the WSJ. New York state payrolls remain nearly 40% below their pre-pandemic levels. The state’s credit rating just got cut one notch by Moody’s with a negative outlook.
Homebase payrolls tracking suggest a plateau (% deviation in employment from January)

Permanent job losers keep rising across the USA and reached 3.8 million in September, up 345k (10.1%) from August and 2.5 million from February. Permanent job losers and the unemployment rate peaked 5 months after the end of the financial crisis but at much higher levels. After the 2001 recession, these numbers peaked almost 2 years later.

Online business directory Yelp said as of Sept. 15, 60% of the closed businesses it tracks, nearly 100,000, had no plan to reopen. Those closures, largely among small businesses, particularly hit restaurants and stores. (WSJ)
This next chart shows the YoY change in employed people in goods vs service producing sectors. Goods-Producing jobs are down 1.0 million YoY in September but Service-Producing jobs are down 8.6 million, both series swooshing, right when the second wave is hitting and the CARES act effects waning.

While manufacturing PMI surveys point to better days ahead, these diffusion indices mask the steep climb in actual numbers needed to reach pre-pandemic levels:

At the current level of backlog, manufacturers need no more than another 100-200k workers but employers are likely to increase weekly hours before, requiring only 65k new jobs assuming backlogs don’t decline any more.

The odds of a [stimulus] deal and a Democratic election sweep have increased, Evercore ISI said.
Services PMIs:
Services PMIs:
The U.S. Services PMI will be out later this morning.
Service sector weighs on eurozone economy in September
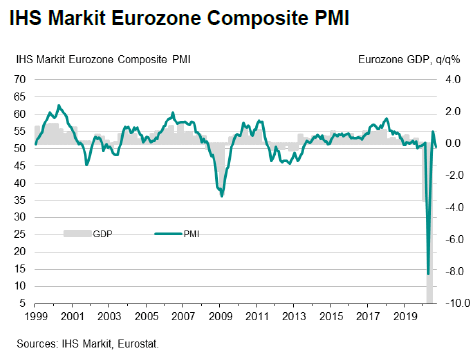
Growth of the eurozone’s private sector slowed further towards stagnation in September. The IHS Markit Eurozone PMI® Composite Output Index slipped to a three-month low of 50.4, down from August’s 51.9 and indicative of only a marginal expansion. The final reading was, however, firmer than the earlier flash estimate (50.1).
The composite PMI belied a two-speed economy during September. Led by a strongly performing Germany, overall regional manufacturing output rose at the fastest pace for over two-and-a-half years. In contrast, service sector activity slipped back into contraction by registering its worst performance since May.
There was some notable divergences in activity at the country level during September. On the one hand, Germany recorded a marked rate of growth, with its performance far outstripping the rest of the region. Italy was the only other nation to record expansion, although the gain here was marginal.
France and Ireland meanwhile slipped back into contraction, whilst a sharp deterioration in services activity weighed heavily on Spain’s private sector performance.
Incoming new business in the eurozone increased only slightly during September, and at the slowest rate in the current three-month period of growth. That was in spite of the first rise in overall export trade for the first time in over two years.
As new business growth softened, and with evidence of ongoing spare capacity across the private sector economy, companies were again able to comfortably deal with overall workloads. According to the latest data, backlogs of work declined for a nineteenth successive month albeit again only modestly.
Employment numbers were again reduced, marking a seventh successive monthly fall in staffing levels. That said, the rate of contraction was the weakest recorded in the current sequence with all nations registering slower falls when compared to August. France and Spain recorded the sharpest cuts to employment numbers, and Italy the weakest.
Operating expenses increased for a fourth successive month during September, with the rate of inflation solid. Input price inflation was sharpest in Spain. Meanwhile, the challenging business environment, characterised by still-weak demand and strong competitive pressures, weighed on company pricing power. Subsequently a seventh successive monthly decline in output charges was recorded in September, with the fall the greatest since June.
Business expectations did, however, improve to their highest level for seven months with confidence broadly in line with its long run average. Italian companies where the most confident, with sentiment here at its highest since the start of 2016.
The IHS Markit Eurozone PMI® Services Business Activity Index signalled a fall back into contraction of the services economy during September. After accounting for seasonal factors, the index posted 48.0, down from 50.5 in the previous month and the lowest level since May.
Germany was the only services economy to register growth (albeit marginal) as all four other nations monitored registered a contraction. Spain recorded by far the steepest monthly fall, followed by Ireland.
A second successive monthly reduction in overall new business was signalled by September’s survey, with Germany again the only nation to record any growth. Export business was also down markedly, extending the current period of contraction to over two years.
A modest reduction in employment was signalled by the September survey data as there remained little pressure on capacity (backlogs of work outstanding declined for a seventh successive month). Spain registered the sharpest monthly fall in job numbers with solid reductions also seen in France, Ireland and Italy, while Germany posted a slight rise.
Cost considerations were a factor behind the latest round of job losses, although firms nonetheless recorded a fourth successive monthly rise in overall operating expenses. Output charges declined again, however, with the rate of deflation the sharpest for three months.
Finally, looking ahead to the coming 12 months, business confidence strengthened in September with sentiment highest in Italy.

Japan: Business activity decreases at slowest rate in eight months
The Japanese service sector continued to contract at the end of the third quarter, with business activity, new orders and employment all decreasing in September. However, the rates of contraction eased, signalling a move towards stabilisation. The ongoing coronavirus disease 2019 (COVID-19) pandemic led to the closure of businesses whilst lockdown restrictions prevented tourism activity. Nevertheless, sentiment was at its highest since December, with panellists hoping for the passing of COVID-19 and full resumption in operations over the next year.
The seasonally adjusted Japan Services Business Activity Index posted 46.9 in September, up from 45.0 in August. The latest figure signalled a reduction in activity, although one that was the slowest in the current eight-month sequence of contraction.
Incoming new business received by service providers also fell for the eighth month running during September. Although solid, the pace of decline eased from that seen in August. Anecdotal evidence continued to highlight the impact of lockdown restrictions on client operations and market demand.
Export sales remained especially subdued, with latest data signalling a steep and accelerated contraction. International travel restrictions and client business closures were often mentioned by respondents.
The reduction of new business at Japanese service companies contributed to a fall in staffing numbers, although firms commonly mentioned employee retirements as the main driving factor. Employment has now contracted for seven successive months. Despite reduced workforce numbers, companies were able to deal with incoming new orders and continued the downward trend in outstanding business seen since last December.
Average input costs fell for the second consecutive month during August. However, the rate of decrease was only marginal. Survey respondents noted lower labour costs following reduced workforce numbers. Cost savings were passed onto clients, with some firms mentioning discounting strategies to stimulate sales in the sector.
Finally, business sentiment improved at Japanese service providers and returned to positive territory during September. Despite another downturn in new work and output, firms hope for a recovery in demand in both domestic and foreign markets and the complete easing of lockdown restrictions over the coming year. That said, some firms expected a decrease in business activity amid worries about the continuation of COVID19.
The au Jibun Bank Japan Composite* PMI Output Index rose to 46.6 in September from 45.2 in August, the highest reading since February. However, the index was below the crucial 50.0 neutral value for the eighth month running.
Private sector new business also continued to fall, although the pace of reduction eased to the slowest in the current period of decline. New orders placed at Japanese manufacturers decreased to a greater extent than in the service sector.
Falling workloads led private sector companies to reduce their staffing levels. Marginal job cuts were signalled among manufacturers and service providers.
Companies in both sectors were optimistic that business activity will rise in the coming 12 months. At the composite level, business expectations were the strongest since December 2018.

September Vehicles Sales increased to 16.3 Million SAAR
The BEA estimates sales of 16.34 million SAAR in September 2020 (Seasonally Adjusted Annual Rate), up 7.6% from the August sales rate, and down 4.3% from September 2019. (…) Sales-to-date are down 18.8% in 2020 compared to the same period in 2019.

-
Americans Are Driving Less Than Before Pandemic, and It’s Permanent Working from home and delivery mean less miles on the road, though the number of cars is holding steady.
The early days of the Covid pandemic brought an unprecedented decline in driving in the U.S., with vehicle miles traveled down 41% from February to April on a seasonally adjusted basis. By July, the most recent month for which the Federal Highway Administration has released data, vehicle miles were still down 13% (seasonally adjusted) from February. (…)
A study this summer by accounting and consulting firm KPMG forecast that vehicle miles traveled will settle at about 90% of pre-2020 levels in coming years. On a per capita basis, they were down 5% from their all-time high in the mid-2000s even before the pandemic. Driving in the U.S. would seem to have peaked. (…)
In September, 22.7% of employed Americans reported working from home because of the pandemic, according to the Bureau of Labor Statistics. Among those in management and professional occupations, the figure was 40.5%.
Americans working at home were saving 60 million commuter hours a day, according to a University of Chicago study.
Electronic commerce and mail orders accounted for 14.2% of U.S. retail sales in July, according to the Census Bureau, up from 11.7% in February and 3.3% in early 2000. (…)

That would be a huge change following the 10% jump since 2014. Here’s tyhe long term chart for vehicle sales courtesy of CalculatedRisk:

New York City to Close Schools in Some (9) Neighborhoods Due to Rising Covid-19 Cases

- The French government will shut bars and impose other restrictions in the Paris region from tomorrow as authorities struggle to contain a spike there. New curbs are also expected to be announced in Ireland and Italy. U.K. Prime Minister Boris Johnson warned of a “tough winter” as the country’s test-and-trace system came under fire again after it failed to capture 15,000 positive tests last week. Globally, infections have passed 35 million. (Bloomberg)
- Russia’s highest case count since May prompts tighter curbs in Moscow
Cineworld brings down curtain on U.S., UK theatres; 45,000 jobs hit Cineworld will close all of its UK and U.S. movie theatres this week, leaving as many as 45,000 workers unemployed for the foreseeable future as it strives to survive a coronavirus collapse in film-making and cinema-going.
The world’s second-biggest cinema chain said the reluctance of studios to push ahead with major releases such as the new James Bond film had left it no choice but to close all 536 Regal theatres in the U.S. and its 127 Cineworld and Picturehouse theatres in the UK from Oct. 8. (…)
Studios have released some of this year’s major planned blockbusters on Netflix or the Disney Plus streaming platform, while cancelling others until next year. (…)
The WSJ adds: “If the status quo continues, 69% of small and midsize movie theater companies will be forced to file for bankruptcy or to close permanently,” the National Association of Theatre Owners said.
States Overpaid Virus Unemployment Claims. They Want the Money Back. Workers in Colorado, Pennsylvania and elsewhere were overpaid accidentally. Now, people are being asked to repay thousands of dollars or are having their current pandemic benefits cut to make up the difference.
TWIN DEFICITS

(Variant Perception Research)
Lacy Hunt and others have long argued, and been proven correct so far, that rising debt actively suppresses economic growth. Debt service prevents everyone (government, businesses, and households) from investing enough capital to generate long-term growth. This is why each new dollar of debt is producing less additional GDP. We are borrowing to fund consumption instead of production. (John Mauldin)

TECHNICALS WATCH
Lowry’s Research: BP and SP side by side, going sideways. Needed: “upside reversal in the trend of BP”.

A 32-Year-Old Trader Is Driving 21,000 Amateur Stock Investors EToro has gained a devoted following in Europe and is now looking to the U.S.
Jay Smith isn’t a professional money manager. He’s just a 32-year-old living in southern England who spends his days playing the stock market.
But Smith, better known online as Jaynemesis, drives the investment decisions of more than 21,000 people with $40 million in assets who copy his trades on a digital platform called eToro. When he loads up on shares of FedEx, so do they, and when he shorts the Nasdaq index, they do that, too.
All of this is taking place on EToro, which calls its service copytrading. While the feature has played a key role in attracting more than 15 million users to the Israeli-British company — which is around the same level as online trading powerhouse Robinhood — the practice has yet to take root in the U.S. That might be about to change. (…)
The company’s biggest difference with rivals is this notion of copytrading. With the tap of a button, a customer can automatically duplicate the trades of dozens of other customers that eToro has designated Popular Investors. They perform like de facto money managers. (…)
EToro pays Popular Investors up to 2.5% of the assets that follow them. Smith, as the No. 1 copytrader on the site, is pocketing $1 million. With his portfolio up 62% in 2020, he’s been attracting droves of recruits. “Hi Jaynemesis, newbie copier here!” one recently posted on his social media feed on eToro’s site. “I have no real idea on stocks but it seems like you do.” (…)
In making it easier than ever to copy amateurs, sell short, and use borrowed money — eToro’s limit for stocks is 5 to 1 — the platforms are magnifying risk and fueling speculation, says Rainer Lenz, the former chairman of Finance Watch, a Brussels-based organization. (…)
“Traditional financial institutions don’t really offer a relevant experience for our generation,” said Yoni Assia, the 39-year-old co-founder and chief executive officer of eToro. “We expect everything to be in real time, to be mobile, and to be social. That’s what differentiates our platform.” (…)
“Give a man a fish, and you feed him for a day. Teach a man to fish, and you feed him for a lifetime.”


 Via MSNBC
