U.S. JOLTS: Job Openings Decline as Hiring Turns Tepid
The Bureau of Labor Statistics reported that the total job openings rate declined to 4.3% during November from an unrevised 4.6% in October. It remained below the 4.8% record high in January. The job openings rate is the job openings level as a percent of total employment plus the job openings level. The hiring rate held steady at 3.8% and has been moving sideways since early last year. Employers became less inclined to let workers go. The layoff & discharge rate fell m/m to 1.1% and matched the record low. Individuals remained ready to seek new positions. The quits rate held m/m at 2.3% but has been trending higher for ten years.
The private-sector job openings rate fell sharply m/m to 4.5% and remained below the high of 5.2% twelve months earlier. The government sector job openings rate declined to 3.1%, but remained above the 2009 low of 1.2%.
The level of job openings fell 7.6% (-10.8% y/y) to 6.800 million. It was the lowest level since February 2018. Private-sector job openings fell 12.7% y/y, but government sector job openings increased 8.1% y/y.
Hiring activity remained weak in November. The private-sector hiring rate held steady at 4.2% and remained below July’s expansion high of 4.4%. The hiring rate in government was unchanged at 1.6%, but below the January 2019 high of 1.8%.
Total hiring improved 0.7% but was unchanged y/y. Hiring in the private sector rose 0.4% (0.1% y/y). Government sector hiring rose 4.2%, but declined 1.1% y/y.
The U.S. private sector had 12.7% fewer job openings in November than one year ago, the worst drop since February 2008. The recession officially started in December 2007.
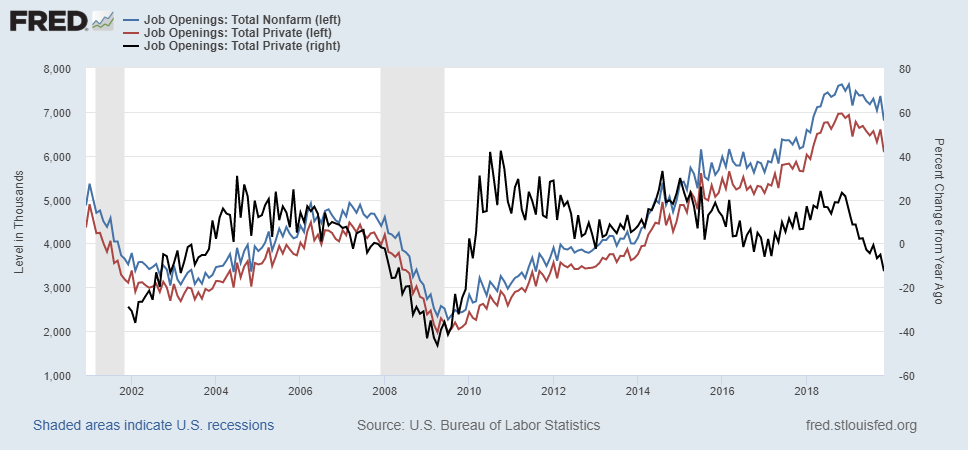
Job openings dropped 584,000 in the past 6 months, the most severe decline since 2008.
Total employment was rising 0.8% YoY in December 2008, 0.9% in March 2001 when the previous recession began. In December 2019, the growth rate was 1.4%, down from 1.9% in January 2019.
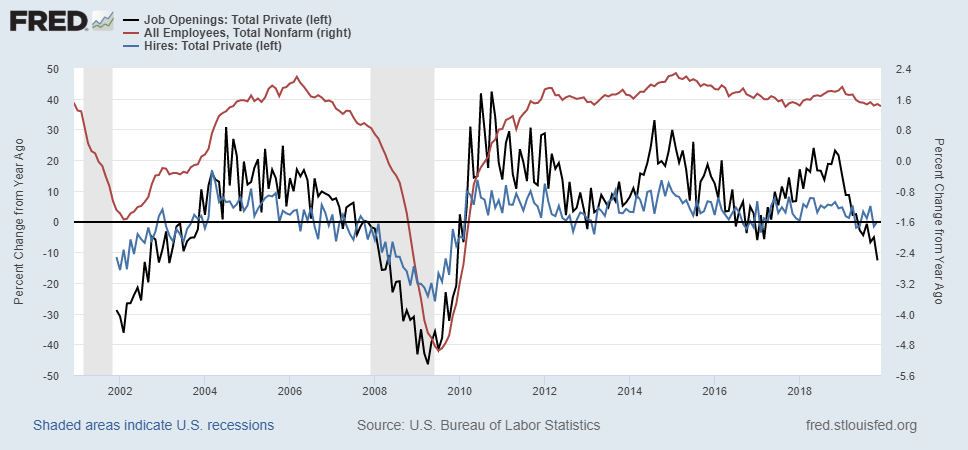
The fact is that labor slack (U6) in the U.S. is 6.7%, an all time low, so hiring people has become very challenging, to say the least. To higher new employees, you either have to convince the holdouts to enter the labor force, or steal them from another employer. Per the Atlanta Fed, job switchers’ wages were up 4.4% in Q4 against +3.3% for job stayers’.
But the other reality is that employers are actually seeking much fewer employees than one year ago. The December NFIB survey revealed that only 19% of small biz owners, the main job creators in the USA, planned to hire people during the next 3 months, down from 23% one year ago and from the cycle high of 26% in August 2019.
- Here are the year-over-year changes in job openings vs. the GDP. (The Daily Shot)

Source: @TaviCosta
U.S. Industrial Production Lower on Utilities
Industrial production decreased a weaker-than-expected 0.3% in December (-1.0% year-on-year) following offsetting revisions to October and November — now -0.5% and 0.8% revised from -0.9% and 1.1% respectively. On an annual average basis, industrial production was up 0.8% y/y in 2019, the weakest annual growth since 2016.
Manufacturing activity increased 0.2% (-1.3% y/y) during December, with a slight downward revision to November (now 1.0% versus 1.1%). This is the largest December-to-December decline since 2015; annual average output edged down 0.2%. Utilities production fell 5.6% (-1.9% y/y), as much warmer-than-normal weather in December decreased demand. U.S. population-weighted heating was 101 degree-days below normal; over the last ten years, the mean for this statistic was -26 degree-days per month. Meanwhile mining activity rose 1.3% (1.4% y/y).
Manufacturing of durable goods declined 0.2% (-1.3% y/y) in December, with motor vehicles dropping 4.6% (-8.3% y/y). Machinery output edged up 0.1% (-3.8% y/y), while computer and electronics gained 1.4% (7.0% y/y). Aerospace production rose 0.8% (0.7% y/y). (…)
Output of business equipment, an indicator of capital spending, edged down 0.1% in December (-1.9% y/y). In the special aggregate groupings, production of high technology products, which is now less than 2% of total output, increased 1.1% (8.0% y/y). Factory sector production excluding the motor vehicle and high tech sectors rose 0.6% (-1.1% y/y), but is still 11% below its 2007 peak.
Capacity utilization declined to 77.0% in December from a slightly upwardly-revised 77.4% (was 77.3%). Factory sector use edged up to 75.2% but is still down 2.1 percentage points from December 2018’s cyclical peak. Utility utilization fell to 73.5%, the second weakest on record (data began in 1967); February 2017, which was even warmer than normal, holds the record low of 71.5%. Capacity in the manufacturing sector grew 1.4% y/y, the first month it has surpassed its 2008 peak.


Markit was quick to jump on the manufacturing data to prove the superiority of its PMI survey vs the ISM’s:
Official data showed manufacturing output growing 0.2% in December following a 1.0% rise in November (revised down slightly from 1.1%). The improvement defied expectations among economists of a 0.2% decline, according to Reuters estimates, but confirmed the signal from IHS Markit’s PMI survey data.
(…) the official data also confirm that the contraction of the manufacturing sector has been only relatively modest, and that renewed signs of life were apparent at the end of the year. This narrative matches precisely that depicted by IHS Markit’s PMI survey.
The manufacturing output index from the IHS Markit PMI survey had risen to a ten-month high of 53.7 in November before slipping back slightly to 52.4 in December, representing a relatively strong end to a year in which the index averaged just 52.2. That was down from a far stronger average of 55.2 in 2018 and 54.2 in 2017. (…)
The fourth quarter PMI output index average of 52.8 therefore equates to a quarterly output growth rate of -0.2%, which is very close to the official estimate of -0.3%.
The mild quarterly decline recorded by both the IHS Markit PMI and official data contrasts with a far steeper contraction signalled by the ISM survey data. The ISM’s manufacturing output index fell to a decade low of 43.2 in December, averaging just 46.2 in the fourth quarter. (…)
A similar divergence from official data has also been evident for the ISM survey against factory orders and employment numbers, a divergence which has not been seen in the IHS Markit data. (…)
A consequence of it [the ISM] being biased towards larger, multinational firms is that the ISM data could be more heavily influenced by global conditions facing US-owned companies than the IHS Markit data. Note that global manufacturing growth outside of the US, as tracked by official production data, has matched the recent pattern of growth shown by the ISM, slowing sharply towards the end of 2019.


U.S. Housing Starts Surge to 13-Year High
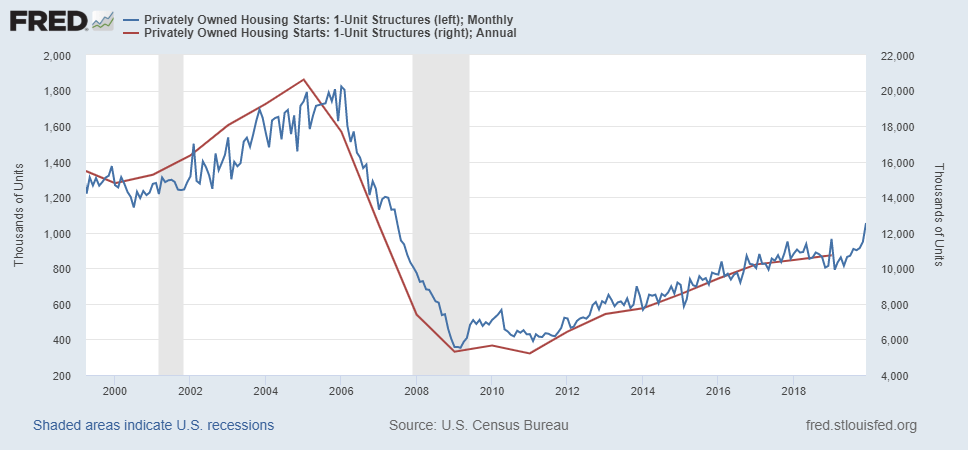
Fueled by low interest rates and a strong job market, new home building strengthened during December. Housing starts jumped 16.9% (40.8% y/y) to 1.608 million (AR) from November’s 1.375 million, revised from 1.365 million. It was the highest level of starts since December 2006.
The rise in starts last month was powered by a 29.8% surge (68.6% y/y) in multi-family starts to 553,000, the highest level since December 1986. Single-family starts also were strong and posted an 11.2% increase (29.6% y/y) to 1.055 million, the highest level since June 2007.
Building permits declined 3.9% (+5.8% y/y) 1.416 million. Permits to build single-family homes eased 0.5% (+10.8% y/y) to 916,000 while multi-family permits declined 9.6% (-2.3% y/y) to 500,000.
By region, housing starts rose by roughly one-third (85.4% y/y) to 254,000 in the Midwest. Starts also were strong in the Northeast where they posted a one-quarter increase (18.8% y/y) to 133,000. In the West, housing starts rose 19.8% (72.7% y/y) to 411,000 and in the South, housing starts rose 9.3% (23.7% y/y) to 810,000.
 Warm weather in winter helps construction disproportionately. The temperature in December was nearly 9% warmer than average with 22% less precipitations. December’s single family starts were up 29.6% YoY and Q4 starts were up 17.5% against –7.6% in Q4’18. For the full year 2019, single family starts were up 2.4%, the same as in 2018.
Next on President’s Trade Agenda? Europe
(…) The U.S. Trade Representative has prepared two sets of tariffs aimed at Europe: one in retaliation for a French digital-services tax, another because it says Europe hasn’t done enough to end subsidies of the aircraft manufacturer Airbus SE. In addition, the administration has never abandoned the idea, first floated nearly two years ago, of imposing tariffs on the European automobile industry. (…)
President Trump and Mr. Lighthizer are planning to meet the new European Commission president, Ursula Von Der Leyen, and Mr. Hogan on the sidelines of the World Economic Forum in Davos, Switzerland next week. (…)
As part of his bid to reset relations, Mr. Hogan [the EU’s newly appointed trade commissioner], an Irish farmer, politician, and formerly Europe’s agricultural commissioner, has emphasized Europe’s willingness to negotiate agricultural issues, but not agricultural tariffs. He has touted an agreement in 2019 that allows more U.S. beef exports to Europe, as well as a regulatory change allowing U.S. soybeans to be used in European biofuels, helping boost exports of one of Mr. Trump’s favored crops.
But the EU remains at odds with the Trump administration on many issues. (…)
“We ought to have fair rules and disciplines under the World Trade Organization structure that allows everybody to have a competitive opportunity around the world,” said Mr. Hogan. “We don’t agree with the approach that leads to managed trade.” (…)
Mnuchin Warns U.K., Italy Over Digital-Tax Plans Treasury secretary says the European countries will face tariffs if they implement their planned taxes
(…) Mr. Mnuchin issued the warning after France agreed to delay the imposition of its own digital tax in the face of threats of steep U.S. tariffs on French exports. Mr. Mnuchin said French President Emmanuel Macron agreed to hold off on the tax through the end of the year while the two countries work out a permanent resolution. (…)
The U.S. has signaled it objects to the plan but supports a mechanism to resolve global tax disputes that would give multinational companies a safe harbor.
With a “phase one” trade deal with China in place, Mr. Mnuchin said phase two wouldn’t necessarily be a “big bang” that removes all existing tariffs. “We may do 2A and some of the tariffs come off. We can do this sequentially along the way.”
Mr. Mnuchin also said the Trump administration would propose a new middle-class tax cut later this year. “We are working on what we call tax cut 2.0…which will be additional middle-class tax cuts. We are in the process of designing it and will be rolling it out shortly.” (…)
Foreign Investment Falls to Near-Decade Low as Globalization Slows New overseas investment by businesses around the world fell for the fourth-straight year in 2019 to its lowest level in almost a decade, pointing to a slowdown in globalization as the world-wide economy cooled.
The United Nations Conference on Trade and Development said foreign direct investment, or FDI, last year fell to $1.39 trillion from $1.41 trillion. The 1% drop puts global FDI at its lowest level since 2010, when many businesses shelved plans as they assessed the impact of the financial crisis. The U.N. expects to see little change in the flows this year. (…)
Unctad said some foreign investments in 2019 reflected businesses adjusting to new tariffs by moving existing production to other locations, rather than expanding their overall capacity, suggesting the slowdown is more severe than the headline figures show. (…)
It said that new projects announced by businesses during 2019 were down more than a fifth on the previous year. (…)
U.S. Slips in Global Innovation Index. Again
Germany took first place in the 2020 Bloomberg Innovation Index, breaking South Korea’s six-year winning streak, while the U.S. fell one notch to No. 9. (…)
The annual Bloomberg Innovation Index, in its eighth year, analyzes dozens of criteria using seven metrics, including research and development spending, manufacturing capability and concentration of high-tech public companies. (…)
The U.S., which was No. 1 when the Bloomberg index debuted in 2013, fell one spot to No. 9 since last year’s ranking. Japan dropped to No. 12, down three spots for the same-sized decline in last year’s index.
The world’s second-biggest economy, China, edged higher by one spot to No. 15. It held onto a second-place ranking on patent activity, and broke into the top five for tertiary efficiency.
China’s strong performance probably shows that it was “busy building up and readying for a prolonged trade war and thus urgently needed to do a lot of in-sourcing, and getting up the value chain of manufacturing,” said Francis Tan, investment strategist at UOB Private Bank CIO Office in Singapore. China has President Donald Trump “to thank for accelerating their plans.” (…)
The U.S. can at least celebrate holding onto world-beating performances in two categories: high-tech density and patent activity. (…)
U.S. Turns Up the Spotlight on Chinese Universities Justice, State Departments see academic partnerships as facilitating the transfer of sensitive technology
(…) Chinese intelligence services, after spending years gathering broad swaths of expertise from overseas, are now more targeted in their ambitions, U.S. officials said. They are seeking specific pieces of technology that fill gaps in research being conducted at Chinese universities and designated as priorities by Beijing. (..)
The focus on Chinese universities is partially because of China’s efforts, under the leadership of President Xi Jinping, to pursue a policy of “military-civil fusion,” which binds Chinese civilian entities with the People’s Liberation Army in a common goal of bolstering China’s defense.
The U.S. military also has ties to American educational institutions, but unlike their Chinese counterparts, U.S. academia isn’t compelled to cooperate. Secretary of State Mike Pompeo noted this difference in a policy speech last week in Silicon Valley: “Under Chinese law, Chinese companies and researchers must—I repeat, must—under penalty of law, share technology with the Chinese military.” (…)
The party has also been tightening ideological control over campuses. In December, the charters of three Chinese universities—including Shanghai’s prestigious Fudan University—were amended to place absolute adherence to Communist Party rule over academic independence, prompting a backlash from Chinese scholars. (…)
The IMF tries to rain on the global stock parade
The IMF released its latest World Economic Outlook Monday, showing yet another revision lower of its expectations for global growth in 2019 and in 2020. IMF head Kristalina Georgieva also issued a number of warnings, suggesting that the worst may not have passed yet.
- “If I were to mark the words that come to my mind at the start of this decade it would be increased uncertainty,” she said on Friday during a speech at the Peterson Institute for International Economics. “And we know that uncertainty is not a friend to investment, growth and jobs.” (Axios)
 White House Considers Changes to Law Banning Overseas Bribes
President Donald Trump’s administration is weighing whether to seek changes to a 1977 law that makes it illegal for U.S. companies to bribe foreign officials. (…)
A forthcoming book called “A Very Stable Genius: Donald J. Trump’s Testing of America,” by Washington Post reporters Philip Rucker and Carol D. Leonnig, reports that Trump has complained about existing rules, and that he clashed with former Secretary of State Rex Tillerson in 2017 when Trump pushed to scrap the FCPA.
“It’s just so unfair that American companies aren’t allowed to pay bribes to get business overseas,” Trump said, according to an passage published by the Post. “We’re going to change that.”
The law is designed to prevent individuals and businesses in the U.S. from paying money or offering gifts to foreign officials as a way to win business overseas. Critics of the law complain that it puts U.S. businesses at a disadvantage in places where bribes are customary.
The Dog That Didn’t Bark: What Soybean Prices Say About Trade Deal
The price of a bushel of soybeans is lower than it was when Donald Trump was elected president in November 2016. It is little changed from when Mr. Trump ramped up his trade confrontation with China and has lost ground in the days since the deal was announced. Prices for wheat, pork and dairy products have been similarly stable. (…)
The dynamics of global commodities markets explain some of the investor skepticism.
Brazil and the U.S. are both major exporters of soybeans. Of the 85 million tons of soybeans that China imported in 2019, 57 million tons were supplied by Brazil, estimates Ken Morrison, a former commodities trader for Cargill Inc., the agriculture giant, who now writes a newsletter on the industry.
If China shifts its purchases from Brazil to the U.S. to comply with the new deal, global demand wouldn’t change. Such a shift might push up the price of U.S. soybeans relative to Brazilian soybeans. But Brazil’s soybeans would then be cheaper in other markets, giving it a new advantage outside of China. The result: the gap between U.S. and Brazilian soybeans would likely close, leaving the price of U.S. soybeans little changed.
If the price doesn’t change, are American farmers better off? The answer is yes if they are able to sell more. Right now, at least, that’s not in the outlook. The U.S. Department of Agriculture estimates that American farmers will plant 84 million acres in the 2020-2021 planting year. While that is more than the 76 million acres in 2019-2020, it is less than as much as the 87 million planted the year before.
What if China bought more soybeans on global markets overall, rather than simply shifting purchases from one country to another? China could order its state-owned storage companies to buy more. But without an increase in national demand, the extra soybeans would end up in storage facilities, putting downward pressure on prices down the road. China could buy more next year to meet its goal, then buy less in 2022.
Another challenge: Beyond two state-owned enterprises, Mr. Morrison noted, most of China’s soybean market is driven by private firms.
“This thing can’t work in a competitive marketplace,” Mr. Morrison said of the trade deal. (…)
“The parties acknowledge that purchases will be made at market prices based on commercial considerations and that market conditions, particularly in the case of agricultural goods, may dictate the timing of purchases within any given year,” the agreement says.
The U.S. and China have ended up in an odd position. China, a one-party state with communist roots, insists that market forces determine the outcome of its purchase commitments. Meanwhile the U.S., a voice for capitalism, depends on massive state intervention to meet purchase commitments. (…)
Value of New York Real Estate Shows Signs of Weakening Market values of existing homes, apartment buildings and commercial space rose at the slowest pace in six years, under a new assessment roll
(…) The weakening valuations follow a multiyear slump in the real-estate market, with slowing rent growth, falling commercial sales and sluggish homes sales, experts say.
Market values of apartments and commercial buildings could slow further next year, since the latest assessments are based on a full year of income and expenses back in 2018, and analysts say conditions have remained weak since then. (…)
Robert Knakal, chairman of New York investment sales at JLL Capital Markets(…) said the market was down 10% in value, but in terms of sales volume, “This is the longest correction we have ever seen in the 36 years I have been” in the business. (…)
EARNINGS WATCH
From Refinitiv/IBES:
Through Jan. 17, 44 companies in the S&P 500 Index have reported earnings for Q4 2019. Of these companies, 70.5% reported earnings above analyst expectations and 22.7% reported earnings below analyst expectations. In a typical quarter (since 1994), 65% of companies beat estimates and 20% miss estimates. Over the past four quarters, 74% of companies beat the estimates and 19% missed estimates.
In aggregate, companies are reporting earnings that are 4.7% above estimates, which compares to a long-term (since 1994) average surprise factor of 3.3% and the average surprise factor over the prior four quarters of 4.9%.
Of these companies, 65.9% reported revenue above analyst expectations and 34.1% reported revenue below analyst expectations. In a typical quarter (since 2002), 60% of companies beat estimates and 40% miss estimates. Over the past four quarters, 58% of companies beat the estimates and 42% missed estimates.
In aggregate, companies are reporting revenue that are 1.3% above estimates, which compares to a long-term (since 2002) average surprise factor of 1.5% and the average surprise factor over the prior four quarters of 1.0%.
The estimated earnings growth rate for the S&P 500 for 19Q4 is -0.8% (-0.6% one week ago). If the energy sector is excluded, the growth rate improves to 1.9% (1.9%).
The estimated revenue growth rate for the S&P 500 for 19Q4 is 4.4%. If the energy sector is excluded, the growth rate improves to 5.6%.
The estimated earnings growth rate for the S&P 500 for 20Q1 is 5.8% (6.1%). If the energy sector is excluded, the growth rate declines to 5.1% (5.3%).
These first 44 companies reported aggregate earnings up 0.3%, an improvement from the -0.4% registered by the first 43 companies that had reported during Q3’19. These companies displayed a beat rate of 86% and a surprise factor of +4.5%.
Analysts remain split on revisions for S&P 500 companies but tend to revise smaller companies slightly more negatively.

Looking at 2020 as a whole, earnings are seen up 9.7%, unchanged from Jan. 1.
Trailing EPS are now $163.15. The Rule of 20 P/E is 22.7. It reached 23.53 in January 2018 before the market correction which brought it down to 20.2 in April 2018. Note that the Rule of 20 Fair Value was still rising then, along with earnings rising 13-14% YoY.

If you don’t care about the Rule of 20 P/E and focus on the regular P/E, you are still very much in “buy high” territory…

…even if you are a forward looking calculator:

SENTIMENT WATCH
As stocks hit more and more records, there are signs traders may be getting way too euphoric
(…) The Ned Davis Daily Trading Sentiment Composite — which measures how optimistic or pessimistic traders are — currently sits at 80, squarely in “excessive optimism” territory. The measure also hit its highest level since June 2018 recently. Historically, the S&P 500 has lost an average of 5% annually since 2006 when the composite is above 62.5, or showing excessive optimism. (…)


Global Stocks Drop Amid Outbreak of Deadly Virus in China Global stocks dropped, led by Asian markets, amid concerns about the rapid spread of a potentially deadly pneumonialike virus originating in central China.
When equities are overvalued after a smart rise, Mr. Market is looking for any reason to lighten up.
Americans Show Scant Interest in Electric Vehicles, Subaru CEO Says The CEO of Subaru expressed frustration over trying to navigate between environmental regulations that seek to expand use of electric vehicles and the lack of real consumer demand for them.
“The only EVs that are selling well are from Tesla,” said Subaru’s Tomomi Nakamura at a briefing for journalists. (…)
Subaru’s chief technology officer, Tetsuo Onuki, said projections of EVs taking over the market in the next decade weren’t realistic.
Rather than trying to “navigate between environmental regulations”, Subaru’s CEO should simply glance at this table to understand his, and most others in the industry’s problem: range! (courtesy of InsideEV)


