U.S. Durable Goods Orders Decline as Aircraft Orders Fall
Activity in the factory sector weakened last month. New orders for durable goods declined 1.2% during October (+1.0% y/y) following an unrevised 2.2% September increase. A 0.5% increase in orders had been expected in the Action Economics Forecast Survey.
The decline in orders reflected a 4.3% fall (-10.1% y/y) in transportation sector bookings which reversed a 4.4% increase. Nondefense aircraft & parts orders weakened 18.6% (-48.9% y/y), but motor vehicle & parts orders gained 1.7% (4.8% y/y). Excluding the transportation sector durable goods orders improved 0.4% (7.4% y/y), up at a 9.8% annual rate during the last three months.
Nondefense capital goods orders weakened 4.5% (-7.5% y/y) due to the decline in civilian aircraft orders.
Orders excluding aircraft slipped 0.5% (+8.1% y/y) following three consecutive months of strong increase.

This is perhaps the most important info today, found in none of the mainstream media this a.m.:
Eurozone growth kicks higher in November, hiring at 17-year peak

The eurozone economy is showing signs of picking up momentum in the fourth quarter, with multi-year highs seen for all main indicators of output, demand, employment and inflation in November. Business activity and prices rose at the steepest rates for over six years, while the largest accumulation of uncompleted work for over a decade encouraged firms to take on staff at a rate not seen for 17 years.
The headline IHS Markit Eurozone PMI rose to 57.5 in November, according to the ‘flash’ estimate (based on approximately 85% of final replies), up from 56.0 in October and its highest since April 2011. The latest reading puts the economy on course for its best quarter since the start of 2011.

The upturn was again led by manufacturing, where the headline PMI rose to a level beaten only once –April 2000 – since the survey began in June 1997. Faster manufacturing output growth was accompanied by improved services growth, which rose to the highest since May, registering one of the largest expansions seen over the past six-and-a-half years.
Inflows of new orders showed the largest gain since February 2011. The biggest increase in factory new orders since April 2000 helped offset a slight moderation in the service sector. Goods exports increased at a survey record pace.
Despite the slowing in growth of service sector new work, both sectors saw backlogs of work accumulate at higher rates, with a record increase in manufacturing joined by the largest rise in the service sector since May 2011. The resultant overall build-up in backlogs of work was the largest since July 2006.
The shortfall of capacity relative to order book inflows signalled by the increase in outstanding work prompted growing numbers of firms to take on more staff. Employment showed the strongest rise since October 2000, with a record gain in factory jobs accompanied by the steepest rise in service sector payrolls for a decade.
Further signs of capacity being stretched were seen in a lengthening of manufacturing suppliers’ delivery times, which signalled the highest incidence of delays for over 17 years. Longer deliveries reflected higher demand for inputs from manufacturers, where inventories over the past two months have risen to a degree rarely seen in the survey’s history.
The faster pace of growth signalled by the surveys was accompanied by price pressures hitting the highest since mid-2011. Average input costs were pushed higher by the combination of rising global prices for key commodities, such as oil, as well as greater pricing power amid improved demand conditions.Input prices showed the largest monthly jump since May 2011 while average selling prices for goods and services rose to the greatest extent since June 2011.
Expectations about the next 12 months cooled slightly in both sectors in November, indicating one of the lowest degrees of optimism seen over the past year, but nonetheless remained elevated by historical standards.
Looking at the data by country, growth surged in France to the highest since May 2011, outpacing Germany for only the fourth time in over five years, despite the latter seeing growth also accelerate to a rate just shy of a six-and-a-half year high. While Germany’s expansion was again led by manufacturing, where the headline PMI rose to the second-highest on record, France’s upturn was led by services, albeit with manufacturing also gaining momentum.
Chris Williamson, Chief Business Economist at IHS Markit:
“The message from the latest Eurozone PMI is clear: business is booming. Growth kicked higher in November to put the region on course for its best quarter since the start of 2011. The PMI is so far running at a level signalling a 0.8% increase in GDP in the final quarter of 2017, which would round-off the best year for a decade.
A manufacturing-led rise in the composite PMI for Germany puts the euro area’s largest member state on course for GDP growth of possibly as much as 0.9% in the fourth quarter, up from an already-spritely 0.8% pace in the third quarter.
In France, a marked improvement in the PMI, fuelled by an increasingly buoyant service sector and improved manufacturing growth, is consistent with GDP rising at a strong 0.7% rate in the fourth quarter.
“Jobs are being created at the fastest rate since the dot-com boom, yet despite this increase in operating capacity firms are struggling to meet demand. Backlogs of uncompleted work are growing at the fastest rate for over a decade, often resulting in a sellers’ market as customers struggle to source goods and services. Prices are
consequently rising at an increased rate.“Manufacturing is leading the upturn, with business conditions improving at a rate only beaten once in the survey’s two-decade history amid record export and jobs growth. The service sector is reporting relatively slower but still strong growth, as witnessed by hiring reaching a ten-year high.
“There are signs that political uncertainty appears to have subdued business optimism a little, but the broad-based nature of the upturn, and the rate at which rising demand is feeding through to the labour market, suggests the eurozone will see a strong end to 2017 and enter 2018 on a firm footing.”


This is the key chart for Draghi et al., including all of us:
Russia-OPEC Agree on Framework to Extend Oil Cuts
Firms Cut Down on Buybacks as Stocks Become Expensive Companies in the S&P 500 are on pace to spend the least on buybacks since 2012
Companies in the S&P 500 are on pace to spend $500 billion this year on share buybacks, or about $125 billion a quarter, according to data from INTL FCStone. That is the least since 2012 and down from a quarterly average of $142 billion between 2014 and 2016. (…)
Buyback activity among top-rated nonfinancial debt issuers, many of which have regularly borrowed money to finance share repurchases, declined for the third straight quarter in the July-to-September period, according to Bank of America Merrill Lynch. Meanwhile, mergers and acquisitions among that group of companies had their biggest quarter of the year, analysts at the bank said. (…)
Dividend payments by S&P 500 companies are poised to set a sixth consecutive record in 2017, according to S&P Dow Jones Indices.
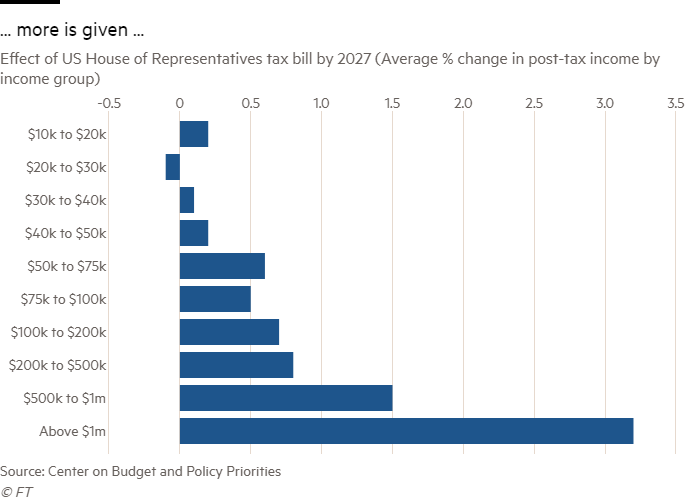
The GOP Tax Plan Is Entering Its Make-or-Break Week
Also a possible “break”:
The signs are that Michael Flynn, Donald Trump’s former security adviser, is to co-operate with an investigation into Russia’s alleged meddling in the presidential election. Mr Flynn’s lawyers have reportedly told the president’s legal team that they will no longer share information on the case, suggesting they are looking to do a deal with Robert Mueller, the special counsel looking into the matter. (The Economist)


 Is This The Real Reason Why The Treasury Curve Has Been Collapsing For A Month?