SERVICES PMIs
USA: Here we go again with very different PMI reports!
The seasonally adjusted final S&P Global US Services PMI Business Activity Index registered 54.9 in May, up from 53.6 in April and broadly in line with the earlier released ‘flash’ estimate of 55.1. The latest upturn in business activity was the fourth successive monthly increase, with the pace of expansion accelerating to the steepest since April 2022. Greater output reportedly stemmed from stronger demand conditions driving a sharper rise in new orders.
Growth in new business quickened again, with the rate of increase the steepest in just over a year. Companies noted that greater client confidence supported the expansion in new orders, as customers – especially in consumer markets – were more inclined to spend. Some also highlighted a broader client base and the acquisition of new customers.
Contributing to the rise in new orders was a renewed upturn in new business from abroad in May. New export orders increased for the first time in a year, and at a solid pace. Demand conditions at new and existing customers reportedly strengthened to support the latest expansion.
At the same time, service providers registered another marked increase in input costs. Greater business expenses were partly linked to increased supplier prices, but were largely attributed to higher wage bills and upward pressure on salaries. Although easing from that seen in April to the second-slowest since October 2020, the rate of input cost inflation remained historically elevated.
Service sector firms also saw a moderation in the rate of output charge inflation during May. Companies commonly stated that greater selling prices were due to the pass-through of higher costs to customers. The rate of charge inflation eased from April but was the second-fastest since September 2022 and sharper than the long-run series average.
In line with a stronger expansion in new business, service sector firms increased their workforce numbers at a solid pace. Matching the payroll gain seen in April, the rate of job creation was the joint-fastest since August 2022. Some companies noted that long-held vacancies were also filled following an increased availability of candidates, whilst others mentioned hiring was stepped up amid anticipated growth in demand.
Greater employment allowed firms to reduce the level of unfinished business during May.Backlogs of work contracted for the first time in four months.
Output expectations for the year ahead among service providers improved in May, as the degree of confidence rose to the highest in a year. Although weaker than the series trend, optimism was attributed to investment in marketing and advertising, alongside hopes for further boosts to new business.


- The ISM:
In May, the Services PMI® registered 50.3 percent, 1.6 percentage points lower than April’s reading of 51.9 percent. (…) The Business Activity Index registered 51.5 percent, a 0.5-percentage point decrease compared to the reading of 52 percent in April. The New Orders Index expanded in May for the fifth consecutive month after contracting in December for the first time since May 2020; the figure of 52.9 percent is 3.2 percentage points lower than the April reading of 56.1 percent. (…)
Eleven industries [out of 18] reported growth in May.
WHAT RESPONDENTS ARE SAYING
- “Restaurant sales continue to track positive year over year, up an average of 8 percent past month. Employment needs have leveled off, and we are in a position to evaluate and upgrade rather than just maintain. (…)” [Accommodation & Food Services]
- “Overall slowing growth and market conditions dragging on some construction sectors.” [Construction]
- “(…) Our [higher-education] enrollment is currently projected to drop 2.5 percent, which will have a negative effect on our budget.” [Educational Services]
- “Pent-up demand for services is driving strong revenue performance, but expenses (labor and supplies) continue to put pressure on margins, hindering the financial forecast. There is modest improvement in financial metrics, but it is becoming clear we will have to find ways to do more with less. (…) The overall outlook, however, suggests the forecast is good for the next quarter. Pent-up demand for services is also causing capacity constraints, but we appear to be managing appropriately at this time.” [Health Care & Social Assistance]
- “Electronic components supply is strong, and lead times are nearly back to pre-pandemic.” [Information]
- “Everything seems to have leveled off: not getting any worse, not getting any better.” [Professional, Scientific & Technical Services]
- “Lead times are starting to shorten, due in part to greater transportation availability. Prices, in general, are continuing to increase but at a slower pace. (…) [Public Administration]
- “Overall business is good, and there has not been a significant change in direction.” [Retail Trade]
- “Business has significantly increased, with more orders, newer customers and more activity in general. More end users are getting back to business as usual, fighting for lower prices and taking a few more days to pay. The leverage point seems to have shifted back to end users, which is healthy.” [Transportation & Warehousing]
- “Business conditions continue to remain elevated as CapEx (capital expenditures) spending in clean energy follows regulatory demands.” [Utilities]
- “Supply is plentiful, freight is moving quickly and costs are coming down. This is a 180-degree change from a year ago. Also, sales demand is down.” [Wholesale Trade]

ING highlights how weak the ISM is:
(…) the only time the service sector report has been weaker in the past 14 years was in April and May 2020 at the peak of Covid containment and the December 2022 blip caused by the huge winter storm that was so disruptive for the travel, entertainment and service sectors.
ISM reports are heading in the wrong directions
The details are poor throughout with business activity having similar metrics to the headline. New orders fell 3.2 points to 52.9, but the backlog of orders plummeted to 40.9 from 49.7. The backlog of orders are not seasonally-adjusted so comparisons are tricky, but for what it is worth, this is the worst reading since 2009. This is something that we also saw in the manufacturing report, dropping from 43.1 to 37.5.
Now at least in the manufacturing report we saw the employment component rise to 51.4 from 50.5, yet the payrolls report said manufacturing employment fell 2000. We saw private sector employment rise 257,000 in that same report, yet the ISM has service sector employment in contraction territory at 49.2! (…)
It looks likely that the manufacturing sector is already in recession (seven consecutive sub-50 readings for ISM manufacturing). The service sectors order books are weak and will need to turn around rapidly to prevent the service sector joining it. Given this situation it is difficult to imagine that employment will continue to make such large gains.

The rival reports are at such extremes that one of these 2 firms will lose face. Which one does the FOMC listen to?
Interestingly (or sadly), neither ING nor Goldman Sachs cared to mention that S&P Global’s report is very buoyant in all aspects. In fact, all media I surveyed this morning only featured the ISM report.
-
WSJ: Bond Yields Slip After Weak Services Data Though the non-manufacturing sector narrowly expanded, it whiffed on stronger expectations and is nearing contraction, according to ISM’s survey of business leaders.
-
Bloomberg: US Services Activity Nearly Stalls as Price Gauge Slides The US service sector nearly stagnated in May as business activity and orders downshifted, while a measure of prices paid slid to a three-year low.
- Reuters: The U.S. services sector barely grew in May as new orders slowed, pushing a measure of prices paid by businesses for inputs to a three-year low, which could aid the Federal Reserve’s fight against inflation.
From all I read, and based on past occurrences, I would side with S&P Global’s survey.
Supporting evidence (via The Transcript):
- “…from what we see, things still are probably far stronger than we would have thought they would have been at this point in the cycle. There’s still a fair amount of cash in deposit accounts. Consumer spend is holding up. Debit card spend is kind of flattish. Credit card spend for us is up roughly 10%. It’s slowing slowly, which is what we would expect. But again, still, you’re not seeing any meaningful declines or any acceleration of that.” – Wells Fargo (WFC ) CEO Charles Scharf
- “As we kind of shared with you as part of our Q1, we continue to see a consumer which is just remarkably resilient and consumer spending continues to be remarkably resilient…And as I look at our drivers as in the performance drivers, which drive our top line, what we’re seeing effectively is that through the first 2 weeks of the month of May, our drivers are generally in line with our expectations” – Mastercard (MA ) CFO Sachin Mehra
- “…in March, she simply pulled back, and back half of March, we saw her pull back and really pull out of spending. The good news is in April, she started to return and she continues to return in May as well.” – Dollar General (DG ) COO Jeffery Owen
- “Quarter-to-date, demand trends have accelerated from April across nameplates.” – Macy’s (M ) CEO Jeffrey Gennette
- “…in the last 3 months, it’s fallen from a 9% growth rate year-over-year to 3%. So the American consumer spending has slowed down.” – Bank of America (BAC ) CEO Brian Moynihan
- “I think the bottom line is demand is really strong. So demand in the second quarter continues at what we predicted as we closed out earnings in Q1. So demand is strong. Leisure demand, in particular, is very strong. Obviously, leisure was really strong last year, particularly close in demand on the leisure side. So some of that on the booking curve. Leisure has gone back — is beginning to go back to a more normal booking curve, but it’s very strong.” – Southwest Airlines (LUV ) CEO Bob Jordan
Not a moot point given how important Services have become in the economy and in the framing of monetary policy.
On inflation and wages, the Fed’s current focus, here’s what the ISM data infer:


But S&P Global’s data say:
- Service providers registered another marked increase in input costs. Greater business expenses were partly linked to increased supplier prices, but were largely attributed to higher wage bills and upward pressure on salaries. Although easing from that seen in April to the second-slowest since October 2020, the rate of input cost inflation remained historically elevated.
- Companies commonly stated that greater selling prices were due to the pass-through of higher costs to customers. The rate of charge inflation eased from April but was the second-fastest since September 2022 and sharper than the long-run series average.
BTW, the Cleveland Fed’s Inflation Nowcast, updated yesterday, sees no easing in core inflation just yet:

The HCOB Eurozone Services PMI Business Activity Index remained in firm growth territory during May with a reading of 55.1. While this was above the series long-run average by a notable margin, it was down from 56.2 in April and thereby indicated a weaker expansion.
May’s upturn was supported by a further improvement in demand for eurozone services. New business intakes rose solidly and for a fifth month in succession, although the rate of growth was the softest since February. Surveyed companies recorded a historically marked uplift in new work from external clients during May, with new export sales rising at one of the sharpest rates since data were first available in September 2014.
Service sector employment growth continued in May and remained much stronger than the long-run average for the series. Nevertheless, firms’ backlogs of work rose for a fourth straight month, indicating pressure on capacity.
Euro area service providers registered another steep rise in their operating costs, although the increase was the softest since August 2021. That said, firms were more aggressive in their price setting as average prices charged rose at a quicker pace than in April.
Finally, businesses remained optimistic towards the outlook for business activity in the year ahead. However, the overall level of positive sentiment dipped to the weakest seen in 2023 so far.
China: Business activity continues to rise sharply in May
|

- China Asks Big Banks to Cut Deposit Rates to Boost Growth The government escalates efforts to boost the world’s second-largest economy.
(…) The guidance, which follows similar rate reductions in September last year, will help alleviate pressure on lenders as they strive to balance shrinking margins and government directives to beef up lending support to the economy. (…)
After spiking in the first quarter, credit and new loans weakened in April as consumers and businesses curbed their borrowing. Households are saving more and paying down their mortgages, rather than taking on more debt, while businesses are faced with falling demand and declining profits. (…)
Once the deposit rates cut take effect, it would lower costs of banks, enabling them to reduce lending rates over time. That, in turn, would make it more attractive for consumers and businesses to borrow. Lower deposit rates would also make it less attractive for consumers to park their cash at banks.
Commercial Properties Face Massive Loan Bill Nearly $1.5 trillion in commercial mortgages is coming due over the next three years. Many of them are vulnerable to default.
(…) Fitch Ratings recently estimated that 35% of pooled securitized commercial mortgages coming due between April and December 2023 won’t be able to refinance based on current interest rates and the properties’ incomes and values. While many malls and hotels face high default risks, the situation is particularly dire for office owners.
Xiaojing Li, managing director at data company CoStar’s risk analytics team, estimates that as much as 83% of outstanding securitized office loans won’t be able to refinance if interest rates stay at current levels.
A rise in defaults could ripple through the commercial real-estate market by forcing distressed sales and pushing down property values. It could also hit regional and community banks that are heavily exposed to the sector, forcing them to write down the value of commercial mortgages on their books and set aside more cash to cover for losses.
Mortgage defaults are still rare but rising fast. The share of securitized office loans that are delinquent jumped to 4.02% in May, up from 2.77% in April and the highest level since 2018, according to data company Trepp. (…)
After the 2008 financial crisis, many banks were willing to extend troubled loans, buying owners time. Interest rates were falling, the crisis seemed temporary, and the hope was that building values would eventually recover to the point that borrowers could pay back their loans. That is exactly what happened.
This time, fewer lenders are betting on a quick recovery, at least in the office sector. Most expect remote work to be a lasting phenomenon, meaning many office towers could struggle for years to come.
“Banks don’t want to kick the can down the road anymore,” Edelstein said.
Here’s what Daniel Pinto, JPM’s COO said last week at a Bernstein conference (courtesy of The Transcript):
So we did a bit of work to understand the dynamics in the real estate market in the last several months. And so the real estate market’s totality in this country is around $13 trillion, $14 trillion, commercial real estate. Offices — the average insertion loan-to-value was in the low-50s. If you were to do a mark-to-market of that portfolio now at the new cap rates and new occupancy rates and all that, so that probably, the loan to value at the moment is between 70% to 80%.
So definitively, it has been a deterioration. So an asset class that an insertion was $2.2 trillion, giving or taking, probably now is sometime between $1.5 trillion to $1.7 trillion. The amount of lending against that is $1.2 trillion. That is roughly half by — provided by banks and half provided by the markets, CMBS, some insurance companies, other participants.
So out of all that, $600 billion of lending. So we have, including First Republic, around $15 billion, $16 billion. So it’s around 8% to 9% of the total amount of our commercial real estate exposure that two-thirds of — close to two-thirds of our commercial real estate portion is multi-family lending and multi-family lending. Essentially rents, they’ve been catching up with inflation, so it hasn’t been deterioration. We have a very conservative portfolio with relatively low loans to — loan to value.
So the office — and then you have retail that a lot is being refinanced already, industrial, the other segments, they’re fine.
So the issue is real estate. There is still a cushion overall. Clearly, lower quality business — buildings in some areas. West Coast, for example, they are more impaired. So I think that we see that as an opportunity. There will be plenty of opportunities to refinance all those portfolios and all those business, but it’s something that you want to keep an eye. It’s very likely the occupancy rates has gone up — has gone down to roughly, at the moment, 87%, 13%; vacancies starting [8%, 9%] (ph).
So if you were to go another few points out, a lot of the equity gets wiped out and then there may be some losses, but still cushion. And in the risking of things, it is a problem. Don’t get me wrong, because a lot of that exposure is with the regional banks and community banks. But I don’t think there is a systemic issue. It is something that will be dealt over time through restructuring all these loans. (…)
Well, there is no doubt, you can see that regional banks and smaller banks, they are building up liquidity, building up capital, they are lending a bit less. So for sure, there is a tightening credit conditions, particularly coming from that segment. I don’t think that the big banks have really changed the lending standards at this point, because of that. And I think that private credit has plenty of dry power to absorb some of the demand. (…)
Characteristics of a new bull market
From Richard Bernstein Advisors
It has been over seven months since the October lows, and during this time, the S&P 500® has rallied over 19%. Naturally, investors are pondering whether this marks the beginning of a new bull market. In this report, we aim to take an objective approach to determine if historical patterns can guide us in assessing the current situation. Spoiler alert: While it is certainly possible for this rally to evolve into a full-fledged bull market, historical precedent suggests it is far from a foregone conclusion. Here are some key takeaways from history:
No definitive technical thresholds: There are no specific technical indicators that serve as magical signals for a new bull market. It is not as simple as crossing a specific threshold to confirm the start of a bull market.
Breadth indicates strength: A broad-based rally with a wide range of sectors and stocks participating indicates a stronger foundation for a potential bull market.
The market leadership of bounces tends to be backward looking: The composition of a market bounce primarily reveals information about the past rather than the future.
Fundamentals matter: Rallies cannot transform into bull markets without support from underlying fundamentals.
This would not be an unprecedented start of a bull market or a bear market rally
Bear market rallies are relatively common occurrences. Putting aside the pandemic bear market in 2020 — which only lasted 23 trading days — the 2000 and 2007 bear markets each experienced four bear rallies of 10% or more, including some rallies of over 20% in both periods. In fact, the current 19% rally from the October lows is not much greater than the rally observed just last summer. Although seven months is a considerable duration since the 2022 lows, five of the past 14 bear markets since 1929 had longer periods between new lows being reached. It appears there are no magic levels or stop clocks that ring in the new bull market (Table 1).
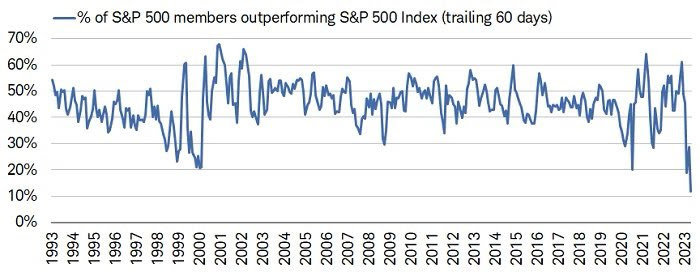
The narrow breadth of this rally raises technical concerns. Historically, bull markets have often commenced with broad participation across various sectors, but the current rally does not exhibit this characteristic. In fact, this would be the first bull market since at least 1990 to begin with the market cap-weighted S&P 500® index outperforming the equalweighted index (Chart 1).
Investors would be wise not to read too much into the sector leadership of the initial market bounces. Sector leadership in these rallies tends to merely be a reversal of the preceding drawdown and has historically had no relationship with what worked throughout the remainder of the bull market. Based on history, it is unsurprising that this year’s big winners (Tech and Comm Services) were last year’s big losers and that this year’s big losers (Energy and Health Care) were last year’s big winners. It would also be quite normal for the sector leadership of the upcoming cycle to look quite different from the rally we have seen thus far.
While historical technical statistics are interesting to discuss, at RBA, we believe that fundamentals ultimately drive market performance. Corporate profits, liquidity, and sentiment/valuation are the primary factors influencing market trends over time. A sustained market rally requires support from at least one, if not a combination, of these factors. The table below provides an overview of the prevailing macroeconomic conditions at bear market bottoms (Table 2) and 231 days into a new bull market (Table 3). It is important to note that this table is not exhaustive and does not include factors such as fiscal policy (e.g. TARP or PPP), bank lending standards or investor positioning, but still offers a general understanding of the circumstances surrounding historical market bottoms.
Investors always try to anticipate troughs in fundamentals, and the times they get it wrong turn out to be the bear market rallies discussed earlier in this piece. But investors also get it right sometimes, and thus it’s not surprising that the market has historically tended to bottom before earnings growth reaches its trough. Nevertheless, when the markets have bottomed in the absence of earnings support, there has always been significant support from either liquidity or sentiment/valuation (typically both) to pick up the slack:
Fed policy was more difficult to characterize before the Fed began targeting the Fed funds rate in the 1970s, but since then every bull market has begun with easing Fed policy.
Prior to the Internet Bubble, every bull market began with a trailing GAAP P/E multiple below the historical median of 16.6x.
Up until the pandemic, every bull market started with a P/E ratio on the prior peak EPS below the historical median of 15.4x.
The current rally may indeed be the early stages of a bull market, but this would truly be an unprecedented beginning without some signs of improving profit fundamentals, increasing liquidity or much cheaper valuations.


- From my EQUITY MARKETS: SEEKING FAIR VALUE post of January 10:
While it is true that equities eventually tend to do well after Fed easing episodes, “eventually” is the key word here: most times, the Fed eases for “good” reasons. Equity markets are not always in sync with the FOMC and some lags have been very costly.
I found 15 “Fed changes of posture” since 1957.
- From the first pause to the market low, the S&P 500 troughed 9 months after, on average. But the range is -3 months to +31 months.
- From the first cut to the market low, the S&P 500 troughed 6 months after, on average. But the range is -3 months to +21 months.
Actually, the S&P 500 declined after every Fed cut but five (1966, 1980, 1984, 1989, and 1995). Equities dropped between -4.0% to -47.7% (month end data) with an average of -16.1%. If we exclude 1974 (inflation) and 2001 and 2007 (bubbles), the average is -5.9% (range: 0.0% to -19.9%).
And I found no stable correlation with valuations, inflation and profit trends that could help decide when it might be safe to jump in.
A dovish turning Fed then only tells us to reduce our underweight and get ready to buy more aggressively.
A related point is that the stock market tends to wait until the Fed has started cutting rates (in other words, when a recession is either imminent or has already started) before making a low. If this really is a new bull market, it’s the first to start when the Fed is still hiking:
If a recession has only been delayed, it would be very strange if the low for the stock market were already in. If a downturn can be avoided altogether, maybe last year’s selloff can be classified as an extreme response to speculative excess, like the Black Monday Crash of 1987. But it’s a stretch. It’s very odd for a bull market to start at this point in the economic cycle.
FYI:
Population Growth Y/Y In Canada and U.S.