The enemy of knowledge is not ignorance, it’s the illusion of knowledge (Stephen Hawking)

It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so (Mark Twain)

Invest with smart knowledge and objective odds

THE DAILY EDGE: 15 FEBRUARY 2022: Prescient Consumers?

U.S. Inflation Outlook Falls for First Time Since October 2020 U.S. consumers don’t expect red-hot inflation levels to last in the long term.

(…) The authors drew in part from the January consumer survey from Federal Reserve Bank of New York, which showed that the median one-year-ahead inflation expectations fell for the first time since October 2020, to 5.8%. The outlook over three years dropped even more sharply, and the decline was broad-based across age, education and income.

Combined with data from the University of Michigan’s sentiment index, this indicates that consumers seem to recognize the unusual nature of the current bout of high inflation, the economists said in the blog post Monday. (…)

In their analysis, Williams and his five co-authors found that medium-term expectations have exhibited lower sensitivity to inflation surprises during the pandemic than before it. They also found that the five-year inflation outlook has remained “remarkably stable” since last summer.

Taken together, this suggests that consumers “do not view the current elevated inflation as very long-lasting,” they wrote.

All products and services surveyed by the New York Fed declined in January, including the year-ahead price changes for food, rent, gas, medical care, college education and gold. The survey also showed that the median households is expecting one-year-ahead earnings growth to rise by 3%, the same as last month. Last year, an average gain of 2.6% was expected.

The median three-year ahead inflation expectations decreased by 0.5 percentage point to 3.5%. (…)

The New York Fed President John Williams was a co-author of this analysis which will surely find its way to the next FOMC meeting, reassuring the doves, surely happy and secured seeing how the prescient American consumer shares their disinflationary views.

I suppose this next chart will not get inserted in the presentation package, however. Even though it reveals how non-economist Americans arrive at their three-year forecasts for “food, rent, gas, medical care, college education and gold” simply watching how prices fluctuate at their corner gas station.

image

More interesting from the survey, however, were these findings:

  • The median expected growth in household income fell by 0.1 percentage point to 3.3% in January, but remains above its trailing 12-month average of 2.9%.
  • Median year-ahead household spending growth expectations remained unchanged at 5.5%, substantially above its pre-pandemic level.

Since the median one-year-ahead inflation expectations from the survey is 5.8%, Americans seem willing to dip into their savings just to keep pace with inflation. They might be helped by lower gas prices but I bet they can’t forecast that.

CEOs are probably better placed to see what’s ahead: The WSJ tallies corporate conf. calls. CEOs trying to protect profit margins and stock valuations.

What CEOs Are Saying: ‘We See Inflation Going Up Everywhere’

  • “We do have a view that we have to have brands that earn the right to take pricing, and secondly, we very much are not looking to just pass through in price, but to do it intelligently because whilst it’s easy to respond to inflation by putting up the prices, there is clearly, as there is broad-based inflation, going to be a squeeze on real incomes in a number of countries.” (Feb. 10) (Coca-Cola)
  • “We see inflation going up everywhere. We have the brands, and we have again the capabilities to price. That’s what we’re doing in the majority of the markets…I’m a bit more cautious on emerging markets. I want to see a few more months to understand how the consumer is kind of absorbing all these high costs in multiple parts of their budget, household budget. But we’re feeling good about how our consumers are staying loyal to our brands in spite of some of our pricing decisions.” (Feb. 10) PepsiCo)
  • We do have the pricing coming into play, but it still remains a challenging environment, we think, in 2022.” (Feb. 7) (Hasbro)
  • “We have seen a lot of inflation…Labor costs have been up 20%, cattle costs are up—have been—they’re up 22%. Grain has been up 29%. This year in freight, I mentioned earlier, is up 32%. We’re not asking customers or the consumer ultimately to pay for our inefficiencies. We’re asking them to pay for inflation.” (Feb. 7) (Tyson Foods)
  • “You should think about the pricing pass-through as inflation or cost recovery mechanisms. Our primary driver for growth is new account wins, new customers and increasing participation. So we’re not trying to build margin by pricing pass-through. We’re trying to recover our costs.” (Feb. 8) (Aramark)
  • So we are expecting double-digit inflation in 2022, and the bulk of it is market-driven…We’re seeing inflation in ingredients and packaging, oil, corn, wheat, and on the packaging side, cans, cartons. So we’re seeing broad-based inflation across our ingredients.” (Feb. 10) (Kellogg)
  • “We plan that raw material inflation stays where it’s at for the full year. So that’s an assumption that we have in our planning. So again, we’ve got to continue to get the price to cover the logistics and any other raw inflation that we see.” (Feb. 8) (DuPont)
  • “We feel confident that we’re going to be able to offset raw material costs with price/mix. The real challenge in terms of 2022 earnings is going to be addressing inflation in other costs, so nonmaterial costs. And, obviously, we think price and mix can help with that. (Goodyear)
  • “We also do the analytical side of things where after we take pricing, we really do analyze what happens to transactions, and the good news is, we have so much data now with our loyalty database that we’re able to understand…any behavioral impacts from what we’re seeing, and we see very little resistance there.” (Feb. 8) (Chipotle) (…)

Miami, Tampa Post Largest Jump in Rents as Sun Belt Prices Soar

Among the 50 largest metropolitan areas, Tampa ranked No. 1 with a 27% surge in rent in the 12 months through January, according to the Zillow Observed Rent Index. Rents also rose 27% in the Miami area, while they were up 26% in No. 3 Phoenix, the data show.

The other metros in the top 10 include Austin, Texas; Las Vegas and two other Florida cities: Jacksonville and Orlando. (…)

According to LinkedIn data, Sun Belt cities such as Nashville, Tennessee; Austin and Tampa are among the largest per-capita recipients of net job migration. Miami didn’t make LinkedIn’s top 10 overall, but it has proved a popular destination for the emerging crypto economy, and has attracted some high-profile new finance and tech firms. (…)

FIBER: Industrial Commodity Price Strength Continues

The improvement in factory sector activity has given life to industrial commodity prices. The Industrial Materials Price Index from the Foundation for International Business and Economic Research (FIBER) strengthened 1.2% during the four weeks ended February 11 and increased 17.6% during the last year. The level of the price index stands at a record high for the series which dates back to January 1985. (…)

 image

  • Cass Inferred Freight Rates rose 3.0% m/m on a seasonally adjusted basis in January, to a new record. The freight rates accelerated to a 35% y/y increase in January from 33% in December.Cass Freight Index Rates January 2022
  • Inflation is growing on the farm. American farmers are paying significantly higher prices for herbicides, seed, fertilizer, equipment repairs and seasonal labor, eroding some of 2021’s windfall from rising crop prices. Higher farm costs could help further push up grocery bills in 2022, analysts say, following a year in which global food prices rose to decade highs.
EARNINGS WATCH

Roughly half of the 153 S&P 500 companies providing FY1 guidance this quarter guided below consensus. The median stock providing below-consensus guidance underperformed by 199 bps during the day following guidance, compared with 187 bps of outperformance for the median stock guiding more than 5% above consensus. (…)

At the sector level, Energy 2022 EPS estimates have experienced the largest positive revisions during the reporting season, while Industrials estimates have been cut most. In aggregate, the bottom-up consensus S&P 500 2022 EPS estimate has been lifted by just +0.6% despite 4Q results coming in 5% above expectations. (Goldman Sachs)

Goldman Sees a Big Change Coming to the Bond Market And it could be bad news for stocks.

(…) In one view, low yields are an ominous signal for future economic growth. In another, they reflect a change in the market’s ownership, with a greater proportion of U.S. government debt locked up by the Fed or by price-insensitive banks in general.
Whatever the reason, you can see just how ‘resilient’ yields have been in the below chart from Goldman Sachs Group Inc. economists led by Jan Hatzius.

They note that in 2021, the average move in the benchmark 10-year U.S. Treasury security has been just 24% of its long-term average, citing the standard-deviation measure during data surprises. In other words, bond yields haven’t been reacting very much to big shifts in U.S. economic data. (…)

relates to Goldman Sees a Big Change Coming to the Bond Market

“These lower-than-warranted sensitivities may be one reason financial conditions haven’t tightened very much in response to this year’s inflation and policy surprises.”

But they argue, that could all be about to change.

The bond market’s sensitivity to growth surprises should increase as we move into an era of higher inflation and interest rates, they say. That would eventually feed into financial conditions and potentially impact growth. “We see scope for increased data sensitivity that could in turn catalyze additional Financial Conditions Index tightening — particularly if inflation remains stronger-than-expected or if growth concerns return,” they write. (…)

It’s worth noting here that last week’s higher-than-expected inflation numbers already kicked off some big moves in bond yields, with the 10-year rising above 2% for the first time since 2019 and the two-year jumping more than 20 basis points in its biggest intraday move since 2009. (…)

Per Goldman:

“Some risk assets appear to be “having their cake and eating it too”: discounting a benign economic environment but not the funds rate adjustments needed to arrive there. After all, if some of the flatter yield curve reflects rising growth risks, then equities should embed a larger risk premium—and a lower expected value of earnings. Our equity strategists have lowered their price targets, and our credit strategists continue to forecast rising risk premia.”

Per J.P. Morgan:

“We believe risky asset markets have mostly adjusted to monetary policy shifts by now,” the JPMorgan analysts wrote in a note to clients Monday. “Short-term rates markets have likely moved too far vs. what CBs will ultimately deliver in hikes this year.” (…)

Kolanovic and his colleagues are steadfast equity bulls who favor cheap, economically sensitive stocks. Last month, the team urged investors to buy beaten-down stocks such as small caps after those companies priced in an economic recession — spurred by a Fed hawkish policy mistake — that’s unlikely to come true. (…)

Chinese Developers’ Sales Tumble in January Real-estate firms struggle to rekindle interest, despite Beijing’s recent attempts to ease restrictions

January contracted sales reports released in recent days by more than a dozen Chinese developers showed year-over-year declines ranging from about 10% to more than 80% for some companies. They also reflected price reductions by industry heavyweights such as Country Garden Holdings Co. Ltd. and Sunac China Holdings Ltd.

In all, total contracted sales of the country’s 100 largest developers saw a year-over-year drop of nearly 40% in January, according to earlier data from Chinese data provider CRIC. (…)

Financially weaker developers such as China Aoyuan Group Ltd. , Modern Land (China) Co. Ltd. and Fantasia Holdings Group Co. Ltd. suffered a sales drop of more than 70% last month compared with a year ago, according to their stock-exchange filings. Meanwhile, some stronger developers also didn’t manage to escape the slowdown in sales. Sales of China Vanke Co. Ltd. fell more than 50% to the equivalent of $5.6 billion. (…)

Land purchases by private developers have also slowed sharply, as their borrowing has been sharply curtailed. “The main source of internal funding for developers is still sales proceeds,” Mr. Tsang added. (…)

Buyers are currently hesitant to buy houses from developers with funding uncertainties. Meanwhile, many also have reservations about the real-estate market as a whole since Beijing is seemingly determined to try to slow down price increases, Mr. Macgregor said. (…)

China’s Approval of Pfizer Pill Opens Door to Ending Covid Zero

China’s surprise decision to clear Pfizer Inc.’s coronavirus pill for use offers rare insight into how Beijing may be planning to move beyond the Covid Zero strategy that’s leaving it increasingly isolated.

Paxlovid’s conditional approval over the weekend makes it the first foreign pharmaceutical product China has endorsed for Covid-19, with the country until now sticking steadfastly to domestically developed vaccines and therapeutics, even withholding approval for the highly potent mRNA shot co-produced by Pfizer and BioNTech SE. (…)

THE DAILY EDGE: 14 FEBRUARY 2022

CONSUMER WATCH

U. Of Michigan Survey Of Consumers

Sentiment continued its downward descent, reaching its worst level in a decade, falling a stunning 8.2% from last month and 19.7% from last February. The recent declines have been driven by weakening personal financial prospects, largely due to rising inflation, less confidence in the government’s economic policies, and the least favorable long term economic outlook in a decade.

Importantly, the entire February decline was among households with incomes of $100,000 or more; their Sentiment Index fell by 16.1% from last month, and 27.5% from last year. The impact of higher inflation on personal finances was spontaneously cited by one-third of all consumers, with nearly half of all consumers expecting declines in their inflation adjusted incomes during the year ahead. In addition, fewer households cited rising net household wealth since the pandemic low in May 2020, largely due to the falling likelihood of stock price increases in 2022.

The recent declines have meant that the Sentiment Index now signals the onset of a sustained downturn in consumer spending. (…)

image

I have never been a great fan of consumer sentiment surveys. They are generally merely coincident and often influenced by trends in gasoline prices. However, this recent survey is interesting given that its plunge is not happening during a recession and is happening in spite of the high accumulated savings and wealth of the past 2 years.

The fact that the wealthiest households come out as the most worried is even more concerning. They own most of the wealth and excess savings and are thus seen as a strong economic buffer. Can we really count on their economic support?

Americans generally spend their labor income (employment x hours x wages), using their savings in and around economic downturns to maintain their standard of living.

fredgraph - 2022-02-13T064700.147

The combination of the pandemic and the broad increase in inflation has brought about a meaningful decline in real wages in the last year. Consumers are surprised by the blow and this survey suggests that they are scared.

image

The U.of M.’s release ends with this note:

(…) The depth of the slump, however, is subject to several caveats that have not been present in prior downturns: the impact of unspent stimulus funds, the partisan distortion of expectations, and the pandemic’s disruption of spending and work patterns. Households have amassed substantial savings and reserve funds from the stimmies as well as due to more limited consumption choices, especially services. There may be a lessened need for additional precautionary savings and a greater desire to engage in discretionary spending.

Not happening just yet.

Through Feb. 6, the Chase card spending tracker is back to its pre-Covid trend after a very poor Christmas season but much of that is inflation. Actually, Chase says that the first week of February is down 0.6% YoY. That’s in nominal dollars…

image

The Chicago Fed Advance Retail Trade Summary (CARTS) tracks the U.S. Census Bureau’s Monthly Retail Trade Survey (MRTS) on a weekly basis, providing an early snapshot of national retail spending. “For the month of January, retail & food services sales excluding motor vehicles & parts (ex. auto) are projected to increase 0.4% from December on a seasonally adjusted basis and to be unchanged when adjusted for inflation.”

If so, real retail sales ex-auto would be down 14.7% annualized in the 3 months to January, the most important period of the year. FYI, at December 31, 2021, Amazon’s inventories were up 37% YoY. Its net sales rose 9.4% in Q4 and 22% for the full year. Dry spell for new orders ex-autos ahead, impacting economies world wide.

The WSJ’s Justin Lahart suggests that Americans are very anxious to spend… but that would only aggravate inflation and motivate the FOMC to be more aggressive.

(…) [Because of] people’s growing impatience with the pandemic, (…) the initial spending response to the fading of Omicron might be more pronounced than what occurred last winter. And there are other factors that could magnify that boost. (…)

Even so, expanding workforce participation and a better supply-chain situation probably won’t be enough to keep the Federal Reserve at bay. To the contrary, the increase in demand and boost to hiring that comes with the fading of Omicron could be stronger than the Fed—and most investors—now expect, leading the central bank to raise interest rates sharply. (…)

Since the Fed seems focused on fighting the inflation that excessive monetary and fiscal stimulations created, we should perhaps all hope that a scared/cautious consumer will provide us with a salutary soft landing.

David Rosenberg is not optimistic:

The year-over-year inflation rate is now at 7.5%, up from 7.0% in December, and the highest since February 1982. In the past sixty years, not once did the economy manage to skirt a recession at this level of inflation. Sad to say. The core inflation rate leapt to 6.0% from 5.5%. It goes without saying that this last period four decades ago occurred in the context of a recession and a bear market in equities; but the comparable inflation rates back then were on their way down and the Fed was in an easing cycle, not embarking on a tightening phase with a yield curve at half the slope it typically is heading into a rate-hiking process.

Rosie could have pointed out that in the past sixty years, “this level of inflation” [7.5%] only happened twice, somewhat diminishing his correlation with recessions. He could also have mentioned the 9.6% CPI print in April 1951, more than 2 years before the next recession.

Nevertheless, high inflation is generally not positive for the economy:

fredgraph - 2022-02-14T071149.431

Inflation Is Everywhere Some 55% of items saw price increases of 5% or higher in January.

The WSJ Editorial Board pressures the FOMC:

If you can believe it—and at this point you probably can—some people still say the sustained surge in prices across developed economies is transitory.

(…) the important fact is that the current inflation is nearly everywhere, including around the world. The United Kingdom’s central bank expects inflation to exceed 7% this spring and for inflation-adjusted living standards to decline by about 2% this year. Inflation in the eurozone hit 5.1% in January, prompting the perennially dovish European Central Bank to start contemplating an interest-rate increase this year.

(…) the supply chain, or a pandemic shift toward consuming goods instead of services, or a chip shortage, or some other one-off factor (…) doesn’t explain why everyone nonetheless has an unusual level of inflation. (…)

Some 73% of the [CPI] items saw annual price rises of 3% or higher in January, and some 55% of items saw inflation of 5% or higher.

This is the pattern that typified the inflation of the 1970s. (…)

The lesson of the 1970s is that once inflation appears, it needs to be corralled with urgency, or it will become embedded and increasingly hard to rein in. (…) The evidence of the inflation mistake is everywhere you look.

Maybe the Reserve Bank of Australia will show another alternative to the increasingly hawkish Fed: move the goal posts:

(…) “The approach that we are running at the moment, waiting for the evidence, does run the risk that inflation will be above 3% for a period of time and that risk is acceptable,” Lowe said in response to questions from a parliamentary panel on Friday. “We think running that risk is an appropriate thing to do.” (…)

EARNINGS WATCH

From Refinitiv/IBES:

Through Feb. 11, 358 companies in the S&P 500 Index have reported revenue for Q4 2021. Of these companies, 76.5% reported revenue above analyst expectations and 23.5% reported revenue below analyst expectations. In a typical quarter (since 2002), 62% of companies beat estimates and 38% miss estimates. Over the past four quarters, 79% of companies beat the estimates and 21% missed estimates.

In aggregate, companies are reporting revenues that are 2.6% above estimates, which compares to a long-term (since 2002) average surprise factor of 1.2% and the average surprise factor over the prior four quarters of 4.0%.

The estimated earnings growth rate for the S&P 500 for 21Q4 is 31.0%. If the energy sector is excluded, the growth rate declines to 22.6%.

The estimated revenue growth rate for the S&P 500 for 21Q4 is 14.5%. If the energy sector is excluded, the growth rate declines to 10.3%.

The estimated earnings growth rate for the S&P 500 for 22Q1 is 6.5%. If the energy sector is excluded, the growth rate declines to 2.1%.

Q1 estimates for the S&P 500 index have not declined so far but analysts are growing uncertain as time goes on:

image

image

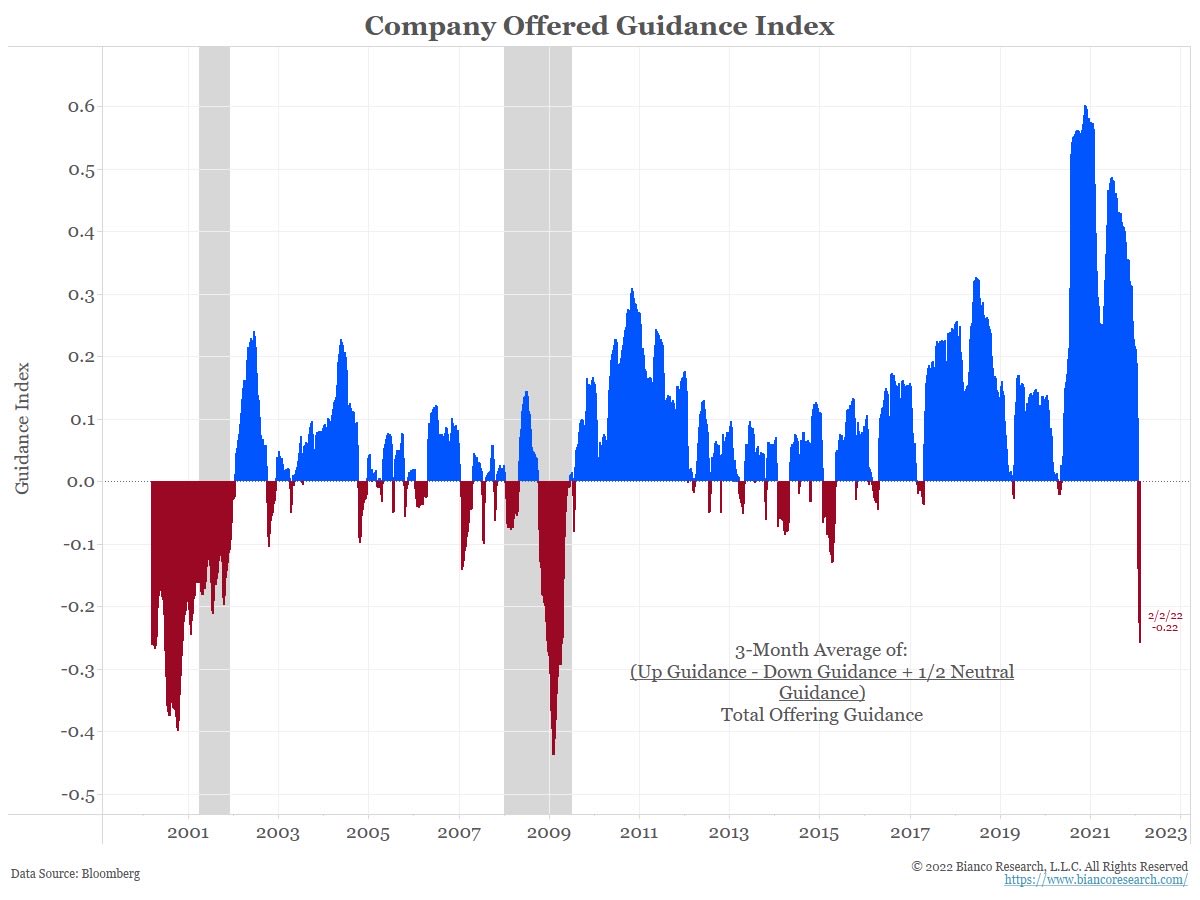
Much fewer S&P 500 companies are offering formal guidance, let alone positive guidance:

image

But Bloomberg tallies all U.S. companies and their guidance has turned most negative since 2009, per an index constructed by @biancoresearch and @Bloomberg via @LizAnnSonders.

Image

We are at Q1’s mid-point. Many companies will want to wait until the end of February to decide whether they need to pre-announce or not.

Equities remain very expensive and the acceleration of inflation is more than offsetting the current growth in profits (yellow line below). Generally a headwind for equity valuation. As John Authers writes: “For investors, the risk is that what companies give by being able to extract higher profit margins [through higher prices], they’ll also take by forcing higher rates and lower earnings multiples.”

image

Miners are likely to report a drop in profits. The top-five western diversified mining companies, including iron-ore giants Rio Tinto Group, Vale SA and BHP Group Ltd., may see combined 2021 second-half earnings of $73 billion, according to analysts’ estimates, compared to $82 billion in the first half. (…)

China’s property market, which consumes around a third of the country’s steel output, has been cooling — Bloomberg Intelligence expects new home starts to decline by 5% this year. And Beijing’s bid to cling to its Covid-zero status, even as regional outbreaks become more frequent, is the X factor that’s likely giving some resource executives sleepless nights. (…)

BHP and Rio have said that a lack of workers in key roles are having an impact on their operations. Fortescue Metals Group Ltd., the world’s No. 4 ore producer, reported last month that its costs had risen 20% over the past 12 months driven primarily by rising fuel prices and labor shortages. (…)

CREDIT MARKETS

John Authers:

(…) it’s always important to keep an eye on the credit market. Higher rates would logically lead to some kind of problem with solvency, and so it’s encouraging that to date the spreads of high-yield bonds compared to Treasuries remain historically low, even though they’re back up to their highest in some months. It is hard to discern any serious angst in the credit market at present:

Could it be that public credit markets are no longer the dependable canary in the coal mine they have always been?

Moody’s recently revealed that within the rated speculative-grade universe, 65-75% of issuers rated B3 Negative or lower (i.e. distressed borrowers) are owned by PE sponsors. Moody’s combed 12 prominent PE portfolios to find that they all “comprise borrowers that maintain average debt-to-Ebitda ratios of over 6x, which is a much higher average than for borrowers in bank loan portfolios and above the Federal Reserve’s Leverage Lending Guidance.”

TECHNICALS WATCH

Equity inflows have not even been close to being negative for a single week during this whole sell-off.

(EPFR via The Market Ear)

Yet, sellers broadly keep overwhelming buyers:

Source: Ned Davis Research

Larger cap equities have so far held up better than mid and small caps but beware:

S&P 500 Large Cap Index – 13/34–Week EMA Trendimage

Foreign Buying of US Equities:  This is one of those things you tend to see later in the cycle (and further reinforcing the widening valuation gap between US vs Global equities). Time to go against the crowd? (Callum Thomas)

Source:  @MFHoz

Wood’s ARK Stays the Course, Betting Big on Innovation Cathie Wood’s flagship ARK Innovation exchange-traded fund has bought more than $400 million of high-growth stocks over the past two weeks.

(…) She says the companies, which span videogaming, digital payments, trading and other industries, have the potential to change the world. (…)

“Today, we are still seeing things very differently from many others out there, particularly when it comes to inflation and interest rates and most importantly, innovation,” Ms. Wood said in a video to investors this month.

Ms. Wood added that a rise in Treasury yields to 3% would be more of an issue for mature growth companies facing steeper competition rather than the “super growth companies” she favors. (…)

ARKK has gotten $350.8 million of net inflows over the past week, including more than $300 million on Thursday, its biggest single-day inflow since June, according to FactSet. (…)

Bearish bets against ARKK account for nearly 16% of the fund’s shares, according to data from S3 Partners. That is down from a peak of 17.3% in mid-January, but well above levels over most of the fund’s lifespan. (…)

Besides that, an ETF designed to track the inverse of ARKK’s performance, the Tuttle Capital Short Innovation ETF, has taken net inflows of nearly $200 million from investors so far this year, pushing assets to $309.8 million, according to FactSet data. The ETF, which goes by the ticker SARK, is up 24% in 2022.

“There’s demand out there to be short ARKK,” said Matthew Tuttle, chief executive of Tuttle Capital. “We look at this as a better way to hedge your portfolio.” (…)

“I think history tells us not to bet against innovation,” [Ms. Wood] said.

ARK does good industry and corporate research. But history also tells us that one not only needs to get the story right, one also needs to get what that story is actually worth right. Profits and valuations matter.

qqq

FYI:

  • From housing economist Tom Lawler via CalculatedRisk which rightly notes that this is valuable demographic data.

image