The enemy of knowledge is not ignorance, it’s the illusion of knowledge (Stephen Hawking)

It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so (Mark Twain)

Invest with smart knowledge and objective odds

THE DAILY EDGE: 20 JANUARY 2021

Business Leaders Survey  Covering service firms in New York, northern New Jersey, and southwestern Connecticut

Activity in the region’s service sector declined at an accelerated pace, according to firms responding to the Federal Reserve Bank of New York’s January 2021 Business Leaders Survey. Nineteen percent of respondents reported that conditions improved over the month, while 51 percent said that conditions worsened.

chart (11)

The employment index moved down six points to -17.6, indicating that employment levels fell at a faster pace than last month. However, wages increased at a faster pace, with the wages index rising nine points to 19.9, its highest level since the onset of the pandemic.

Price increases picked up: The prices paid index rose six points to 38.9, and the prices received index rose eight points to 7.4, the first sign of any significant selling price increases since the pandemic began.

image

Yellen Makes Case for Sweeping Stimulus Package Biden’s choice for Treasury secretary urged lawmakers in her confirmation hearing to think big to avert a protracted economic downturn and put aside concerns about the mounting national debt.

(…) If she is confirmed by the Senate as expected, Ms. Yellen will become the administration’s top economic-policy spokesperson responsible for selling President-elect Joe Biden’s $1.9 trillion proposal, which includes another round of stimulus payments, extended jobless benefits, grants for small businesses and a nationwide vaccination program. After that, Ms. Yellen said, long-term investments will be needed in areas such as infrastructure and workforce training to help make the U.S. economy more competitive and productive. (…)

Like the other nominees, Ms. Yellen sounded a hawkish note on China, calling it “our most important strategic competitor” and promising to address its “abusive, unfair and illegal practices,” including undercutting American companies by dumping products, erecting trade barriers and stealing intellectual property. (…)

Ms. Yellen affirmed the U.S.’s commitment to market-determined exchange rates, and she made clear the U.S. doesn’t seek a weaker dollar for competitive advantage (…).

Ms. Yellen acknowledged the government’s mounting debt load, which stands at $21.6 trillion—or roughly 100% of a year’s economic output. But she urged lawmakers to put those concerns aside for now. Interest rates are at historic lows and expected to remain there for some time, making borrowing more affordable, she said. (…)

She assured senators that the Biden team doesn’t immediately plan to pursue tax increases but would consider them as part of a later package that focuses on long-term investments. (…)

CONSUMER WATCH
Survey: 53% of Americans say $600 coronavirus stimulus checks won’t last them a full month

(…) That total includes 18 percent who do not think the money is enough to make any impact on their finances.

Meanwhile, 71 percent of those receiving stimulus payments say the money will be very important or somewhat important to their near-term financial situation. (…)

Of the Americans who are planning to spend their stimulus checks, most (42 percent) say they’re going to put it toward monthly bills, such as their rent, mortgage or utilities. More than a quarter of respondents (25 percent) want to use the funds to pay down debt, and nearly a third (32 percent) are going to allot it toward their day-to-day essentials. Few Americans (8 percent) say they’re going to use their stimulus check to cover discretionary purchases, from dining out and shopping to taking a vacation.

Other Americans (6 percent) say they are inclined to invest it, while 30 percent plan to park the cash in their savings. A marginal 5 percent don’t know what they’ll do with the money, while 8 percent selected “other.” (…)

Americans’ plans for their stimulus check depend on how much money they make. An overwhelming majority of those earning under $30,000 annually (49 percent) say they’re going to put the funds toward monthly bills, while Americans making $80,000 and over a year were most likely to say they’re going to put their check toward their savings (39 percent). Those higher-income earners were also more than two times as likely to put the funds toward discretionary spending than their lower-income counterparts (at 16 percent versus 6 percent, respectively). (…)

unnamed - 2021-01-19T090909.673

Americans Aren’t Draining Their Retirement Funds in the Pandemic Workers affected by the pandemic continued to withdraw money from their retirement accounts in the final months of 2020. But, as happened earlier in the year, the increase was modest.

(…) In 2020, Fidelity Investments, the nation’s largest 401(k) provider, said 1.6 million people, or 6.3% of eligible participants in plans it administers, took some money out.

Fidelity and many other 401(k) record-keepers reported that although the number of people taking Covid-19-related withdrawals continued to grow in the final three months of 2020, the rate of increase was modest and largely in line with what occurred in earlier months, even as the option to take a penalty-free withdrawal ended on Dec. 31.

An additional 1% of 401(k) participants at Fidelity took what is known as a hardship distribution in 2020. These allow withdrawals for reasons including buying a home, preventing foreclosure or paying medical bills. In a typical year, about 2% take a hardship distribution.

At rival Vanguard Group, 5.7% of eligible participants took penalty-free withdrawals because of the crisis and 1.7% did so on hardship grounds in 2020. T. Rowe Price Group Inc. TROW 1.32% says 8% of eligible people in plans it administers with assets over $25 million took at least one withdrawal because of the pandemic. About 6% of people with 401(k) accounts that Alight Solutions LLC administers tapped their savings. (…)

The main reason withdrawal rates are lower than expected is that the unemployment crisis has disproportionately fallen on lower-income workers, who “are least likely to have a 401(k) plan,” said Brigitte Madrian, an economist at Brigham Young University. (…)

But there is a LOT of cash somewhere!

Households cash, checking & savings deposits (% of GDP 1950-2020)

unnamed (22)Source: Macrobond, ING
China’s Consumers Fall Behind Even as Its Economy Marches Forward One thing is missing from China’s otherwise remarkable economic recovery: a strong rebound in consumer spending.

(…) Domestic consumption has lagged, with retail sales shrinking 3.9% in 2020 from the previous year and demand for imported goods falling slightly.

There are many reasons for the weakness. While China’s unemployment rate never shot up as much as unemployment did in the U.S. and Europe, many employers cut salaries or hours, leaving consumers anxious. Many opted to save more—a common tendency in China, which has long had a high savings rate.

China’s government also didn’t hand out checks to consumers as the U.S. did, choosing instead to focus stimulus on helping factories and other businesses. (…)

“You have real restraints on where this recovery could go in China and how much its economy can speed up, if [the government] doesn’t do more on the consumption side,” said Leland Miller, chief executive officer of China Beige Book, a research firm that conducts private surveys on the Chinese economy. (…)

Yan Ling, a 25-year-old teacher living in the central city of Chongqing, said she plans to keep cutting back on what she calls unnecessary goods, such as snacks and clothes, in part because she worries that a possible resurgence of the pandemic could threaten her job stability. (…)

“The pandemic made me realize the importance of saving,” she said. (…)

Although China’s household savings rate edged down from a peak of 25% of gross domestic product in 2010 to 23% in 2018, it remains far above the global average, according to the International Monetary Fund. A survey by China’s central bank in the third quarter of 2020 found that 50% of households said they plan to save more, up from 45% a year earlier, while fewer said they intend to spend or invest more. (…)

While China’s urban employment rate recovered to pre-pandemic levels by September, estimated workloads were still down by more than 40% from normal, according to Gan Li, a professor of economics at Texas A&M University.

Average incomes among private-sector employees dropped 29% in September from a year earlier, his research showed.

“Low workload reflects a depressed demand, which means that recovery in the job market is still quite fragile,” said Mr. Gan. (…)

Chinese authorities have suggested in recent months that they will take steps to increase consumption this year with what some officials have described as “demand-side reforms,” though little detail has been revealed. (…)

Similar to the USA: “China has a “two-speed recovery,” led in particular by sales of housing. Meanwhile, consumer services are lagging behind seriously” (Bloomberg’s John Authers)

relates to The Madoff Look Is the Least of China Worries

When Investors Forget Fundamentals, the Market Is Broken Best explanation for how stocks have moved so far this year is the raw price of the stock, an almost meaningless number

(…) Forget a careful evaluation of future cash flow, valuation, brand power, management skill or even political sensitivity. I repeat: The best explanation for how stocks have moved so far this year is the price of the stock, an almost meaningless number.

Stocks priced below $1 have performed the best, followed by those between $1 and $2, and so on up almost perfectly. The worst performers have share prices above $100. It looks remarkably like investors are treating a low-price share as an indicator that the stock is a bargain, and a higher price as a sign that it is worse value for money. (…)

John Authers describes this new curve steepener!

[Here’s a] graph from SocGen’s chief quantitative strategist, Andrew Lapthorne. It ranks the small-cap stocks in the Russell 2000 by their share price — not their market cap, or their price-earnings ratio or anything like that, but just by the nominal price per share in dollars. The highest-priced stocks are on the left, while the cheapest are on the right. Black dots show how they have done since the vaccine trade got going in earnest at the beginning of November (on the right-hand scale), and the red dots show how well they’ve done so far this year (on the left-hand scale).

relates to The Madoff Look Is the Least of China Worries

Covid-19
BioNTech/Pfizer vaccine found effective against Covid-19 variant Laboratory-based study shows mutations were neutralised by antibodies in blood of vaccinated patients
Israeli hospital: 98% of staff who got 2nd shot have high-level COVID antibodies

A new serological study conducted at Sheba Medical Center in Ramat Gan has shown 98% of hospital workers who received the second dose of the coronavirus vaccine have developed a high level of antibodies to fight off the virus.

The study of 102 samples, taken a week after Israel began administering the second dose — when the vaccine is expected to reach peak effectiveness — showed most vaccinees had higher antibody counts than among those who have recovered from COVID-19.

The hospital says that a week after receiving the final dose, antibodies jumped to a level between 6 and 20 times higher than that observed after the first shot. (…)

Europe, Struggling to Exit the Pandemic, Faces Bleak 2021 Covid-19 infections and deaths remain stubbornly high across much of Europe while vaccination efforts are moving so slowly that widespread immunity is unlikely in the region before the fall, raising the prospect of a bleak 2021.

(…) The EU, with a population of around 450 million, had by late December ordered 300 million doses of the vaccine developed by BioNTech SE and Pfizer Inc., the first to be authorized in Western countries. That amount, expected to be delivered sometime by the fall, is sufficient for 150 million people, since inoculation requires two doses.

The bloc is now negotiating the order of another 200 million doses, which would start to become available late this year. (…)

The vaccination effort would be bolstered by the possible authorization on Jan. 29 of a shot developed by AstraZeneca PLC and the University of Oxford, with the bloc having preordered 300 million doses of it. (…)

France, Once a Vaccine Pioneer, Is Top Skeptic in Covid-19 Pandemic

(…) France’s mass vaccination campaign is off to a glacial start, with only around 422,000 people receiving the vaccine in more than three weeks since European regulators authorized the drug, far behind most other developed nations. A big reason: French officials are running up against deeply ingrained opposition that has made France among the world’s top vaccine skeptics.

An Ipsos poll conducted in December found that France ranked at the bottom of 15 countries on willingness to take a Covid-19 vaccine, with only 40% of the public saying they wanted the shot. Polls show that more than three-quarters of nursing home workers—who are among the government’s first target groups for the vaccine—don’t want to take it. (…)

Some of the world’s first antivaccination groups arose in France toward the end of the 19th century as Louis Pasteur pioneered the technique of using attenuated viruses to stimulate immunity. The Universal League of Antivaccinators was founded in France in 1880 to oppose proposals to make the smallpox vaccine obligatory. The league wrote to the French government three years later to oppose a government pension for Mr. Pasteur, calling his discoveries “disappointments and disasters.” (…)

The National League for Liberty in Vaccination, a French nonprofit founded in 1953, is one of the oldest antivaccine groups. France has been slower to adopt vaccines against diseases such as measles and rubella than the U.S. and some other developed countries. (…)

China Barricades Part of Capital as Northern Outbreak Escalates

Daxing district in southern Beijing, where its new airport is located, has been sealed off from the rest of the country after six infections were found there. The total number of cases in Beijing stands at 15, while over a thousand infections have been found nationwide since early January, mostly in China’s vast rural northern provinces.

While the number of cases is small compared to outbreaks in western countries, the flareup — fueled by an unusually cold winter — is China’s biggest coronavirus challenge since the Wuhan crisis a year ago given its potential to spread to the capital of over 20 million people, China’s cultural and political center. (…)

Residents in five Daxing apartment complexes have been barred from leaving their homes from Wednesday, said the local government, while students across the district were told to stay home. A wide range of public venues, including office buildings, hotels, restaurants, factories and supermarkets have been closed while the Daxing population undergoes mass testing.

In addition, Beijing is now requiring anyone coming to the city from overseas to be quarantined in isolation for 21 days — first at a centralized facility for 14 days, and then at their residence for seven days. They can then move around the city but are banned from any public gatherings for a further seven days. (…)

THE DAILY EDGE: 18 JANUARY 2021: The Big Debate (2)

U.S. Retail Sales Continue to Fall During December

Total retail sales including food service & drinking establishments declined 0.7% (+2.9% y/y) during December following a 1.4% November shortfall, revised from -1.1%. October’s 0.1% slip was unrevised. A 0.2% sales increase had been expected in the Action Economics Forecast Survey. Retail sales excluding motor vehicles & parts fell 1.4% (+1.1% y/y) in December after November’s 1.3% drop, revised from -0.9%. October’s 0.1% easing was unrevised.

In the retail control group, which excludes autos, gas stations, building materials & food services, retail sales fell 1.9% (+6.4% y/y) following a 1.1% decline slip and a 0.2% October dip. These declines followed three consecutive months of roughly 1.0% improvement. Retail sales excluding restaurants declined 0.3% last month (+6.3% y/y) after November’s 1.1% fall.

Sales of motor vehicle & parts dealerships rose 1.9% last month (10.1% y/y) and reversed November’s 1.5% drop. This compares to a 3.1% rise in unit light vehicle sales reported for December which made up November’s 3.0% decline. (…) building materials & garden store sales improved 0.9% (17.0% y/y), about the same as in November.

Sales of nonstore retailers declined 5.8% (+19.2% y/y) following a 1.6% November fall. (…) Shopping in department stores continued to weaken as sales were off 3.8% (-21.4% y/y), the fourth sharp decline in five months. (…) Working the other way last month were apparel & accessory store sales which rebounded 2.4% (-16.0% y/y) after falling 6.1% in November.

(…) food and beverage store sales fell 1.4% last month (+8.9% y/y) which reversed November’s 1.5% increase. In another nondiscretionary category, health & personal care products sales rose 1.1% (5.8% y/y) following two months of 0.4% decline.

Shutdowns and restrictions on dining out continued to reduce restaurant and drinking establishment sales, which weakened 4.5% last month (-21.2% y/y) off for the third straight month.

Lots of confusing data, offering many spinning options depending if one is a consumer bull or a consumer bear. Let’s try to remain objective.

“Control sales ex-restaurants” probably best illustrate the fundamental trend: after rather erratic monthly sales during the second half of 2019, the pandemic hit in March boosting grocery store sales during the lockdowns, followed by the surge in purchases of durable goods between May and September.

The negative spin highlights that control sales ex-restaurants declined 0.2% MoM in October, 1.1% in November and 2.0% in December. Is the consumer spent out and refusing to use its huge CARES Act-boosted savings?

fredgraph - 2021-01-16T100519.728

Not really say the positive spinners: control sales ex-restaurants were up 6.4% YoY in December, capping a quarter up 8.3% after +8.9% in Q3 and +0.4% in Q2. Full year 2020: +5.7% (following +4.1% in 2019), the best year since 2005. In fact, the second half growth of 8.6% was the most in at least 27 years.

Looking forward, the biggest debate has to be whether American and European consumers will use theirs huge savings to spend us into an inflationary boom forcing the fed to prematurely act on rates or whether they will keep high precautionary savings against eventual adverse events and/or higher taxes and thus keep growth and inflation subdued throughout the year.

The WSJ editorial board Saturday:

(…) “With interest rates at historic lows, we can not afford inaction,” President-elect Joe Biden declared Thursday night. He wasn’t kidding as he outlined a $1.9 trillion Covid spending plan, which comes on top of the $900 billion Congress appropriated last month, and the $2.9 trillion in the spring. And this is only Mr. Biden’s “first installment,” as Sen. Bernie Sanders put it. (…)

When the pandemic does ease, the economy is poised to take off without a single dollar more in government spending. Pent-up consumer demand—the savings rate is already double what it was pre-Covid—and the desire to socialize and travel again will lead to a sharp 2021 rebound even if Congress does nothing. (…)

Greg Ip in the same WSJ:

Though the economy is in bad shape, it may not need help on the scale Mr. Biden is proposing. GDP is now about 3%, or $700 billion annualized, below its normal, potential level, according to the Congressional Budget Office. The last round of stimulus could eliminate most of that gap, weakening the macroeconomic case for more.

If Congress passes stimulus close to what Mr. Biden proposes, it could supercharge an economy already poised to rebound once enough of the population is vaccinated to let the economy reopen. (…)

If Mr. Biden’s proposal is enacted, it would, along with $900 billion in December and previous measures, add $5.3 trillion to deficits, according to the Committee for a Responsible Federal Budget. That’s a staggering 25% of gross domestic product. (…)

But David Rosenberg has the opposite view, seeing the 20 million Americans on some sort of jobless benefits and the fact that

The areas where there will be pent-up demand comes to the grand total of 6% of total consumer spending and barely more than a 4% share of GDP. (…) Too many pundits live in the old paradigm of conspicuous consumption and not enough see the secular change in consumer behavior, towards a more frugal future, that lies ahead.

Adding the payback from the return to trends in the areas juiced up by the CARES Act dollars, Rosie concludes that “the pent-up demand, on net, will amount to $100 billion in a consumer spending arena that amounts to $1.5 trillion. So seriously. We are going ape over a net 0.7% add to spending growth and 0.5% to GDP growth?”

Hoisington Management takes a more academic stance against accelerating inflationary growth:

First, the massive void in economic activity and destruction of wealth created by the virus and related shutdowns of businesses in the U.S. and abroad will take years to fill. Second, U.S. fiscal multipliers are generally negative, rendering much government spending counterproductive in terms of stimulating economic growth. Third, monetary policy becomes much less impactful since the debt overhang was massive before the pandemic and is now even worse, not just in the United States but in virtually all parts of the world. (…)

GDP measures new output, but it has no capability of subtracting from the output measure the destruction of wealth caused by the pandemic and the economic shutdown response. Achieving the level of precrisis activity will in fact require years, owing to the wealth destruction. (…)

In my May 5, 2020 post The Day After, I wrote:

Consumers are the key to re-starting world demand. We are in uncharted territory but we can safely say that

  • previous employment levels are unlikely to be reached for years as many businesses will shrink/disappear and companies will seek to reduce costs;
  • the use of robots will accelerate;
  • fear and safe behavior will linger;
  • the savings rate will most likely rise as consumers build bigger financial shock absorbers;
  • pension angst will increase with ever rising pension deficits.
  • Will luxury, ostentatious wealth be out?

(…) It would be surprising if this pandemic made people loosen up, dissave and borrow merrily.

After each of the previous 3 recessions, Americans’ savings rate rose. Following the Great Financial Crisis, the jump was huge and sustained in spite of generally favorable economic and financial conditions.

This apparent secular change can only be reinforced by the current shock which, contrary to previous ones, is equally impacting everybody, everywhere. Baby boomers will become increasingly worried about their pensions, cash flows and asset values. Millennials, already bruised by the two previous recessions, will get even more prudent and frugal. These two generations, totalling some 145 million Americans, will be an even bigger drag on growth than they have been in the past 10 years.

My cautious early May spin did not expect :

  • multiple truly gigantic fiscal measures totalling, per Greg Ip, 25% of GDP in the U.S., including several large direct payments to consumers;
  • and a fairly rapid end to the pandemic with several highly effective vaccines found within 9 months when it used to take several years.

We now stand with a 12.9% savings rate before accounting for the additional $930 billion in direct payments to be received in two instalments early in 2021. These will boost disposable income by 5.4% and thus bring the savings rate, if totally unspent, above 18%.

In the last 60 years, the savings rate never exceeded 13.5% on an annual basis (1971-75). It averaged 7.3% between 2010 and 2019 and was 7.5% in 2019. Even with a cautious and frugal consumer, it seems preposterous to expect the U.S. savings rate to remain well above 10% for an extended period, particularly considering that

  • real interest rates are negative, a clear disincentive to save;
  • the heretofore frugal 72 million American millenials are now forming households and families, at an accelerating rate…

image

  • …within their own homes. A BLS study reveals that homeowners spend 154% more than renters on housing expenditures excluding mortgage and rent.

image

  • work-from-home is already making people move away from smaller but expensive inner-city dwellings to larger or less expensive suburban or rural dwellings.

True, there are still a lot of people out of work but the gradual return to normality will considerably reduce that number before the fall.

True, there has been much wealth destruction but what about the rise in house, equity and fixed asset prices, also not accounted for in GDP?

True, a segment of the population will keep hurting but that’s the normality after a recession. The lower rungs of the income and wealth deciles are never those who get the economy rolling again, benefitting only after the more affluent and the masses have restarted the economic engine for good. In December, 57.4% of the U.S. population was working, near the post GFC trough, but assuming that 75% of the 9 million service workers still pandemic-unemployed get back to work in 2021, the employment to population ratio would rise to 60.1%, its mid-2018 level, doing in a few months what took 8 years after the GFC.

As to Rosenberg’s estimate of the meager remaining pent-up demand,

  • I would never underestimate Americans’ yearning to consume;
  • I would never underestimate producer’s capabilities and creativity to boost demand;
  • and we should not underestimate authorities’ ways and means to incite consumers to part with some of their huge government-provided savings (e.g. temporary sales tax cuts).

Americans have been warned that the virus would hit hard in the fall-winter of 2020-21 and that the economy could suffer some more. Yet, the savings rate has declined every month since April, including a drop from 15.0% in August to 12.9% in December. And while retail sales declined sequentially from their abnormally high summer level, most spending categories remained strong through December:

image

These strong expenditures on goods have already helped restart the U.S. manufacturing sector:

Industrial Production in U.S. Rose a Solid 1.6% in December Production data provides a source of strength for the economy as consumer spending and employment gains slow

(…) Utilities output increased 6.2% in December from the previous month. Manufacturing output, the biggest component of industrial production, climbed 0.9% in December from the previous month. Manufacturing, which has regained much of the ground lost earlier in the pandemic, saw production end the year down 2.8%. Mining output rose 1.6% over the month, driven by drilling and extraction in the oil-and-gas sector. (…)

Actually, manufacturing production has been booming since its April trough but it is still 2.4% lower than its pre-pandemic level. Manufacturers’ and wholesalers’ inventories/sales ratio is back to their November 2019 level but retail inventories, including autos, remain well below normal.

fredgraph - 2021-01-16T081027.535

Recall that U.S. manufacturing was not particularly strong in 2019, down 0.2% for the year after +2.3% in 2018. We are still experiencing the effects of the pandemic, unable to assess the true condition of the industry post-tariff war and post-pandemic.

fredgraph - 2021-01-16T074541.462

Manufacturers themselves seem a little cautious as manufacturing employment remains 4.3% lower than last November. During the last 3 months, manufacturing production grew 3.2% sequentially but employment advanced only 0.9%. Average weekly hours are down 0.5% from November 2019. All productivity gains or risk management?

Total manufacturing new orders are still 1.9% below their February 2020 level and remain on the same declining trend since mid-2018. But the surge in retail sales of durable goods has spurred new durable goods orders (50% of total new orders) slightly above their 2019 average.

image

The positive spin is that manufacturing production is up 12.6% annualized in Q4’20 with strength in all categories through year-end as Haver Analytics shows:

image

In all, I side with the positive spinners in this debate about savings. So is Goldman Sachs which now expects an additional $1.1T in fiscal measures from the new Congress:

3. We Have Raised Our 2021 GDP Growth Forecast to +6.6% on a Full-Year Basis. Data available on request.

The other, related, big debate is the inflation outlook and the ensuing impact on bonds and equity markets. (See UNDER CONTROL).

America’s Big Banks Girded for Bad Loans. They’re Still Waiting. JPMorgan, Citigroup and Wells Fargo all reported better-than-expected earnings Friday. Reserve releases and Wall Street powered the results.

(…) Bankers warned that losses on credit cards, real-estate loans and other types of debts are still likely to rise when government relief programs eventually wear off, hitting their lowest-income customers in particular. (…) “You have a cloudy next two quarters, mixed economic information, almost 4,000 people dying a day,” JPMorgan Chief Executive Jamie Dimon said on a call with reporters. “Hopefully by some time in the summer you can have a very healthy economy.” (…)

Profit at the corporate and investment banking divisions jumped 82% at JPMorgan and 27% at Citigroup, their best fourth quarters on record. A flurry of new blank-check companies boosted equity-underwriting fees at JPMorgan and Citigroup by more than 80%.

But revenue fell at all three firms’ consumer banks—down 8% at JPMorgan, 14% at Citigroup and 5% at Wells Fargo. (…)

Banks also haven’t had to take losses on bad loans at nearly the pace initially feared. In fact, all three said that charge-offs were lower in the fourth-quarter than in the year-earlier period, before the pandemic brought the economy to a halt.

JPMorgan said it pulled $2.9 billion out of its reserves and Citigroup released $1.5 billion. Wells Fargo pulled $757 million, though it was largely because it sold off a book of student loans. They have continued to hold on to the vast majority of their reserves, fearing that some loan losses are just being pushed further into the future. (…)

Mr. Dimon noted the wide divergence between those who can navigate the coronavirus economy and those who can’t. For many big businesses, 2020 was a surprisingly good year. Many families, meanwhile, are close to running out of money.

One reason the banks have weathered the coronavirus economy is that they have been focusing on well-off consumers and big businesses since the financial crisis. Mr. Dimon noted that most of JPMorgan’s customers are prime borrowers, who have “a lot more income, a lot more savings, housing prices are up, they did not lose their jobs.” At the bottom of the pyramid, “it’s the opposite.”

Mr. Dimon noted the wide divergence between those who can navigate the coronavirus economy and those who can’t. For many big businesses, 2020 was a surprisingly good year. Many families, meanwhile, are close to running out of money.

One reason the banks have weathered the coronavirus economy is that they have been focusing on well-off consumers and big businesses since the financial crisis. Mr. Dimon noted that most of JPMorgan’s customers are prime borrowers, who have “a lot more income, a lot more savings, housing prices are up, they did not lose their jobs.” At the bottom of the pyramid, “it’s the opposite.”

JPMorgan Chase said Friday that it ended 2020 with $1.4 trillion in cash and marketable securities, which it said is some $450 billion in excess of what regulators require. Across Citigroup, PNC Financial Services, JPMorgan and Wells Fargo, which all reported earnings Friday, cash assets at year-end represented about 15% of their total assets, well up from less than 10% a year before.

Behind this is a wave of deposits driven by the Federal Reserve’s balance sheet expansion as well as fiscal stimulus. Large U.S. banks’ loans are now only about 56% of their deposits, down from around 70% before the Covid-19 pandemic, according to Fed data. (…)

JPMorgan cited the macroeconomy and corporate borrowers having lots of liquidity as major drivers of its release in wholesale lending; it held reserves flat for credit cards. (…)

The impact of all that excess cash on profitability is becoming a tad more muted. While banks don’t have great options for deploying cash without loan growth, the banks mostly increased their investment-securities assets in the fourth quarter, against the headwind of fast prepayment of mortgage-backed securities. This helped slow their quarterly declines in net interest margin, a measure of banks’ core profitability.

(…) consumers continue to pay down card balances at an “extraordinary” pace, according to JPMorgan, and many corporations are awash in cash of their own. (…)

THE USD
Dollar Shorts Mount Before Yellen Outlines Market-Based Policy Hedge funds boosted net short positions in the greenback to the highest since April 2018.
Yellen to Make Clear U.S. Doesn’t Seek Weak Dollar The expected remarks at her confirmation hearing Tuesday would represent a return to the U.S.’s hands-off approach, which President Trump had deviated from by often publicly calling for a lower dollar.
Foreign Investors Expect the Dollar to Remain Weak Increased stimulus spending could play a role in further softening of the U.S. currency. Investors are overwhelmingly betting the dollar will fall further, according to positioning data compiled by RBC Capital Markets.

For one, KKR is clearly bearish in the USD

In a world where the U.S. is leading the fiscal and monetary ‘race’ to stimulate the economy, there has to be a release valve for all of this potential profligate spending. We think the release valve is the U.S. dollar. An easy way to measure the potential change in the dollar’s standing is to look at relative interest rate differentials, particularly in real terms. (…) the United States now has real rates on par with Europe and well below most other major growth economies. It also now boasts a deficit that typically precedes sustained dollar weakness.

image

China’s Growth Beats Estimates as Economy Powers Out of Covid Gross domestic product climbed 6.5% in the final quarter from a year earlier.

Gross domestic product climbed 6.5% in the final quarter from a year earlier, pushing growth to 2.3% for the full year. That leaves the world’s second-largest economy driving global growth and potentially passing U.S. GDP sooner than previously expected. (…) Economists expect China’s GDP will expand 8.2% this year, continuing to outpace global peers even as they begin to recover due to a roll-out of vaccines. (…)

Retail sales fell 3.9% in 2020. Consumption spending per capita fell 4% in 2020 from a year earlier after adjusting for inflation, while investment in fixed assets such as real estate and infrastructure grew 2.9%, according to the statistics bureau. Industrial production surged, with China producing more than 1 billion tons of crude steel in 2020, an annual record. (…)

On a QoQ basis, GDP rose 2.6% in Q4 vs expectations for a 3.2% rise and an upwardly revised 3.0% gain in Q3. Growth in retail sales in December missed analyst forecasts and eased to 4.6% from November’s 5.0%.

Trump admin slams China’s Huawei, halting shipments from Intel, others – sources The Trump administration notified Huawei suppliers, including chipmaker Intel, that it is revoking certain licenses to sell to the Chinese company and intends to reject dozens of other applications to supply the telecommunications firm, people familiar with the matter told Reuters
EARNINGS WATCH

Per Refinitiv/IBES, we have 26 reports in, a 96% beat rate and a +27.4% surprise factor leading to a 12.9% YoY earnings growth on a +1.7% revenue growth rate for these 26 early reporters.

image

image
image
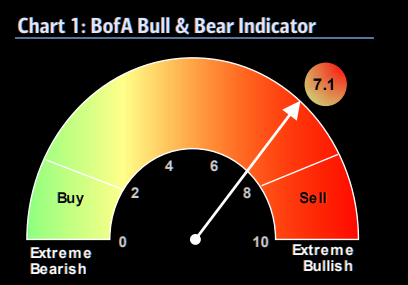
BofA’s bull and bear indicator

Many claim that this has been the absolutely most accurate of all the indicators out there.

An Old Foe of Banks Could Be Wall Street’s New Top Cop Gary Gensler is expected to be Joe Biden’s pick to take over the Securities and Exchange Commission. “He will do things that are controversial.”

(…) If he gets the assignment, he would be tasked with toughening regulation and enforcement of public companies and the finance industry.

He did that when he ran the Commodity Futures Trading Commission, a smaller regulatory sibling to the SEC, from 2009 to 2013. There, he steamrolled the opposition to write rules from scratch governing the markets for hundreds of trillions of dollars of derivatives. Some of these complex financial instruments were blamed for the 2008-09 financial crisis.

Lawyers, regulators and lobbyists say Mr. Gensler would likely be the most active, pro-regulatory SEC chairman since William Donaldson ran the agency in the wake of the corporate scandals of the early 2000s, or Arthur Levitt’s tenure during the Clinton administration. They also expect a renewed eagerness to pursue enforcement cases against major corporations and Wall Street banks. At the CFTC, Mr. Gensler earned a reputation for an aggressive, sharp-elbow style of management more reminiscent of Wall Street than Washington, at times even clashing with officials in his own party. (…)

Among Democrats’ top priorities are for the SEC to require more-comprehensive reporting from public companies about the risks they face from climate change or government efforts to curb it. They say financial disclosures should also include more information about companies’ diversity and worker pay. And Mr. Gensler is already facing calls to further tighten a 2019 rule that stopped short of requiring brokers to put their clients’ interests ahead of their own. (…)

Critics of the SEC in recent years have said it focused too much on helping companies raise capital and not enough on investor protections. Rick Fleming, the SEC’s in-house investor advocate, said in a Dec. 29 report that the agency “engaged in numerous rule-makings of a deregulatory nature” last year that “often had the effect of diminishing investor protections.”

Some have also called for the SEC to refocus enforcement efforts on large banks and hedge funds. Under recently departed chairman Jay Clayton, the enforcement program emphasized wrongdoing that harms less-sophisticated investors, including cryptocurrency scams, Ponzi schemes and investment advisers who fleeced clients with murky fees. (…)

Another target of Democrats may be private-equity firms and hedge funds, lightly regulated investment firms that are off limits to small investors. The firms captured 69% of the capital raised in 2019, while the regulated public markets accounted for 31%, according to SEC estimates. (…)

A Republican commissioner in 2013 said in a speech that lawsuits challenging CFTC regulations were evidence of a “flawed rule-making process that prioritized getting the rules done fast over getting them done right.” (…)

COVID-19

Hospitalizations peaking?

image

Let’s hope so but

Testing has been topping but the U.S. positivity rate exceeds 10%, more than twice the maximum level hoped for. The spreading of more infectious new variants could mean a sharp acceleration in cases in coming weeks.

Vaccination tracker:

More than 42.2 million doses in 51 countries have been administered, according to data collected by Bloomberg. The latest rate was roughly 2.43 million doses a day, on average.

Vaccinations in the U.S. began Dec. 14 with health-care workers, and so far 14.3 million shots have been given, according to a state-by-state tally by Bloomberg and data from the Centers for Disease Control and Prevention. In the last week, an average of 898,410 doses per day were administered.

The initial round of shots through early January has been doled out primarily through hospitals and other institutional health-care settings. The next phase will draw more on pharmacies and health clinics—places where vaccines are more traditionally administered—and will broaden the pool of people eligible to get the shots. Some states are turning sport stadiums and theme parks into mass vaccination centers. (Bloomberg)

Last week, CVS and Walgreen both said that they can each administer 20-25 million vaccines per month. Quick superficial math: 330M people minus 70M under 16 = 260M. Assume 20% refuse vaccination = 210M to be vaccinated minus 14M already done = 195M x 2 doses = 390M vaccines to be administered. CVS/Walgreen could do it under 10 months on their own.

Given vaccine availability, more than 50% of Americans could be vaccinated by the summer.

In China, Tech-Worker Deaths Spark Online Backlash Employee dissatisfaction with Chinese internet companies’ “996” culture—working 9 a.m. to 9 p.m. six days a week—has been brewing for years, but now public anger at the increasing powerful tech giants is rising.
ONCE UPON A TIME IN AMERICA

From Axios:

Almost 40 million firearms background checks were processed in 2020 — by far the most since the FBI began keeping records in 1998.

  • Nearly 4 million checks were processed in December alone — the single busiest month ever — and the total for 2020 was almost 40% higher than in 2019, which had been the previous record-holder.

This past year took our collective arsenal to new heights, with millions of Americans buying guns for the first time. That trend coincides with a moment of peak political and social tension.

Past spikes in firearms sales were prompted by fears of tightening gun control laws — usually in the aftermath of a mass shooting event or the election of liberal Democrats. But 2020’s surges seem to be connected to more general fears.

unnamed - 2021-01-17T104927.898

Data: FBI. Chart: Andrew Witherspoon/Axios