MANUFACTURING PMIs
The U.S. Manufacturing PMI will be out later this morning. China’s was released yesterday.
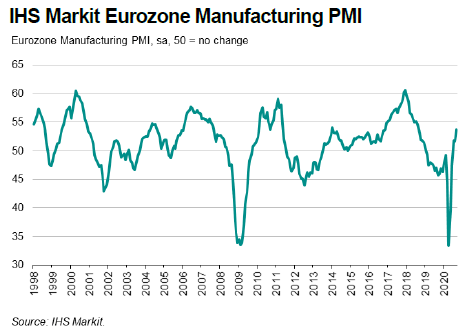
Eurozone manufacturing growth strongest for over two years
The IHS Markit Eurozone Manufacturing PMI® signalled an acceleration in growth of the manufacturing economy during September. After accounting for seasonal factors, the index posted 53.7, unchanged on the earlier flash reading and up from 51.7 in the previous month. Moreover, September marked the strongest growth in over two years and improved operating conditions have now been signalled for three months in a row.
All three market groups recorded a monthly improvement in operating conditions during September. Solid gains were seen in both the consumer and intermediate goods categories, but both lagged investment goods where growth was the strongest for over two years.
Germany led the upswing in regional manufacturing activity, with the respective PMI here hitting its highest level for 26 months. The Italian manufacturing sector also performed well, with growth also the strongest for over two years.
A solid improvement in operating conditions was seen in the Netherlands, whilst modest growth was registered in France and Austria. In contrast, Spain posted only a slight expansion while Greece saw no change and Ireland’s manufacturing recovery stalled.
Overall, manufacturing output and new orders received by euro area goods producers increased at considerable and accelerated rates during September. Growth rates in each instance were the strongest in over two-and-a-half years, although gains were principally centred on Germany.
A noticeable feature of the upturn in manufacturing new orders was the relative resurgence of export trade, with latest data showing a third successive month of growth and the sharpest gain since February 2018.
Strong gains in new work placed some pressure on firms, as evidenced by a solid rise in backlogs of work during September. Growth in work outstanding was the sharpest for nearly two-and-a-half years, although this failed to prevent further job losses as manufacturers sought productivity gains and control over costs given the uncertain near-term outlook. That said, the drop in employment was the weakest since February and noticeably slower than in recent months.
Firms also utilised inventories wherever possible to meet swelling production and order book requirements. Stocks of purchases and finished goods both declined markedly, with the drop in warehouse inventories the sharpest since the start of 2010.
Ongoing delays in the delivery of inputs also encouraged higher degrees of stock utilisation. Average lead times deteriorated for an eighth successive month and to the greatest degree since May. A rise in purchasing activity amongst eurozone manufacturers, the first recorded for 22 months, added to pressure on vendors.
Meanwhile, there was little change in prices during September. Input costs were marginally higher overall, albeit with some divergence in trends across the region. For instance, Germany saw a noticeable fall in prices, but Ireland registered a marked rise.
Meanwhile a slight fall during September ensured that output charges overall declined for a fifteenth successive month. Competitive pressures and a still-fragile demand environment weighed on pricing power.
Finally, confidence about the future improved during September to reach its highest level since April 2018. Italian manufacturers were the most confident, followed by German and Dutch goods producers.

Chris Williamson, Chief Business Economist at IHS Markit:
(…) The recovery would have been far more modest without Germany, however, where output has surged especially sharply to account for around half of the region’s overall expansion in September. Germany’s performance contrasted markedly with modest production growth in Spain, slowdowns in Italy and Austria, plus a particularly worrying return to contraction in Ireland. Excluding Germany, output growth would have weakened to the lowest since June.
Divergent export performance explains much of the difference between national production trends, with Germany the stand-out leader in terms of growth in September, led by a strengthening of demand for investment goods such as plant and machinery.
Encouragingly, optimism about the future rose not only in Germany but also in France, Italy, Spain and Austria, hinting that the upturn could broaden out in coming months. Without a more broad-based recovery, the sustainability of the upturn looks at risk, with additional worries fuelled by rising Covid-19 infection rates.
Japan: Manufacturing PMI reaches seven-month high
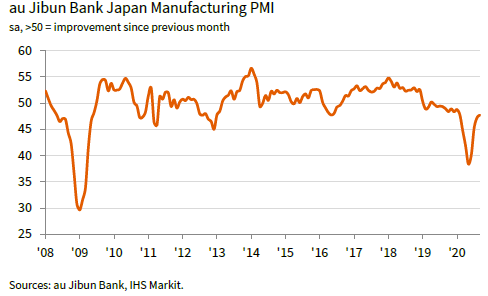
September data indicated that the Japanese manufacturing sector moved another step closer to stabilisation, helped by the slowest fall in new orders since January. At the same time, hopes of a longer-term recovery in production volumes strengthened, with growth expectations for the year ahead rising to the highest since May 2018.
At 47.7 in September, up from 47.3 in August, the headline au Jibun Bank Japan Manufacturing Purchasing Managers’ Index™ (PMI)® rose for the fourth month in a row following the low point seen in May (38.4). The latest reading was the highest since February, albeit still below the neutral 50.0 value.
Supporting the rise in the PMI during September, latest data indicated the weakest decline in production volumes for seven months. Manufacturers reporting a drop in output mostly commented on project cancellations and subdued demand levels due to the coronavirus disease 2019 (COVID-19) pandemic. However, the latest decrease in production was modest in comparison to the rate of contraction seen during the second quarter of the year.
New orders fell to the least marked extent since January, which highlighted a turnaround from the severe downward trend seen in the earlier stages of the pandemic. Some manufacturers commented on a boost from rising demand from clients in China and South East Asia, which partly offset weakness in other major overseas markets. Total new export sales fell again in September, but at the slowest pace for eight months.
Employment remained relatively stable across the manufacturing sector, with this index only fractionally below the 50.0 no-change threshold. Where a decrease in payrolls was reported, survey respondents mostly cited the non-replacement of retired staff. However, backlogs fell at a sharp rate, which suggested a lack of pressure on production capacity.
Supply chain disruptions showed signs of easing in September, with lead times lengthening to the least marked degree in the current eight-month sequence of longer delivery times. Improvements in transport availability and fewer delays at international borders allowed manufacturers to boost shipments of finished goods in September. This resulted in the fastest drop in post-production inventories for seven months.
There were again reports that rising transport costs and increased raw material prices had pushed up average cost burdens across the manufacturing sector. Input prices have now risen for four months running, although the rate of inflation remained only marginal in September. Margins were also under pressure, as suggested by another slight reduction in average prices charged by manufacturing companies.
Manufacturers in Japan are increasingly confident that production volumes will expand during the next 12 months. More than twice as many survey respondents (37%) expect a rise in their output levels as those that anticipate a reduction (18%). The resulting index signalled the strongest business expectations since May 2018, which was mainly linked to hopes that the global economic impact of the pandemic will fade in the next 12 months.
Key will be Services PMIs coming out next Monday.
-
American, United to Cut 32,000 Jobs as Washington Debates Relief The airlines will go forward for now with a total of more than 32,000 job cuts after lawmakers were unable to agree on a broad coronavirus-relief package, the airlines told employees.
-
Allstate to Lay Off 3,800 Employees One of the U.S.’s largest insurers said it plans to lay off about 8% of its approximately 46,000 workers.
(…) The pandemic resulted in “fewer auto accidents, so you need fewer claims people,” Mr. Wilson said. Of the layoffs, “somewhere between 25% and 30% are due to the fact that we have fewer claims,” he said. (…)
House Delays Vote on $2.2 Trillion Coronavirus Bill Lacking GOP Backing Democratic aides say postponement is to allow two sides one more day to keep talking
- Goldman Sachs is not optimistic:
Negotiations on a COVID-19 fiscal relief package continue and while there is a chance a deal could be reached in the next day or so, the odds still seem stacked against additional pre-election fiscal stimulus. The outlook should be fairly clear by tomorrow, when the House is scheduled to depart until after the election and is likely to vote on the recently introduced House Democratic fiscal package before then. If a vote occurs on that bill, the odds of pre-election stimulus would approach zero, we believe. A delay in the vote would be a positive signal, though there remain several obstacles to an agreement that would still need to be overcome.
ECB Steps Up Support for Credit Markets The European Central Bank is ramping up its corporate-bond purchases, increasing its support for the region’s companies as weaker economic data weigh on credit markets.
U.S. Pending Home Sales Climb Again
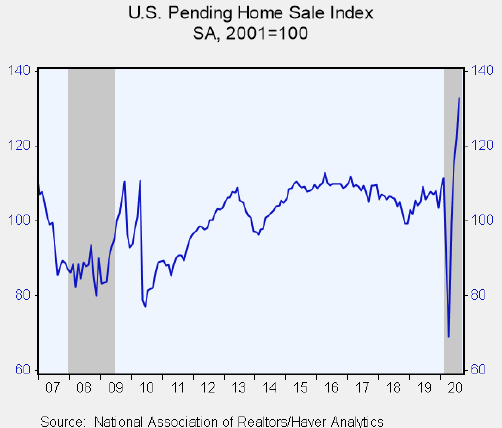
Pending home sales rose for the fourth consecutive month in August, rising 8.8% m/m (+24.2% y/y) to a record high of 132.8 (2001=100), according to data released by the National Association of Realtors. While the August gain was still slower than the dramatic rebounds in May and June, it reflected a pickup in activity from the 5.9% m/m rise in July. The rise in home sales has been supported by the continued decline in mortgage rates with the rate on a 30-year mortgage in the Mortgage Bankers Association weekly survey falling to a record low in August.
Pending home sales rose again in all the major regions of the country. And while August gains were generally smaller than the rebounds in May and June, they were meaningfully stronger than those in July, apart from the Northeast. The largest monthly gain in August was in the West with pending sales up 13.1% m/m (+13.2% y/y) after a 6.8% monthly increase in July. Pending sales rose 8.6% m/m to new record highs in both the Midwest and the South. These series begin in 2001. From a year ago, sales were up 15.4% in the Midwest and 14.9% in the South. After an outsized 25.2% m/m jump in July, pending sales in the Northeast slowed sharply in August, gaining 4.3% m/m (+20.6%y/y).
Momentum in the Recovery in Consumer Confidence Slowed in September
After a slight decrease last week, consumer confidence recovered this week to its highest point since mid-March. However, the rate at which consumer confidence is growing at the end of the month is not as great as it was throughout August and early September. Top takeaways from this week’s data include: growth in consumer confidence slowed during the second half of September, the gap between Main Street and Wall Street narrowed, and the share of furloughed workers who no longer expect to be brought back to work by their former employers rose to 34%, up from 30% in August. (Morning Consult)

 This Overlooked Variable Is the Key to the Pandemic
This is the most interesting article I have read on the pandemic, well worth the time.
Coronavirus Super-Spreaders Drove Explosive Outbreak in India
(…) Prolific SARS-CoV-2 transmitters tended to spread the virus during prolonged close contact on buses and other forms of transportation, according to the researchers, who were also from Princeton University, Johns Hopkins Bloomberg School of Public Health, and Indian state governments. In such settings, there was a 79% chance of an infection occurring.
That compares with only a 1 in 40 chance of catching the virus from someone in the community who wasn’t a household member, Laxminarayan said. Children under 14, though, were found to be frequent “silent” spreaders of the virus, especially to their parents and peers. (…)
Japan’s three C’s in action: crowds in closed spaces in close contact.
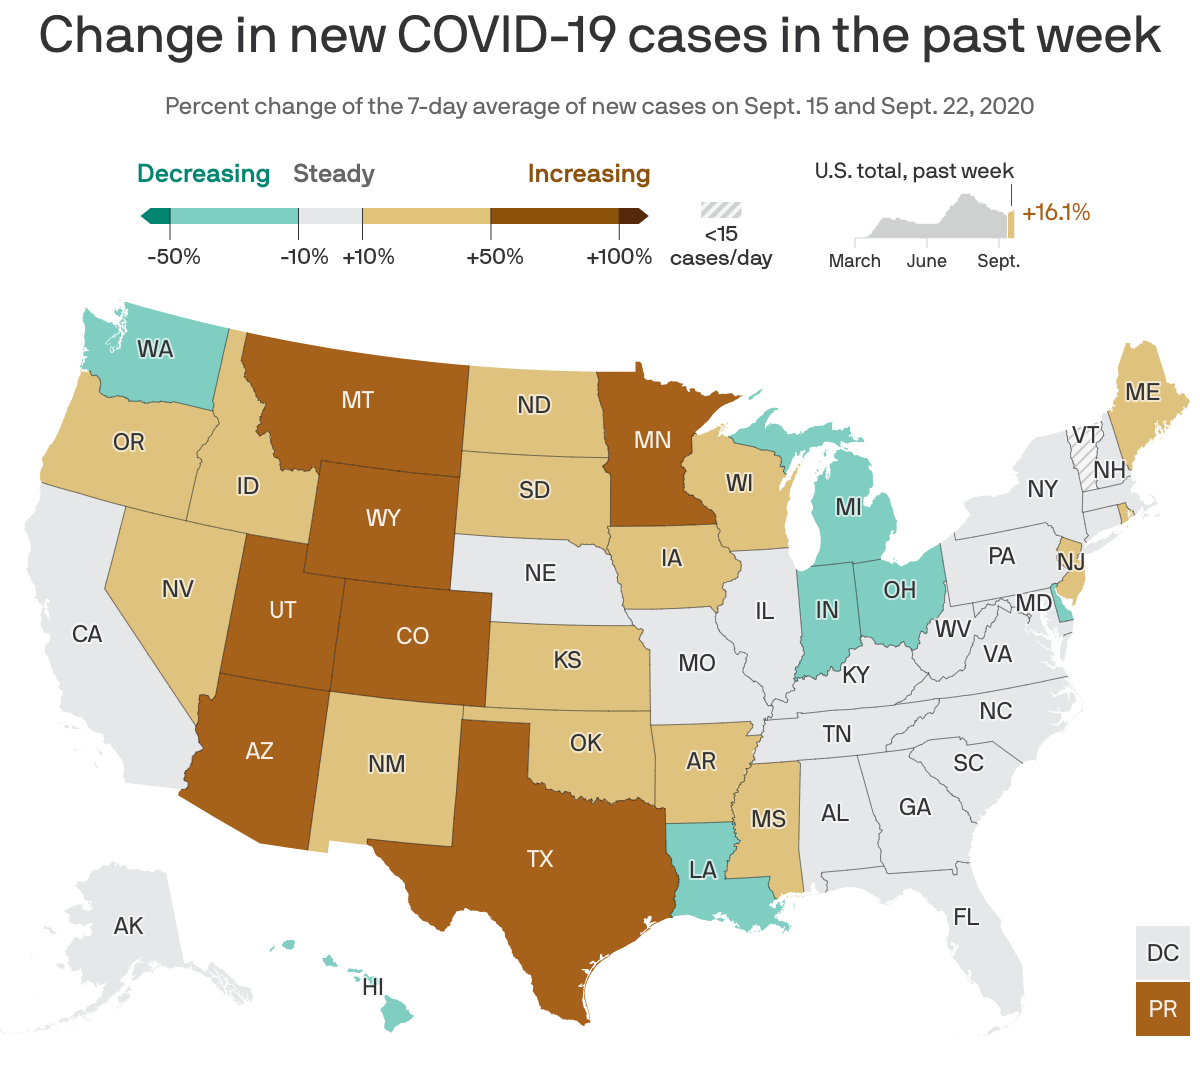
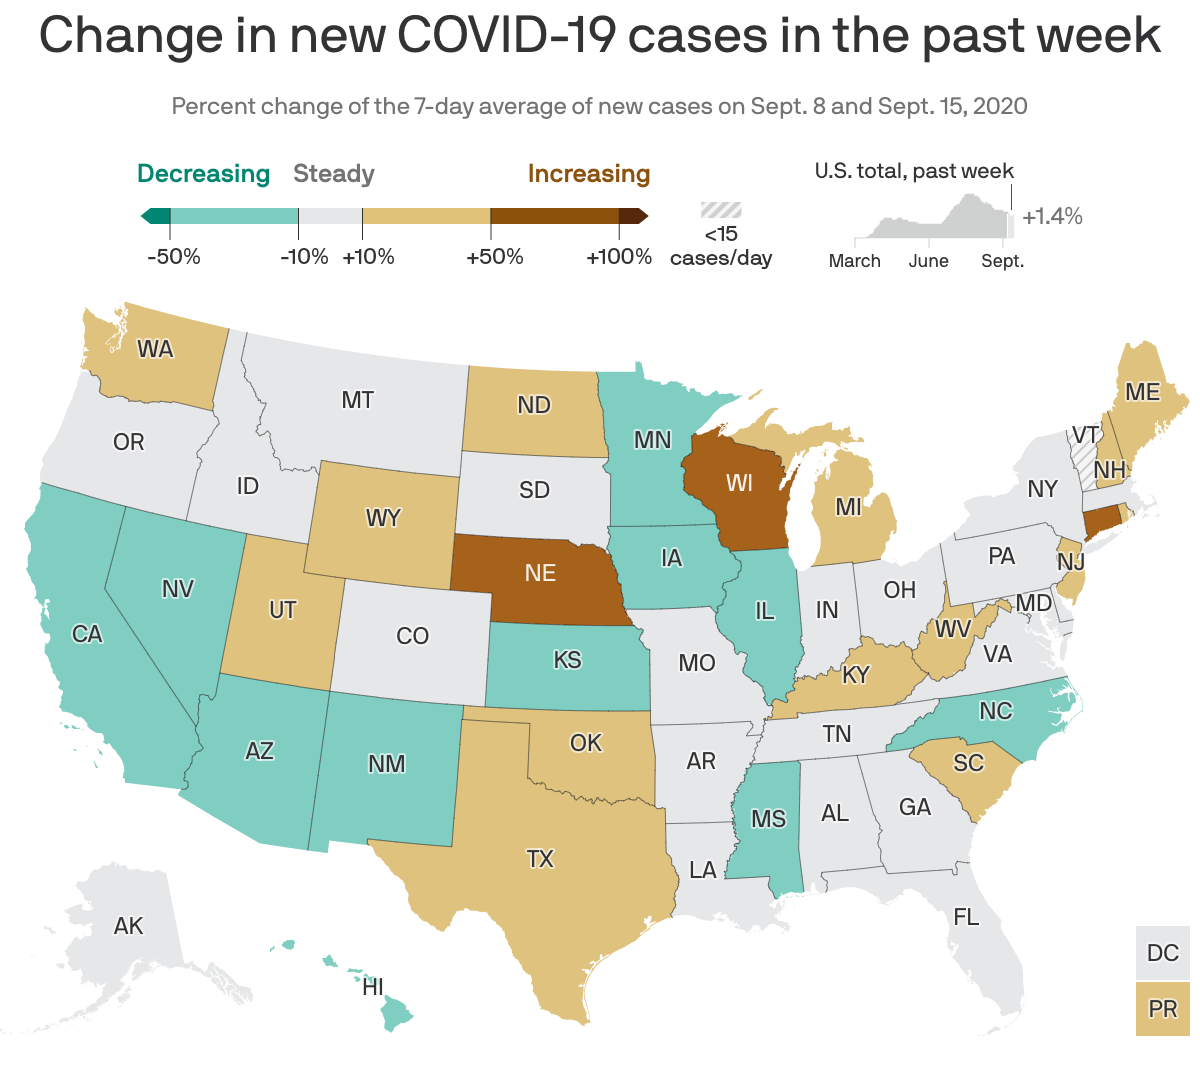
Axios has a weekly map showing the spreading of virus cases across the U.S. states. It is increasing at a slower rate but gradually concentrating in the northern states.
September 22 to 29
September 15 to 22 September 8 to 15
TECHNICALS WATCH
- The 13/34–Week EMA Trend (CMG Wealth)

- Don’t Fight the Tape or the Fed
Personally, I would not label this “don’t fight the Fed” as CMG Wealth does. The indicators that comprise this reading are a combination of NDR’s Big Mo and the 10-Year Treasury yield, really equity market momentum and long-term rates. “Since 1980, the indicator has only hit the -2 level less than 6% of the time with very poor equity market returns.”

Fed Caps Big Banks’ Dividends, Halts Share Buybacks in Fourth Quarter The biggest U.S. banks will face restrictions on dividends and share buybacks for another three months, the Federal Reserve said, citing the need to conserve capital during the coronavirus-induced downturn.
The biggest U.S. banks will face restrictions on dividends and share buybacks for another three months, the Federal Reserve said Wednesday, citing the need to conserve capital during the coronavirus-induced downturn.
The Fed said it would maintain prohibitions on share buybacks and a cap on dividend payments by 33 banks with more than $100 billion in assets until the end of year. The restrictions, imposed for the third quarter, were due to expire Wednesday. (…)
In another sign of the uncertainty facing the industry and the broader economy, the Fed has required big banks to undergo a second round of so-called stress tests later this year, based on two coronavirus-related recession scenarios. Results of the tests, designed to ensure banks can continue to lend in a crisis, will be announced by the end of the year.
Banks are in a much stronger position now than they were during the financial crisis of 2008. But an analysis the Fed conducted this summer found that if the economy takes a long time to recover, banks could experience losses on a similar scale. It said at the time that limiting shareholder payouts would help keep banks healthy during the recession. (…)
Palantir Grabs $21 Billion Valuation, but Debut Comes With a Hiccup Palantir and Asana made history by both completing direct listings on the New York Stock Exchange on the same day, a milestone for the little-tested way to go public.
(…) By the time markets closed, Palantir’s stock was worth less than it was earlier in the day. The stock closed at $9.50—below its high of $11.42 and its first-trade price. Still, that netted the company a valuation of roughly $21 billion, and shares remained above the $7.31 and $9.17 average prices where they had changed hands in private trades in August and September, respectively. (…)
Asana’s shares closed at $28.80, which is 37% above their reference price of $21 and above the average price of $25.11 where private shares changed hands in August. That gave the company, which makes workplace tools for productivity and communication, a valuation of about $5.9 billion. (…)
The structure of a direct listing typically allows existing shareholders and employees to sell most or all of their shares immediately rather than wait for the mandated lockup of 180 days in most traditional IPOs. Palantir is taking steps to limit the supply of stock on the market by only allowing existing holders to sell 20% of their shares until early next year. That scarcity could serve to bolster the stock price.


