The enemy of knowledge is not ignorance, it’s the illusion of knowledge (Stephen Hawking)

It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so (Mark Twain)

Invest with smart knowledge and objective odds

THE DAILY EDGE: 18 JANUARY 2019

THE ART OF THE DEAL

This bad sitcom just keeps on surprising us!

U.S. Debates Lifting China Tariffs to Hasten Trade Deal U.S. officials are debating easing tariffs on Chinese imports as a way to calm markets and give Beijing an incentive to make deeper concessions on trade.

The idea of lifting some or all tariffs was proposed by Treasury Secretary Steven Mnuchin in a series of strategy meetings, according to people close to internal deliberations. They say the aim is to advance trade talks and win China’s support for longer-term reforms.

But Mr. Mnuchin faces resistance from U.S. Trade Representative Robert Lighthizer, who is concerned that any concession could be seen as a sign of weakness, these people said. (…)

In past China discussions, Mr. Trump has sided with Mr. Lighthizer on tariffs, rather than Mr. Mnuchin. But this time, the president has made clear he wants a deal—and is pressing Mr. Lighthizer to deliver one, according to people familiar with the discussions.

“I think we’re going to be able to do a deal with China,” he told reporters Monday.

The U.S. and China are seeking to resolve their dispute ahead of a March 1 deadline. At 12:01 a.m. the following day, tariffs on $200 billion of Chinese goods are scheduled to jump to 25% from the current 10%. The higher levies could batter U.S. importers and further harm an already weakening Chinese economy. (…)

But Mr. Lighthizer has shown some signs of easing his position, say people involved in the talks, including raising the possibility that some tariffs could be reduced if the U.S. strikes a favorable deal on March 1. (…)

Even high-level strategizing about eliminating tariffs represents a striking turnaround for an administration that hasn’t lifted steel and aluminum tariffs on its closest allies and is still threatening them with a 25% levy on car imports. (…)

Presidential adviser Jared Kushner has indicated some sympathy for lifting at least some tariffs, say those tracking the talks, but not on the scale of Mr. Mnuchin. (…)

The WaPo adds:

  • “He’s driving toward a deal,” said one business executive who asked not to be named, to avoid angering the administration. “He wants a deal and may be willing to settle for not very much to get it.”

  • In talks in Beijing this month, Chinese officials offered to increase annual purchases from the United States by about 30 percent, or roughly $40 billion, the business executive said. That figure is consistent with internal administration estimates of U.S. capacity to fill new Chinese orders, the executive said. (…) Chinese officials also expressed doubt that U.S. businesses could meet a sudden spike in orders, especially for liquefied natural gas and crude oil, according to two business executives familiar with the talks.


  • Sides Hatch Plan to Reopen Chicken Trade

U.S. and Chinese trade officials are in talks to reopen China’s market to U.S. chicken exports as they seek to forge a new trade deal, according to people familiar with the discussions. (…)

If the talks are successful, U.S. meat giants like Sanderson Farms Inc., Pilgrim’s Pride Corp.and Tyson Foods Inc. could begin clawing back some of the business in China, a key market that represented hundreds of millions of dollars in annual sales before a ban was implemented in 2015 in response to an outbreak of avian flu in the U.S.

China’s immense appetite for chicken feet, along with dark meat and other products less popular among Western consumers, has made the loss of that market particularly painful for chicken processors. (…)

Sitcom watchers in need to make decisions are confused, to say the least.
image

We should all be worried:

Source: Pantheon Macroeconomics (via The Daily Shot)

Source: TS Lombard (via The Daily Shot)

Tax reform consequences?

Home Prices Are Dropping All Over New York City

In almost every Manhattan neighborhood, at least a fifth of the listings got a price cut in the last three months of 2018, data from StreetEasy show. The biggest share was in the East Village, where 33 percent of homes were offered for less.

Inventory is piling up across the city, and that’s good news for buyers in search of a bargain. For sellers with dreams of making a big profit, it’s time for a reality check.

“What we’re seeing right now is a lot of folks being forced to adjust their expectations,” said Grant Long, senior economist at StreetEasy. “We expect that prices are going to have to come down even more for it to make sense for a lot of buyers who are in the market.” (…)

EARNINGS WATCH

Amid the political chaos and confusion and the ensuing economic uncertainty, corporate America keeps delivering, but for how long?

As of Jan. 16, 77% of the 44 companies that have reported Q4 beat estimates. The earnings surprise factor is +1.6%. At the same time during the Q3’18 earnings season, the beat rate on 41 reporters (not necessarily the same) was 88% and the surprise factor +4.0%. On revenues, the beat rate is 59% so far in Q4 (+0.1%) compared with 71% (+0.5%) 3 months ago.

Earnings growth for the 44 companies having reported is 21.8% on revenue growth of 7.9% vs 28.7% on 7.5% for the 41 reporters in Q3.

The blended growth for Q4 is now 14.2%, down from 15.8% 2 weeks ago. It was 19.9% for Q3’18 last Oct. 16 but it ended up 28.4% for the full quarter.

Trailing EPS are now $162.00, up 32% YoY and 4.1% from their level 3 months ago. Trailing EPS are above the full year estimate of $161.45 (per Refinitiv), potentially leading to higher estimates for 2019.

Rising earnings and stable inflation are keeping the Rule of 20 Fair value positively sloped, just about the only fundamental factor still solid and supportive for the U.S. market.

image

TECHNICALS WATCH

From Steve Blumenthal’s Trade Signals:

  • Last week, the Ned Davis Research (NDR) CMG Large Cap Momentum Index signaled a reduction in equity exposure to 40% from 80%. The balance of the equity market signals remain in sell signals.

  • 13/34–Week EMA Trend Chart


The only bullish indicators from Steve’s list are sentiment indicators from Ned Davis Research:

  • NDR Crowd Sentiment Poll: Extreme Pessimism (S/T Bullish for Equities). Current weekly sentiment reading is 55.5. It was 50.2 last week.

  • NDR Daily Trading Sentiment Composite: Neutral Sentiment (S/T Neutral for Equities). Current daily sentiment reading is 42.22. It was 34.44 last week.


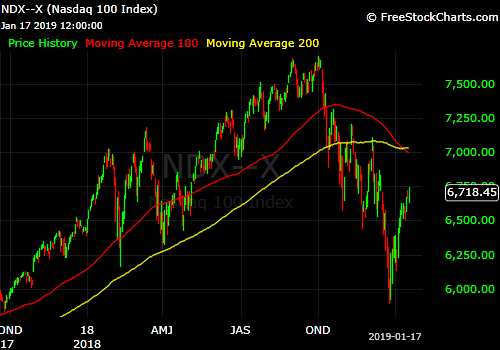
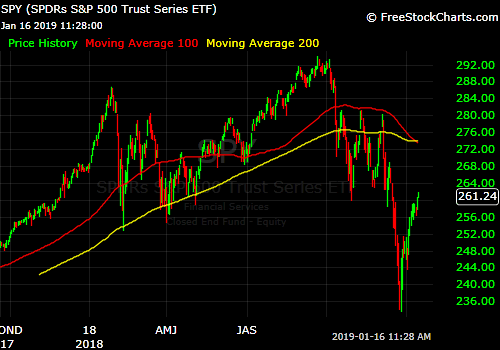
To ruminate this weekend: the SPY, W5000 and NDX all saw their 200-d m.a. tick up yesterday, but very, very slightly…
spy

w5000

ndxx

THE DAILY EDGE: 16 JANUARY 2019

Today’s retail sales data for December will not be available because of the government shutdown, but based on the Redbook same-store index, holiday sales were relatively healthy. (The Daily Shot)

Source: Pantheon Macroeconomics

U.S. Producer Prices Decline Led by Lower Energy Costs

The headline Final Demand Producer Price Index using new methodology fell 0.2% during December following a 0.1% uptick in November. A 0.1% decline had been expected in the Action Economics Forecast Survey. From December-to-December, the index rose 2.5%, the same as during 2017. Producer prices excluding food & energy eased 0.1% after a 0.3% increase. A 0.2% gain had been anticipated. For the year, the core PPI rose 2.7% after rising 2.2% in 2017. The PPI excluding food, beverages and trade services is another measure of underlying price inflation. It held steady last month (2.8% y/y) following a 0.3% increase. It’s 2017 rise was 2.3%.

The PPI using the old methodology fell 0.3% during December (+1.4% y/y) following a 0.8% November decline. Prices excluding food & energy improved 0.1% last month (2.5% y/y) after rising 0.3% in November. (…)

image

Core PPI rose 2.0% annualized in Q4 with a weak finish. Core Goods prices are up 1.6% a.r. in Q4, also with a weak finish.

image

Empire State Manufacturing Activity Weakens Sharply

The Empire State Manufacturing Index of General Business Conditions declined to 3.9 in January, the lowest level since May 2017. The Action Economics Forecast Survey expected a reading of 12.0 for January. Data back through 2017 were revised. The Empire State data, reported by the Federal Reserve Bank of New York, reflect business conditions in New York, northern New Jersey and southern Connecticut.

Haver Analytics calculates a seasonally adjusted index that is comparable to the ISM series. The calculated figure fell sharply to 51.9 from 56.2. It was the lowest level in two years. During the last ten years, the index has had a 66% correlation with the quarter-to-quarter change in real GDP.

Deterioration in the component series was broad-based last month and led by much lower orders, delivery times and inventories indexes. The shipments and unfilled orders indexes also fell sharply.

The employment index fell significantly during January after showing strong hiring in December. A lessened 15% of respondents reported increased employment, while a steady eight percent showed a decrease. The series dates back to 2001. During the last ten years, there has been a 77% correlation between the employment index and the month-to-month change in factory sector payrolls. The employee workweek reading was little changed.

The prices paid index weakened to the lowest level since December 2017. Forty-one percent of respondents indicated increased prices this month, while a higher six percent reported a decrease. Prices received held steady at the lowest level since December 2017.

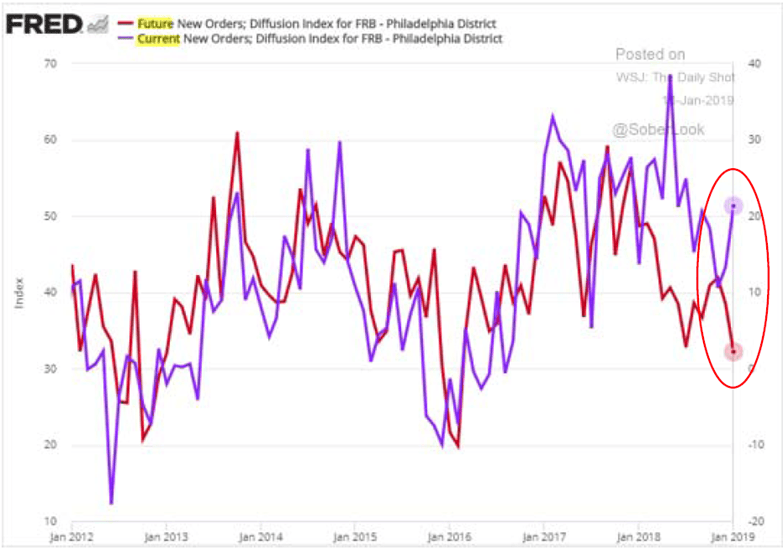
The series measuring expectations for business conditions in six months fell sharply to the lowest level in nearly three years due to declines in most categories.

 large image large image

Banks Flash Warning on Economy The latest signs of weakness in the U.S. economy come from big banks JPMorgan Chase and Wells Fargo

(…) JPMorgan reported growth of 1% from a year earlier in commercial and industrial loans, down from 4% in the prior quarter, which Chief Financial Officer Marianne Lake said was partly because the bank had pulled back from lending in particular areas and partly because of a general slowdown in the economy.

The bank also increased loan-loss reserves in its commercial-banking book moderately. On a conference call, Ms. Lake characterized the reserve build as being in “a handful of names in a handful of sectors, nothing that points to a systematic deterioration in a particular sector.” (…)

Meanwhile, at Wells Fargo there was a 5% jump in commercial and industrial loans, which was an encouraging sign after relatively weak momentum in this business for the past few quarters. But total loans outstanding at the end of the year were still down slightly from a year earlier. Notably for the biggest mortgage lender in the country, mortgage originations fell by 28% from a year earlier, the latest signal of weakness in the U.S. housing sector.

High five Fact is that bank lending has been pretty good lately. It’s off a weak base but Q4 lending is up 8.0% YoY and December up 9.7%.

image

BTW: JPMorgan CEO James Dimon said on a conference call with reporters that if the government shutdown lasts through the first three months of 2019, that could send U.S. economic growth to zero. (…)

Source: @GregDaco, @OxfordEconomics (via The Daily Shot)

(…) In addition to those 800,000 workers, a much larger number of government contractors is going without pay. The shutdown is reducing payments to contractors by about $245 million a day, or about 0.4 percent of daily gross domestic product. Some estimates put the number of workers who will be affected at more than 4 million — and unlike government employees, contractors won’t receive backpay once the shutdown ends.

Together, those 4 million contractors and the 800,000 furloughed employees constitute about 3 percent of the country’s labor force. That number is heading into territory that could have macroeconomic implications — for comparison, the increase in unemployment in the typical recession is usually about 2 percent to 4 percent. Furloughed workers and unpaid contractors are not quite the same as unemployment, but the macroeconomic spillovers might be comparable. (…)

Companies might delay investment due to regulatory disruptions — already there are ominous signs. Thanks to the lack of government workers to grant regulatory approval, new products from aircraft to beer to trucks can’t be released. That uncertainty will almost certainly give companies pause about investing. If anxieties about the decline in demand due to the shutdown make companies even more reluctant to invest, the result could be that many businesses stampede for the exits. And since many businesses serve other businesses, a lack of investment could quickly ripple through the supply chain. A general slowdown in business activity would result, with the attendant layoffs, pay freezes and cuts — in other words, a recession. (…)

U.S. Home Sales Plunged in December, Price Growth at 6-Year Low Previously hot metropolitan areas are cooling fast.

The median home price rose to $289,800 in December, a gain of 1.2 percent, the slowest monthly pace since March 2012. Sales dropped by almost 11 percent, the biggest decline for any month since 2016, Redfin said. Previously hot metropolitan areas are cooling fast. Prices dropped 7.3 percent in San Jose, California. (…)

Redfin’s data, which covers many large metropolitan areas, represents closed sales. Buyers likely signed contracts in November for most December sales. While rates for 30-year mortgages peaked at 4.94 percent in November, climbing a percentage point since the start of 2018, they’ve since fallen to 4.45 percent.

Goldman Says Rich People Will Drag Down the U.S. Economy The stock market sell-off means they’ll be spending less.

(…) Lower equity prices could take half a percentage point off U.S. gross-domestic product growth in 2019, with overall tighter financial conditions restricting expansion by around 1 percentage point, Goldman economist Daan Struyven wrote in a note Tuesday. (…)

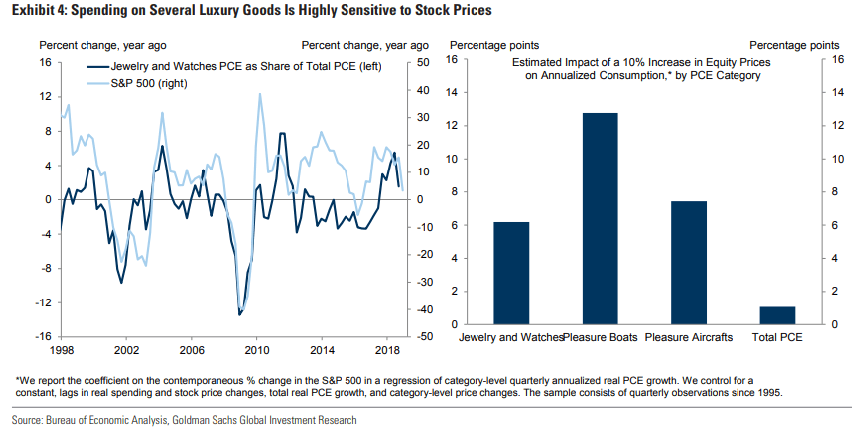
Struyven argued against the idea that the wealth effect from the stock market might be limited due to a higher concentration of stock ownership than in previous decades, and a lower propensity to spend among rich households. To prove that this thesis doesn’t hold up, he cited increases in equity holdings, as well as a high sensitivity of luxury-goods spending to stock-market fortunes, as evidence.

That’s at odds with a paper from the National Bureau of Economic Research in 2013 that finds “at best weak evidence of a link between stock-market wealth and consumption,” and asserts that the housing market has much more of a wealth effect.

The share of personal consumption expenditures spent on jewelry is “highly correlated with moves in the stock market,” Struyven wrote in the Jan. 15 report. (…)

image

China injects record $84bn to boost economy Central bank acts on growth fears and higher lunar new year cash demand

(…) The finance ministry also issued new quotas for local government bond sales earlier than normal this year to ensure that infrastructure projects are adequately funded.  A senior finance ministry official on Tuesday provided details on new tax cuts designed to support small businesses, manufacturers and exporters.

Trade War Tops Global Risks for Business Leaders

(…) “We simply do not have the gunpowder to deal with the kind of slowdown that current dynamics might lead us towards,” said Børge Brende, president of the World Economic Forum.

Economic policy, once a way for rivals to mutually benefit in trading relationships, is now “frequently seen as a tool of strategic competition,” the report said. (…)

“The biggest risk is the lack of willingness to collaborate—we are not mitigating that risk,” the group’s chief said. (…)

EARNINGS WATCH
Earnings: First, the Good News Corporate results are likely to be a lot better than analysts expect in the fourth quarter

(…) For one thing, despite Apple, earnings warnings have been muted. By Refinitiv’s count, the ratio of companies with negative earnings pre-announcements to those with positive pre-announcements is 1.5—well below the long-term average of 2.8. In the third quarter, the negative-to-positive ratio was 1.4, and eventual earnings growth ended up at 28.4%, versus the 21.6% analysts expected at quarter end.

Another plus: Among the admittedly small number of companies that already have reported results, some 85.2% have topped estimates. That compares with 64.5% historically and 78% over the past four very strong quarters. (…)

The first quarter could be a different matter, though. The effects of the government shutdown and ongoing trade disputes are expected to weigh on the economy and the boost to earnings growth from the tax cut is going away.

While they are unveiling good numbers, companies will be discussing all this on their earnings calls—so don’t relax too much.

It’s been a while I had not seen a positive spin on earnings. The most recent facts:

As of yesterday, we have had 27 earnings reports boasting an 85% beat rate. Financials are 50% with only 4 reports in but the two misses were enough to bring the surprise factor down from +3.3% to zero.

Q4 earnings are seen up 14.0%, down from 15.8% on Jan. 1.

Trailing EPS are now $162.05, slightly above the full year estimate of $161.65.

Q1’19 earnings are now seen up 3.3%, down from 5.3% on Jan. 1 while Q2’19 earnings are expected up 5.1% (6.5%).

U.S. middle-market private companies enjoyed the strongest earnings growth in years, propelled by high demand for products and services, according to a report released Friday by Golub Capital, a lender to these firms.

Closely held smaller companies reported that earnings rose 13.4% in the first two months of the fourth quarter compared with the same period in 2017, the fastest such increase since at least 2012. Revenue rose by 10.6% during the first two months of the fourth quarter, the report said.

“Unless you are a business that’s driven by commodity prices, you are doing great,” said Lawrence Golub, chief executive of Golub Capital. “There is a lot of momentum going to 2019; it looks as if nothing could derail that.” (…)

Some sectors analyzed by Golub Capital, such as manufacturers, feel the pressure of higher steel prices. “We see margin compression in the industrial sector,” Mr. Golub said. “This sector is most sensitive to cost increases coming from trade issues.”

The report is based on the Golub Capital Altman Index, which assesses the median revenue and earnings growth of more than 150 closely held companies across the U.S. that Golub Capital lends to. The index, which was created in 2012, focuses on financial performance during the first two months of each quarter and measures earnings before interest, tax, depreciation and amortization. (…)