The enemy of knowledge is not ignorance, it’s the illusion of knowledge (Stephen Hawking)

It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so (Mark Twain)

Invest with smart knowledge and objective odds

THE DAILY EDGE: 10 DECEMBER 2021: CPI, DPI

CPI for all items rises 0.8% in November; gas, food, shelter, vehicle indexes all rise

The Consumer Price Index for All Urban Consumers (CPI-U) increased 0.8 percent in November on a seasonally adjusted basis after rising 0.9 percent in October, the U.S. Bureau of Labor Statistics reported today. Over the last 12 months, the all items index increased 6.8 percent before seasonal adjustment.

The monthly all items seasonally adjusted increase was the result of broad increases in most component indexes, similar to last month. The indexes for gasoline, shelter, food, used cars and trucks, and new vehicles were among the larger contributors. The energy index rose 3.5 percent in November as the gasoline index increased 6.1 percent and the other major energy component indexes also rose. The food index increased 0.7 percent as the index for food at home rose 0.8 percent.

The index for all items less food and energy rose 0.5 percent in November following a 0.6-percent increase in October. Along with shelter, used cars and trucks, and new vehicles, the indexes for household furnishings and operations, apparel, and airline fares were among those that increased. The indexes for motor vehicle insurance, recreation, and communication all declined in November.

The all items index rose 6.8 percent for the 12 months ending October, the largest 12-month increase since the period ending June 1982. The index for all items less food and energy rose 4.9 percent over the last 12 months, while the energy index rose 33.3 percent over the last year, and the food index increased 6.1 percent. These changes are the largest 12-month increases in at least 13 years in the respective series.

Adobe Digital Price Index: Online Inflation Hits Record High Online prices increased 3.5% year-over-year

Adobe (Nasdaq:ADBE) today announced the latest online inflation data for the month of November 2021. Online prices hit a record high at a 3.5% year-over-year (YoY) increase while prices are down 2% month-over-month (MoM) due to holiday discounts. This is the highest YoY increase since Adobe first began tracking the digital economy in 2014, and it marks the 18th consecutive month of YoY online inflation.

Apparel was a standout category with prices up 17.3% YoY and down just 0.4% MoM, reaching a record high of inflation. One dollar out of every four dollars* is now spent online in the U.S., making the digital economy a significant component of the overall economy.

The [Digital Price Index] DPI covers more than 100 million products in the U.S. and is modeled after the Consumer Price Index issued by the U.S. Bureau of Labor Statistics.

  • Yesterday, I received this email from my friendly AC company: “We received a notice from all the national dealers including, Carrier, Trane, Rheem, Lennox, etc., of another price increase of 10% for all Air Conditioning equipment effective January 3rd, 2022.”
Wage Growth Tracker Was 4.3 Percent in October The Atlanta Fed’s Wage Growth Tracker was 4.3 percent in November, up from 4.1 percent in October and the highest reading since 2007. The Tracker for people switching jobs was 5.2 percent in November, up from 5.1 percent in October.

atlanta-fed_wage-growth-tracker (3)

(…) In the three separate store elections overseen by the National Labor Relations Board on Thursday, the federal body said that one store voted for unionizing, one voted against it and results in the third weren’t conclusive. The labor board said it will review challenges from both sides in that store election. (…)

The union drive has preoccupied Starbucks executives for months, and captured the attention of chain workers beyond Buffalo. One Starbucks store in Mesa, Ariz., last month petitioned to unionize, with supportive baristas working with the same Workers United union and saying they drew inspiration from the Buffalo effort.

A NLRB hearing on three additional Buffalo stores that also petitioned to unionize is slated to begin Friday. (…)

Unions are rare in U.S. restaurants. Less than 2% of food-service and bar workers were union members as of last year, according to the Labor Department.

More than half of Starbucks’s 6,500 U.S. airport, grocery, casino and other licensed locations are unionized, according to the company. A Buffalo union would represent the first for a location owned by Starbucks; the company owns 9,000 of its roughly 15,500 U.S. cafes. (…)

Starbucks in October announced wage increases, saying that the average U.S. barista’s pay would rise by next summer to nearly $17 an hour from $14. (…)

The safety net!?

$35tn wealth surge provides solid platform for US growth

Non-financial assets – primarily real estate, but also including things such as cars, jewellery and equipment – now totals $48.6tn versus $40tn at the end of 2019. Meanwhile, financial assets total $114tn, up from $93.4tn in 2019 – an astonishing 22% increase in 21 months.

Within financial assets the largest categories are corporate equities & mutual funds ($42.6tn) pension and life funds ($32.9tn), small business equity ($14.4tn), and time and savings deposits ($10.7tn).

unnamed - 2021-12-09T184911.763

Household Liabilities are “just” $18tn and are primarily mortgage and consumer loans, which leaves household net worth at $144.7tn. This is equivalent to 624% of US GDP and 796% of annual disposable income. As the chart below shows, the household balance sheet, in aggregate, has never been in such a strong position.

The household balance sheet measured as a % of household disposable incomeunnamed - 2021-12-09T184954.857

It is certain that the majority of the increases in wealth will have been experienced by higher income and already wealthy households since they will have been heavily invested in the “winning” asset classes. The biggest contribution to the financial wealth gains came from corporate equities and mutual funds due primarily to risk appetite rebounding and equity markets surging higher on unprecedented Federal Reserve and government stimulus. The same reasons led to strong performances for pension and life insurance funds. Conversely, the value of debt security holdings has actually declined as low yields prompted investors to sell.

Moreover, higher income and wealthier households spend proportionally more on services and “experiences” such as travel, eating out, theatre and the cinema – things that Covid containment measures have prevented. Consequently, we are likely to have seen a significant increase in unplanned saving amongst this grouping with the money instead put into various financial and physical assets.

There was also a substantial increase in wealth within cash, checking and savings deposits. Given such low interest rates being paid on balances we can safely say this was overwhelmingly due to people putting more and more money into these accounts – up $3tn since 1Q20 and up $3.4tn since 4Q19!

Lower income households will also have benefited to some extent with government stimulus cheques of $1200, $600 and $1400 combined with uprated and extended unemployment benefits contributing to significant increases in household incomes over the past 18 months. This can be seen in the chart below with the orange bars representing the income boost from the cheques and the grey bars representing the expanded unemployment benefits.

An NBER paper calculated that 69% of unemployment benefit recipients actually earned more money being unemployed than when they were working. The median recipient received 134% of their previous after-tax compensation. Encouragingly, we are now seeing positive income growth from higher wages and salaries and this will hopefully mean that incomes can keep rising despite the curtailment of additional unemployment benefits.

Contributions to the change in personal income levels versus February 2020 ($tn)unnamed - 2021-12-09T185251.811

With employment growth looking resilient and higher income growth becoming increasingly evident as firms compete for staff, the outlook for consumer spending remains positive. Today’s evidence of further massive accumulation of wealth only adds to the potential spending ammunition of the household sector, which gives us more confidence that the US economy can expand by more than 4% in 2022.

October and November were strong retail months. The more recent weeks have been slower:

image

(…) Comparable sales, those from stores and digital channels operating for at least 12 months, rose 9.8% in the quarter ended Nov. 21 compared with the same period last year, excluding gas sales and currency fluctuations. E-commerce sales rose 13.3% during the quarter. (…) For the latest quarter the company estimates that overall year-over-year price inflation was in the 4.5% to 5% range. (…)

In late October, Costco raised its starting wage for workers to $17 an hour, eating into profit, Mr. Galanti said. (…)

Net income hit $1.3 billion in the most recent quarter, up from $1.2 billion in the same period last year. Analysts expected net income of $1.2 billion, according to FactSet. (…)

About 79% of Costco’s imports are late by an average of 51 days, Chief Financial Officer Richard Galanti said on a call Thursday. “Virtually, all departments are impacted. We’ve ordered early in many cases,” he said. (…)

Costco management now anticipates overall price inflation in the 4.5-5.0% range (ex-gas) vs
3.5-4.5% in September and 2.5-3.5% in May. The company said that supply chain pressures have remained relatively stable to the previous quarter with ~79%
of import containers arriving late by 51 days on average.

Bank of Canada Highlights Concerns Over Supply Chain, Inflation Risks The Bank of Canada on Thursday signaled its growing discomfort with high inflation and the possibility that supply chain disruptions could last longer than policy makers had anticipated.

(…) Mr. Gravelle’s comments on Thursday were “notably more hawkish than Wednesday’s policy statement,” Andrew Kelvin, chief Canada strategist with Toronto-Dominion Bank, wrote in a note to clients. (…)

[Mr. Gravelle] acknowledged, however, that the economic models the bank relies on for forecasting are having a hard time dealing with a global shock to supply and demand.

“Given that there is no historical precedent to the sudden closing and reopening of the economy, our models were not built to capture the many economic forces that arose from the pandemic,” he said.

Supply strains are peaking…but have yet to decline:unnamed - 2021-12-10T075018.779

Musk, Other Insiders Are Selling Stock at Historic Levels Top executives and company leaders like the Waltons, Mark Zuckerberg and Google’s co-founders have sold $63.5 billion through November, up 50% from 2020. The sales come amid soaring market valuations and ahead of possible changes in U.S. and some state tax laws.

(…) So far this year, 48 top executives have collected more than $200 million each from stock sales, nearly four times the average number of insiders from 2016 through 2020. In November, insiders unloaded a collective $15.59 billion. (…)

Corporate insiders, particularly those in high P/E tech stocks, are increasing liquidity just before the Fed starts reducing liquidity in markets as Nordea suggests:

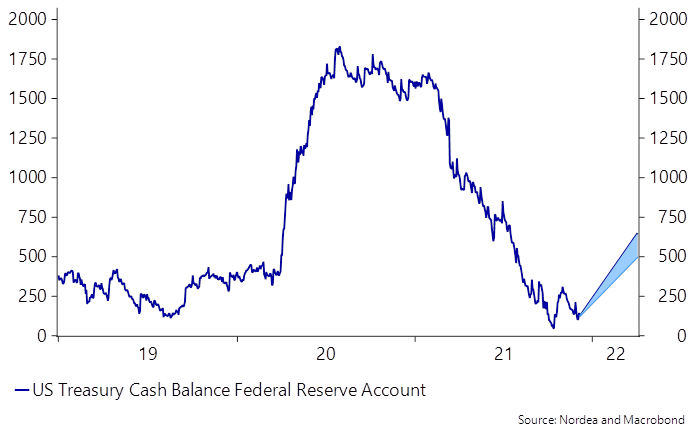
The quicker tapering and lifting of the debt ceiling will mean less liquidity to the street. The latest release from the Treasury indicates a cash balance at USD 650bn as of end-March, which from current levels implies a drain of some USD 550bn from private sector liquidity, in turn resulting in USD liquidity becoming more expensive. The rise of US STIRs has come fast, but are coming at the expense of a quicker policy reversal priced into the market.

New US Treasury cash balance scenario
x

Europe Sees Early Signs Latest Virus Surge Is Leveling Off

While the trend varies across countries, overall European Union numbers look to have hit a plateau. Austria and Germany have seen a dramatic shift, with the former’s seven-day case rate plunging by more than half since late last month. (…)

The spread also appears to be slowing in the Netherlands, which was another Western European hotspot last month. But cases are still rising sharply in some countries, including Switzerland, where the spread of infections is at a record high.

There’s also the big unknown of the new omicron variant, which looks to be more transmissable than the delta mutation. Germany and other countries are pushing hard to deliver booster shots after some initial research suggested lower protection in people who received just two shots. (…)

Austria is ending a three-week lockdown on Sunday but keeping restrictions on those who haven’t been inoculated. And in a controversial move, it’s also bringing in mandatory vaccinations as the continent gradually toughens its stance. (…)

In the USA:

(CalculatedRisk)

The holidays with my family (Katelyn Jetelina) I can share my plans, what I’m thinking for my little family, and where the risks lie and don’t lie. Maybe it will help. Maybe not. Maybe I will regret this, but ‘tis the season.

THE DAILY EDGE: 9 DECEMBER 2021: Inflation, Productivity, Rates

U.S. JOLTS: Job Openings Rate Improves in October

The Bureau of Labor Statistics reported that on the last business day of October, the total job openings rate rose to 6.9% from 6.7% in September, revised from 6.6%. The rate hit a record 7.0% in July of this year. The job openings rate is calculated as job openings as a percent of total employment plus jobs that have not yet been filled.

The level of job openings surged 4.1% (60.5% y/y) to 11.033 million from 10.602 million in September.

The level of hiring fell 1.3% (+7.1% y/y) as the hiring rate held steady at 4.4%. The rate remained well above the 3.8% low this past January. The overall layoff & discharge rate remained at the record low of 0.9% for the third straight month. The quits rate eased to 2.8% from the record 3.0% in September and compared to the most recent low of 1.6% in April 2020. The level of quits rose 24.0% y/y to 4.157 million. The JOLTS figures date back to December 2000.

The private-sector job openings rate returned to the record 7.4% after falling to 7.1% in September. It has improved from a 3.6% low in April 2020. The highest rates were in leisure & hospitality (10.3%) and professional & business services (7.9%). The government sector job openings rate fell to an elevated 4.0% from 4.3%. The level of private sector job openings rose 5.2% to 10.118 million, up nearly two-thirds y/y. The number of government job openings fell 7.5% (+30.6% y/y).

The private sector hiring rate fell to 4.8% in October, the lowest rate since May. A hiring rate of 8.0% in leisure & hospitality accompanied a 5.0% rate in construction. In the government sector, the hiring rate was 1.7%. The level of private sector hiring declined 1.7% in October (+7.1% y/y) to 6.10 million. The government sector jobs level rose 7.1% (7.4% y/y) in October.

fredgraph - 2021-12-09T083512.718

This Inflation Defies the Old Models Neither supply or demand by itself is increasing prices; it’s an unusual combination of both

(…) this inflation was made possible only by strong demand interacting with restricted supply. The U.S. hasn’t seen anything like this combination except, perhaps, in the aftermath of World War II. Then, Mr. Biden’s Council of Economic Advisers has noted, pent up demand coincided with war-induced shortages. This makes the solution elusive: fixing supply is largely beyond the means of the White House and Fed, but treating the problem as one of only demand could damage the economy. (…)

Many economists note the boost to inflation is concentrated in goods. That’s because the pandemic diverted consumer spending away from services such as restaurant meals toward goods such as groceries. Nonetheless, the unusual dynamics are spreading to services as well. (…)

The unusual origins of this inflation mean the solution isn’t straightforward. Ideally it will recede painlessly as distortions to demand and supply self-correct. Rising semiconductor output will eventually cure the shortage of cars. A receding virus and less generous federal relief should coax some workers to fill job vacancies. Households may have all the furniture, exercise equipment and pizza they want.

But that process could take a while; meanwhile, higher inflation could become self-perpetuating through price and wage-setting behavior. Then, the solution to this unfamiliar inflation becomes painfully familiar: higher interest rates and perhaps a recession.

John Authers: Markets Overestimate a ‘Powell Pivot’ at Their Peril This isn’t 2018, when inflation wasn’t even a worry. The central bank can’t afford to back off meaningful rate hikes this time.

(…) On the Fed’s greater haste, the Bloomberg analysis of the probabilities implied by fed funds futures show how expectations have shifted in the last two months. As recently as November, there was seen to be minimal chance of a rate hike before June. Now, the chance of a hike at May’s meeting is well over one in two, and there is one-in-three chance of a rise as early as March (…).

But longer-term yields have fallen, significantly, despite ongoing elevated inflation forecasts. (…)

So the implicit expectation is that by moving more quickly and aggressively, the Fed will save itself from having to hike too far and make rates so expensive that they slow down the economy. Hence, many are now braced for a Fed announcement next week that it will accelerate its taper — probably even double the amount that it cuts back asset purchases each week, and be finished as early as March, rather than the more relaxed schedule taking until June.

Something along these lines wouldn’t have too great a market impact. But how safe is the assumption that the Fed won’t be hiking long into the future? (…)

To put this in historical perspective, over the four decades since price rises peaked under Paul Volcker, inflation has quite often exceeded the fed funds rate (meaning that the real fed funds rate is negative), but all hiking cycles have ended with the fed funds rate above inflation. (…)

With inflation proving a tougher nut to crack than in decades, this further argues for pushing up real rates well into positive territory. Such an outcome is not reflected by present market calculations.

(…) most of the FOMC don’t think rates will go beyond 1.8% by the end of 2024. That’s higher than the market implicitly expects, but gives some comfort that the Fed doesn’t think it will need to keep piling on pain until rates exceed inflation. (…)

[William Dudley, former governor of the New York Fed,] adds that the market estimate of a 1.5% highest rate is “well below what common sense would dictate.” (…)

The Fed is arguably a long way behind the curve. The U.S. recovery has hummed along far more impressively than in Europe or Asia, and yet the stimulus that the economy has received is far greater. If we take broad “M2” money as a yardstick for the amount of liquidity in the economy, it’s clear that the Fed has trodden on the accelerator for much longer than other central banks. (…)

This suggests that the Fed may well have to do far more work to slow things down than other central banks. It might also imply that the strength of the American recovery owes a lot to the Fed’s exceptional generosity. (…)

While the Fed has only just embarked on tapering, the other four big central banks have already cut back very significantly on asset purchases:

relates to Markets Overestimate a ‘Powell Pivot’ at Their Peril

All this suggests that the Fed will need to work very hard to rein in liquidity and calm inflation down once more. So why would markets expect Jerome Powell and his colleagues to relent early? The most popular case is that they will be forced into a “Powell pivot” and step back if they find themselves triggering a fall in the stock market, or a sharp economic downturn. This blueprint is taken from what happened in late 2018. But it ignores the fact that there is plenty of room for assets to fall from the current dizzy levels, and that inflation is now a very serious problem while it wasn’t even an issue three years ago. If the Fed loses its nerve, we could expect a fall for the dollar, which would worsen inflation. In very strong language, Howell argues the following:

Some policy catch-up looks inevitable, but, like in the 1970s, we believe the current Fed lacks the necessary fortitude to tackle the inflation problem. Consequently, inflation will persist, with the US dollar potentially in the firing-line. We recognise that Chair Powell is probably not a Paul Volcker on
inflation, but we also worry that President Biden is a Jimmy Carter for the dollar.

That might be taking things a little too far. But the risks are serious enough, and plenty of people are warning about them. There is a very real chance that Powell will soon have to get everyone ready for fed funds rates to keep rising until they are comfortably above the rate of inflation. That will not be popular.

Fiera Capital’s strategists last week boosted their 12-18 months expectations for inflation from 3.5% to 4.5% in their Stagflation scenario (40% probability). Their reflationary recovery scenario (50%) has inflation at 4.0%.

They also boosted their short-term rates forecast by 50 bps, targeting 1.75% in their stagflation scenario. Their U.S. equity outlook is strongly negative under all scenarios after having been very bullish for many years.

But what about productivity gains many expect to keep inflation low enough. The Employment Cost Index shot up 3.7% YoY in Q3 and Unit Labor Costs are now rising in the 4-6% range.

fredgraph - 2021-12-09T080814.301

Richard Bernstein yesterday tweeted: “Technology improves productivity and fights inflation” is total bunk. Current quarter #productivity among worst in history and #trend productivity virtually unchanged in 70 years.

Image

China’s Factory-Gate Inflation Softens in November China’s factory-gate inflation ebbed in November after hitting a 26-year high, which economists say will give policy makers more room for easing to bolster a slowing economy.

The producer-price index rose 12.9% from a year earlier in November, down from 13.5% growth in October, which was the fastest increase since 1995, according to data released by the National Bureau of Statistics. (…)

Meanwhile, China’s consumer-price index rose 2.3% from a year ago in November, accelerating from October’s 1.5% increase, and rose above 2% for the first time in more than a year.

The rise in consumer inflation was mainly driven by food prices, which increased 1.6% year over year in November, after falling 2.4% in October, the statistics bureau said. (…)

U.S. Light Vehicle Sales Remain Firm in November

Firm?

The Autodata Corporation reported that light vehicle sales during November of 13.12 million units (SAAR) were unchanged (-18.4% y/y) versus October. Despite the m/m stability, sales were 29.1% below the April peak of 18.50 million units.

Trucks’ share of the light vehicle market eased to 79.5% last month from 80.3% in October. That share has improved from a low of 48.1% during all of 2009.

Passenger car sales rose 3.5% (-31.3% y/y) in November to 2.68 million units after a 2.3% October decline. Purchases of domestically-produced cars rose 11.2% last month (-32.0% y/y) to 1.89 million units after a 3.0% October gain. Down for the sixth straight month, sales of imported autos weakened 11.2% in November (-29.5% y/y) to 0.79 million units following an 11.9% October drop.

Sales of light trucks eased 0.9% (-14.3% y/y) in November to 10.43 million units after rising 8.3% in October. Purchases of domestically-made light trucks fell 1.8% in November (-13.9% y/y) to 8.08 million units. Offsetting this decline, sales of imported light trucks rose 2.2% last month (-15.8% y/y) to 2.35 million unit but remained 28.8% below April’s record 3.30 million units.

Imports’ share of the U.S. vehicle market fell last month to 23.9%, the lowest percentage since January. It had risen to a September high of 27.9% from 19.9% in 2015. Imports’ share of the passenger car market declined to 29.5% from 34.4% in October. Imports’ share of the light truck market edged higher to 22.5% after plummeting to 21.8% in October. These figures were down from 25.2% in September.

fredgraph - 2021-12-09T083833.422

Bank of Canada Leaves Key Interest Rate Unchanged at 0.25%

ING:

The Bank of Canada left monetary policy unchanged today, but the accompanying statement confirmed expectations that 2022 will see the central bank raise interest rates in response to strong growth, record employment and elevated inflation. The forward guidance remains that the timing of the first hike will come “in the middle quarters of 2022”, but we see the possibility of a first move in March with three further moves in each of the subsequent quarters.

The central bank is forecasting GDP growth of 4% in 2022 and 3.75% in 2023 on the back of strong consumer demand, business investment and a recovery in exports to the US. High prices are also going to be supportive for activity in the natural resource sector of the economy, which accounts for 10% of economic activity. (…)

Canada employment is above pre-Covid levels, outperforming the US (millions)

unnamed - 2021-12-09T084015.541

Source: Macrobond, ING

After all, employment is already above its pre-pandemic peak with November’s 153,700 jump meaning there are now 185,800 more people in work than there were in February 2020. Job vacancies are also at record highs, suggesting employment growth will remain robust. With incomes rising and household savings built up through the pandemic providing an additional resource to fund expenditure we see demand continuing to run hot through next year.

This is likely to mean inflation imminently breaks above 5% and stays there throughout the first quarter. However, the BoC have only slightly tweaked their inflation assessment from inflation being likely to “ease back to around the 2% target by late 2022” to “ease back towards 2%”. We are more wary that supply chain strains and labour shortages could keep inflation more elevated for longer.

With the BoC having pointed to the prospect of earlier rate hikes and abruptly ending QE at the October policy meeting we changed our own forecast to four 25bp rate hikes in 2022 – one in each quarter. The emergence of the Omicron variant is a cause for concern, but the tone of the BoC statement suggests that even if it does lead to some consumer caution the case for policy tightening remains strong. As such, we see no reason to change our four-hike view for 2022.

The Canadian dollar was trading marginally weaker after the rate announcement, but the impact is proving very contained and short-lived given the lack of surprises in the statement. Some of the recent CAD strength is likely being fuelled by the notion that the BoC is ready to respond to inflation pressures with tightening, assuming the global picture does not significantly worsen. We think today’s statement did very little to dent this notion, allowing CAD to continue benefiting from the rebound in global sentiment.

We think USD/CAD may extend its decline to 1.2500 by the end of the year, although that is heavily reliant on further improvements in the Omicron-related sentiment. 

Market Can Weather Evergrande Crisis, China’s Central Banker Says People’s Bank of China Gov. Yi Gang said the central bank was committed to a level playing field for investors and that broader problems with debt at Chinese property developers should be dealt with according to market principles.

Financial stress at China Evergrande Group EGRNF -7.13% and a few of its peers won’t cause longer-term damage to the Hong Kong market, and broader problems with debt at Chinese property developers should be dealt with according to market principles, China’s top central banker said. (…)

Mr. Yi added that the Chinese central bank was committed to a level playing field for investors. “Companies issuing bonds overseas and their shareholders will be urged to properly handle their debt issues and meet their debt obligation in accordance with law and market principles,” he said. “This is a market event. It should be handled in the market-oriented way, based on law.”

“The rights and the interest of creditors and shareholders will be fully respected, in accordance with their legal seniorities,” the central banker said. (…)

(…) In China, supply chain asset-backed securities are created by bundling together developers’ payment obligations to their suppliers, which include sellers of building materials and contractors. Large property firms such as China Vanke Co. , Kaisa Group Holdings Ltd. and Evergrande often have hundreds of small suppliers.

In essence, property developers get suppliers to sell their account receivables—the right to collect money from the developers—to factoring companies. A factoring company gives suppliers cash upfront, typically paying them amounts that are less than what the developer owes them. Small suppliers often have little choice but to accept the payment terms.

In a typical supply-chain securitization, a factoring company bundles the suppliers’ receivables into securities that are sold to investors in China. The transaction is initiated by a developer, and the cash raised from the bond sale helps the factoring company buy the supplier receivables. When the developer pays its bills, that money goes to holders of the bonds. (…)

Real-estate developers, however, can only use the deals to refinance existing debts, the bankers added. (…)

In effect preventing a supplier crisis.

Beijing Reins In China’s Central Bank The PBOC was never independent but it has tried to establish good communication with markets. Xi Jinping’s financial shake-up is changing that.

(…) In recent weeks, Communist Party discipline inspectors from China’s top anticorruption agency have visited the central bank’s headquarters in central Beijing. Officials briefed on the matter said the inspectors asked questions, reviewed documents and brought an unusually stern message: Beijing has little tolerance for any talk of central-bank independence; the monetary authority, just like any other part of the government, answers to the party. (…)

China’s leadership has come under pressure to tamp down turmoil in the property sector, which is now threatening to severely cut into services and manufacturing activities. A senior economic adviser to Chinese leaders said China’s much slower-than-expected economic expansion in the third quarter, at 4.9%, led top leaders to decide to bolster support for the economy despite the central bank’s preference to maintain a more conservative policy stance. (…)

In an article posted on the discipline commission’s website last month, Xu Jia’ai, head inspector of the PBOC, said his team of inspectors had given party lectures across the central bank to strengthen the party’s leadership at the bank.

“In the past period, the foundation for comprehensive and strict governance of the party in the financial sector was weak,” Mr. Xu said, “and the tendency of financial ‘specialism’ and the central bank ‘exceptionalism’ was prominent.”

The message, said some who attended the lectures, was that whatever macro-policy discipline the central bank tries to maintain would be secondary to the need to deliver what the party leadership asks.

Amazon Fined $1.3 Billion in Italian Antitrust Case Italy’s antitrust regulator said Amazon harmed competitors by favoring third-party sellers that use its logistics services, ramping up scrutiny of tech giants by antitrust regulators globally.
Covid Spurs Biggest Rise in Life-Insurance Payouts in a Century Death-benefit payments rose 15.4% in 2020 to $90.43 billion, mostly due to the pandemic, according to the American Council of Life Insurers. It’s the sharpest rise since 1918.