The enemy of knowledge is not ignorance, it’s the illusion of knowledge (Stephen Hawking)

It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so (Mark Twain)

Invest with smart knowledge and objective odds

THE DAILY EDGE: 11 NOVEMBER 2021: Broadflation!

Inflation Pickup Makes Fed More Likely to Raise Rates Next Year Consumer prices are rising at their strongest 12-month pace in three decades

The Labor Department reported Wednesday that consumer prices rose strongly in October, up 0.9% on a seasonally adjusted basis from the prior month. Over the last 12 months, inflation is up 6.2%. So-called core prices, which exclude food and energy items, rose 4.6% over the past year. Both are the largest annual increases in more than 30 years. (…)

The rise in core prices over the past year is in line with unit labor costs, a key measure of compensation for U.S. workers, which rose 4.8% in the third quarter from a year earlier.

(…) data suggest price pressures are broadening to a wider range of goods and services as rising shipping and commodities costs feed through the economy. (…)

U.S. bond market expectations for inflation ticked up after Wednesday’s report, as did prices in futures markets indicating the Fed would raise rates at its meeting next June.

St. Louis Fed President Jim Bullard said on Tuesday he was worried an “inflationary process” had started over the last six months. “There’s a case to be made that inflation is going to be mostly transitory and dissipate, but you can only put so much probability on that scenario,” he said. (…)

More data:

  • October’s core CPI was up 0.6% MoM, +7.3% a.r.. Coming after +0.10% and +0.24%, the slowdown thesis has been put aside.
  • Core Goods inflation jumped 1.0% last month after +0.3% and +0.2%. Last 3 months: +6.1% a.r..
  • Core Services: +0.4% after +0.0% and +0.2%. Last 3 months: 2.4% a.r. but a disturbing trend. Rising wages being passed on?
  • Shelter: +0.5% after +0.2% and +0.4%. Last 3 months: 4.5% a.r..

fredgraph - 2021-11-11T064921.090

Now look at the essentials of life:

  • Food-at-Home: +5.4% YoY but +10.8% a.r. in the last 3 months. Energy: +30.0% YoY. Rent of primary residence: +2.7% YoY but +4.9% a.r. in the last 3 months.

Now, forget these essentials:

  • All items less food, shelter, and energy: +5.3% YoY, +3.6% a.r. in the last 3 months.
    • All items less food, shelter, energy, and used
      cars and trucks: +4.0% YoY, +4.0% a.r. in the last 3 months.
    • Goods less food, energy, and used
      cars and trucks: +5.5% YoY, +7.8% a.r. in the last 3 months.

Inflation is now here, there and everywhere. Deflating average hourly earnings, workers’ real take-home-pay still looks on trends…

image

…but that is because of the statistical compositional quirks during the pandemic. Using a composition-adjusted series, the average worker is now starting to feel the inflation pinch:

image

So far, there is no visible impact on nominal spending as the Chase spending tracker shows through Nov. 5.

image

image

US inflation again exceeded expectations by a wide margin. Headline and core rates are now at 30-year highs with near-term momentum suggesting 7% is possible. Pipeline price pressures show little sign of abating and inflation expectations are climbing as well, leading us to conclude QE tapering will be accelerated and rate hikes will come sooner. (…)

With the economy set to grow 6%+ annualised in this quarter and inflation set to persist at 6%+ through 1Q why does the Fed need to keep stimulating? The November FOMC statement said the committee “is prepared to adjust the pace of purchases if warranted by changes in the economic outlook” and if this backdrop doesn’t justify QE taper concluding early we are not sure what will. (…)

The Federal Reserve continues to assert that “longer term inflation expectations remain well anchored at 2 percent”, but consumer surveys suggest this is looking increasingly tenuous. The Federal Reserve’s own survey (conducted nationally by the NY Fed), shows 1Y ahead inflation consumer expectations rising to 5.7% – not really surprising as it tends to track actual inflation. However, the 3Y ahead inflation expectations rose to a new all-time high of 4.2%. We wouldn’t be surprised to see the University of Michigan 5-10Y ahead expectations break-up toward 3.5% in the next few months.

It is a similar story for market inflation expectations using Treasury index protected securities. They are now show 3%+ inflation out to 7 years maturity with even the 10Y up at 2.7%.

unnamed - 2021-11-10T103434.436

Year-Ahead Inflation Expectations (5)

Year-over-Year Unit Costs (4)

  • 58% of surveyed firms say their unit costs are “up significantly” or “up very significantly”, from 45% last July. The percentage “up very significantly” is 32%, from 17% last July.
  • “Projecting ahead over the next 12 months, how do you think the following five common influences will affect the prices of your products and/or services?”

Future Influence of Labor Costs on Prices (1)

Future Influence of Non-Labor Costs on Prices (1)

  • Most companies are protecting their margins raising prices. Higher productivity not specifically mentioned yet.
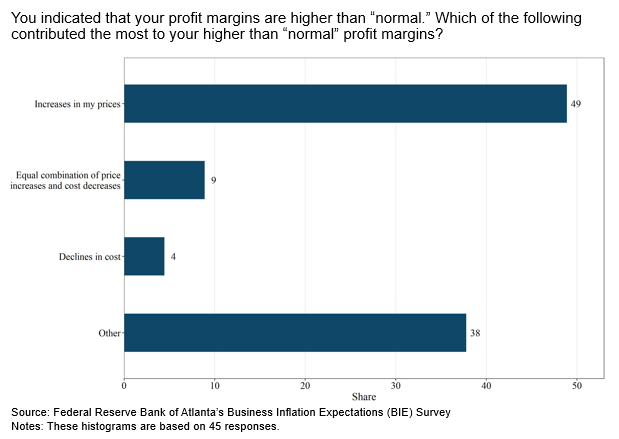
Business Inflation Expectations - November 2021 - Special Question Chart 1

  • Companies anticipate being able to keep raising prices in 2022:
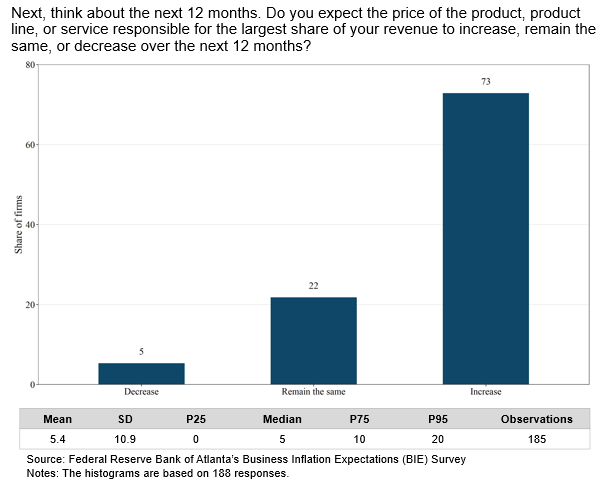
Business Inflation Expectations - November 2021 - Special Question Chart 4

According to the Bureau of Labor Statistics, private industry wages and salaries increased 6.5% annualized in Q3. That’s the fastest increase recorded in this wage series in nearly 30 years. The surge in labor costs should not be a surprise.

Big and small companies have been talking publicly for many months about labor shortages and the need to raise wages to keep staff and attract new workers. The pressure on labor costs is widespread but is most severe in services, the segment of the private sector workforce that accounts for 84% of all jobs. (…)

Even after boosting wages by the most significant amount in three decades, firms are telegraphing the need to do more to maintain and recruit staff. In other words, the labor shortage is not going away anytime soon. (…)

Powell is using the pre-pandemic jobless rate and employment levels as gauges to its full employment mandate. Yet, history shows that no two labor markets are alike. And, the precise moment when the sweet spot for the demand for labor and the supply of workers is met is not based on any arbitrary metric, but when a broad range of companies start increasing wages and offering even more to new workers in order to compete. At that point, it’s the view of companies, not policymakers or economists, that the labor markets have passed the point of balance.

Companies have declared that the country is at full employment. The Fed should declare victory and start to normalize official rates at the same time as it plans to scale back its asset purchase program. However, the Fed is not listening, and the continuation of the easy money will only add to labor market pressures and more inflation.

John Authers: It’s Official. The Inflation Numbers Are a Hot Sticky Mess The debate over whether this is transitory is over, and the question now is what to do.

(…) The current “patient” approach is beginning to look totally inappropriate. My colleague Cameron Crise offered this dramatic chart, which calculated a “real” fed funds rate by subtracting the headline increase in CPI. On this basis, we have the lowest real fed funds rate in history, at a time when inflation is its highest in 30 years.

The real Fed funds target rate has never been this negative

Whoever is running the Fed next year will be aware of the hapless chairmen of the 1970s who presided over the last episode of steeply negative real rates. This is as true for possible Chairwoman Lael Brainard as it is for incumbent Jerome Powell. Tuesday saw long bond yields tumble after news that Brainard had been interviewed, on the assumption that she would be significantly more dovish. That led to an epic switchback after the inflation numbers. Apparently Mr. Market has worked out that no Fed chairman can lie back and do nothing about inflation like this.

Meanwhile, the exceptional turbulence in fixed-income markets, a fact of life for a month now, continued in full force. (…)

In a nutshell, the market has swung strongly against the notion that the Fed can stay patient, and is betting that it has already left it too late. (…)

  • Inflation Is Now Global, But the Traps Are Local Why it’s tough to take the inflation fight to where it truly matters: The big powers like the U.S., China and Europe are hemmed in by domestic policies they can’t exit. Expect prices to keep rising.

(…) Most central banks know how to deal with this, right? They simply raise interest rates. Even critics of prolonged easy money say that when it comes down to it, officials have a tried and true formula. Central banks dare not chance truly runaway levels of inflation and risk a return to the bad old days of the 1970s, at least in the U.S. and Europe. Or, in China’s case, squander a big part of the prosperity and economic stability engineered by Deng Xiaoping’s opening of the economy. For all the talk about cold war between Washington and Beijing, China’s inflation experience has largely tracked the West’s, according to a Reserve Bank of Australia paper published on the eve of the pandemic.

The current hand-wringing isn’t happening in a vacuum, however. China is worried about growth, which is already slacker than the fourth quarter of 2019, before Covid-19 crashed over the world. (…)

For its part, the Federal Reserve will find it tough to accelerate tightening. Chair Jerome Powell has emphasized that quantitative easing should be finished before considering hikes in the benchmark rate. The tapering of QE has only just been announced and is scheduled to wrap up mid-2022. That makes a meaningful withdrawal of stimulus, as opposed to slowing the pace of easing, unlikely before the third quarter. Sure, the Fed can always hasten the taper, but the institution has bent over backwards to avoid a tantrum like the market gyrations of 2013. (…)

ECB President Christine Lagarde is unlikely to find Germany’s broadside helpful. Since the euro’s inception, ECB bosses have grown used to German officials warning about the sins of loose money. (…)

The market for monetary nostalgia is on a bull run. Inflation is globalized, but don’t look for a Plaza Accord-type global response echoing the 1985 pact inked in a swank New York hotel that re-aligned the trajectories of major currencies. Domestic conditions aren’t sufficiently sympathetic.  

Within less than 24 hours, the world’s three largest economies — the U.S., China and Japan — each released inflation data that shattered consensus forecasts and showed prices rising at the fastest pace since at least the early 1990s. Actually the highest print in more than 40 years in Japan.

The fourth-largest economy, Germany, also confirmed inflation at the fastest pace since the early ‘90s, but that release didn’t surprise economists as it was the final print and the beat had come with the preliminary estimate. Germany isn’t letting the side down though — it recently confirmed the highest producer price inflation on records that go back to 1977. This from the country where policy makers famously fear inflation more than most. (…)

What’s bizarre is that we listen to economists on this issue. Today marked the 11th month in a row of Japan PPI beating consensus forecasts! It was the ninth in a row for China PPI. They’ve underestimated seven of the last eight U.S. CPI prints, although NONE of the 70 economists surveyed by Bloomberg anticipated the 0.9% m/m increase in CPI Wednesday — the highest prediction was 0.7%. And yet their “expertise” is still guiding too many people in markets. You almost couldn’t make it up. It’s like the frogs trusting the chef who put them in the pot on whether they will be OK. (…)

Bonds will suffer, but we’ll swing from bouts of curve flattening to steepening. The risk-reward ratio of overpriced momentum stocks now has negative appeal, but some other equity sectors can still perform. Currency markets will see some extraordinary dislocations as FX will be a key outlet for economic imbalances. (…)

The inflation genie is out of the bottle. The immediate path for markets is difficult because the shifting reaction function of big central banks is still in play. It’s not suddenly going to get easier: the year ahead will see immense asset-price dislocations.

(…) The 6.2% increase in the consumer price index in October “would have been enough in any market since 1925 — and for all I know long before that — it would have been enough to have crashed the market,” said the value-investing giant and co-founder of Boston-based asset manager GMO. “But this time the faith in the Fed is so complete that when they say it is temporary we believe it.” (…)

Grantham, 83, said the U.S. central bank has overstimulated the economy repeatedly, inflating the tech bubble in 2000, the housing bubble before the 2008 financial crisis and creating “craziness” in today’s stock market with wild moves in meme stocks.

“Have they learned? Absolutely not,” said Grantham. “The Fed in my opinion, hasn’t done a thing right since Paul Volcker.”

In order to explain today’s “market you have to assume 100% ignoring of rising inflation, which is quite remarkable.” (…)

Manhattan Rents Jump by Most on Record as Tenants Seek Upgrades The median rent rose 18% in October from a year earlier to $3,382, appraiser Miller Samuel Inc. and brokerage Douglas Elliman Real Estate said in a report Thursday. It was the biggest annual increase in data going back a decade.

Jobless Claims Closing in on Pre-Pandemic Lows

With the Veteran’s Day holiday tomorrow, the weekly release of jobless claims was pushed up to today.  Initial claims missed expectations falling to only 267K rather than the anticipated drop to 260K.  Last week’s number was also revised higher by 2K to 271K.  The decline this week marked the sixth week in a row of declines as claims are once again at the lowest levels since March 2020. In fact, this week’s level is only 11K above the March 14, 2020, pre-COVID surge level. (…)

Delayed an extra week, the inclusion of all other programs showed yet another drop in continuing claims on an unadjusted basis. Total claims across all programs fell to 2.57 million, down roughly 100K from the previous week. Essentially that entire decline was on account of regular state claims with the moves in PUA and PEUC claims basically netting out. There continue to be some residual claims from pandemic era programs, but they now account for a significantly smaller share of claims than was the case only a few months ago, and generally, those claim counts have declined. (…)

(Bespoke)

Chinese Developers Rally on Policy Hopes as Evergrande Again Averts Default Stocks and bonds of Chinese developers jumped on signs that Beijing could moderate its tough stance on the beaten-down property sector, while industry heavyweight China Evergrande made another set of last-minute bond payments.
China’s Xi Wins Backing for Doctrine Enabling Third Term He now has a mandate to potentially rule for life.

THE DAILY EDGE: 10 NOVEMBER 2021: Faster CPI, Slower China

This a.m: CPI for all items rises 0.9% in October as most indexes increase

The Consumer Price Index for All Urban Consumers (CPI-U) increased 0.9 percent in October on a seasonally adjusted basis after rising 0.4 percent in September, the U.S. Bureau of Labor Statistics reported today. Over the last 12 months, the all items index increased 6.2 percent before seasonal adjustment.

The monthly all items seasonally adjusted increase was broad-based, with increases in the indexes for energy, shelter, food, used cars and trucks, and new vehicles among the larger contributors. The energy index rose 4.8 percent over the month, as the gasoline index increased 6.1 percent and the other major energy component indexes also rose. The food index increased 0.9 percent as the index for food at home rose 1.0 percent.

The index for all items less food and energy rose 0.6 percent in October after increasing 0.2 percent in September. Most component indexes increased over the month. Along with shelter, used cars and trucks, and new vehicles, the indexes for medical care, for household furnishing and operations, and for recreation all increased in October. The indexes for airline fares and for alcoholic beverages were among the few to decline over the month.

The all items index rose 6.2 percent for the 12 months ending October, the largest 12-month increase since the period ending November 1990. The index for all items less food and energy rose 4.6 percent over the last 12 months, the largest 12-month increase since the period ending August 1991.

image

image
image
U.S. Producer Prices Are Strong Again in October

The Producer Price Index for Final Demand rose 0.6% in October following a 0.5% gain in September. The y/y increase remained at a record high of 8.6%. The series dates back to 2009. A 0.7% rise had been expected by the Action Economics Forecast Survey. The PPI excluding food and energy rose 0.4% last month after a 0.2% gain. The y/y increase remained at the record 6.8%. A 0.5% increase had been expected. The PPI less food, energy and trade services also rose 0.4% (6.2% y/y), double the September rise.

Higher energy prices led last month’s rise in the PPI with a 4.8% (42.4% y/y) increase. Gasoline prices surged 6.7% in October (89.9% y/y) while home heating oil prices rose 13.0% (114.8% y/y). Natural gas prices increased 3.8% last month (28.7% y/y) but the cost of electric power eased 0.3% (+5.6% y/y).

Food prices eased 0.1% during October (+10.5% y/y) and offset some of this energy price strength. (…)

Finished consumer goods prices less good & energy rose 0.3% in October (5.5% y/y). Nondurable consumer goods prices gained 0.3% (4.7% y/y), the smallest monthly increase since April. Durable consumer goods prices edged 0.1% higher last month (6.9% y/y). Prices for private capital equipment strengthened 0.4% (5.6% y/y) and have been strong since the spring.

Services prices rose a diminished 0.2% in October (5.9% y/y) for the second straight month. Trade services prices rose 0.4% (8.5% y/y) and also have been strong since the spring. Prices less trade, transportation & warehousing edged 0.1% lower (+4.2% y/y).

Construction product prices surged 6.6% last month (12.3% y/y) reflecting a 7.5% rise (13.3% y/y) in construction costs for private capital investment.

Intermediate goods prices jumped 2.1% (25.4% y/y) due to a 29.1% surge (160.0% y/y) in unprocessed fuel costs.

image

 image image

China Factory Inflation Grows at Record Pace on High Energy Prices Producer prices jumped 13.5% in October, fueling worries about continued global inflation

China’s producer-price index rose by a record 13.5% in October from a year earlier, accelerating from a 10.7% increase in September, according to the National Bureau of Statistics. (…)

Consumer inflation in the world’s second-largest economy rose by 1.5% last month from a year earlier, up from 0.7% in September, though it remained below the official target of around 3% for this year. (…)

Higher coal and metal prices could deter local authorities from buying steel and other commodities needed for infrastructure construction, a key driver of growth that China often relies on to stave off slowdowns.

As a result, China’s growth could slow to a 3.6% year-over-year expansion in the fourth quarter, down from 4.9% in the third quarter, according to a forecast from Zhaopeng Xing, chief China strategist at ANZ. (…)

ZeroHedge has better reporting on China’s inflation:

(…) In reality, however, there was just one key variable – thermal coal, which as we said last month indicates that PPI will continue rising far higher, although judging by the recent sharp reversal in the price of Chinese thermal coal (if only for the time being), this may be as high as PPI gets.

Or so Beijing should hope because with the spread between PPI and CPI hitting a new all time record, virtually no Chinese companies that use commodity inputs – which in China is a vast majority – are making any profits.

The gap between upstream and downstream prices “continues to highlight weak consumer demand in the economy and the immense pressure on profit margins downstream firms are facing,” said Michelle Lam, greater China economist at Societe Generale SA in Hong Kong. (…)

  • Overall CPI would have risen almost 2.5% if not for the effects of falling pork prices, according to the NBS.
  • Non-food CPI inflation increased to +2.4% yoy in October from +2.0% yoy in September, primarily on a sequential increase (especially fuel costs). Fuel costs increased by +31.4% yoy in October (vs. +22.8% yoy in September).
  • Core CPI inflation (headline CPI excluding food and energy) edged up to +1.3% yoy in October (vs. +1.2% in September), with inflation in services flat at +1.4% yoy in October. In other words, producers are passing on a growing part of their own surging costs on to consumers, but nowhere near all as the record gap between CPI and PPI shows.
  • Local stocks were certainly not happy, with China’s CSI 300 Index sliding as much as 1.3% amid signs that producers are passing on higher costs to consumers, and that the PBOC may have no choice but to tighten financial conditions at the expense of risk assets. Several food companies have already announced price hikes of up to 15%, including Haixin Foods, Anjoy Foods and Jiajia Food, due to rising costs for raw materials. (…)
China’s Credit Stabilizes as PBOC Encourages Banks to Lend

(…) The PBOC recently told banks to ease some excessive restrictions on lending to the property sector as concerns mounted over the industry’s health with the deepening of China Evergrande Group’s debt crisis. (…)

Growth of China's outstanding credit stock stabilized in October

  • BTW:

image

  • BTW #2: Anne Stevenson-Yang, J Capital’s excellent analyst, informs us that
    • Property remains the principal vehicle for investment in China, so the current decline in property prices threatens to drag down returns in every investment.

    • Given the decline in property values, wealthy Chinese are moving money into financial assets, especially stock market-related funds.

    • The
      shift out of property investments suggests that China’s decline in construction may be sustained and that the price declines for commodities like iron ore and coal will continue.

  • Goldman Sachs: “While we expect macro policies to ease somewhat to support growth next year, much of the structural tightening that intensified this year – especially in the property market – is here to stay, in our view. Therefore, we forecast real GDP to grow 4.8% in 2022 and expect average annual growth of only 4.5% during 2022-25, significantly below market consensus. (…) we believe the Chinese property market is in a multi-year slowdown. (…)

  • “The experience of the US-China trade war and the Covid pandemic have likely convinced Chinese policymakers that resilience is more important than speed when it comes to growth. As President Xi aims to secure a third term next year, the leadership seems to be taking an even longer-term view on development than before. With this backdrop, we believe the Chinese economy is settling into a new regime where policymakers accept slower growth in the near term for a more resilient economy in the long run.”

European Gas Prices Slump as Russia Finally Increases Supplies

Benchmark Dutch futures fell more than 10% after flows to Europe via Ukraine and Poland edged higher Wednesday. Gazprom PJSC booked some pipeline capacity on the Ukrainian-Slovakian border for the day, bringing supplies through the route in line with Russia’s long-term transit agreement with its neighbor.

Putin said late last month that Gazprom would refill its European storage facilities after finishing Russia’s domestic stockpiling campaign, which ended Monday. Any extra supply is welcome, as Europe started its heating season with the lowest inventories in more than a decade.

Traders are watching every move by Europe’s top supplier, focusing on how much gas is delivered beyond contracted volumes. Auctions for December pipeline capacity run next Monday, which will cast light on whether extra shipments could materialize. Additional bookings may be unlikely unless Gazprom sees progress in the certification of the contentious Nord Stream 2 pipeline, some analysts said. (…)

Meanwhile, Russia is boosting gas production, with a full-year output forecast at 777 billion cubic meters, up 12% from 2020, Energy Minister Nikolay Shulginov said Wednesday.

For now, Russian gas deliveries remain much lower than normal for the time of the year and the gains this week come after a recent slump. The bearishness is also limited by colder weather forecasts for large parts of Europe, Energi Danmark said in a note on the website.

Gazprom is increasing shipments to Europe, but from a very low base

US equity investor sentiment surges higher as earnings outlook brightens

The Risk Appetite Index from IHS Markit’s Investment Manager Index™ (IMI™) monthly survey, which is based on data from around 100 institutional investors each month, rose from +7% in October to +36% in November, its highest since the survey peak of +54% seen back in April 2021. As such, the survey indicates a substantial improvement from the near-evaporation of risk appetite recorded back in September.

The swelling of risk appetite was accompanied by a marked uplift in investors’ expectations of market returns over the coming month to a survey high, surpassing the prior (April) peak by a wide margin and building further on the improvement seen in October.

By comparison, the survey’s Expected Returns Index had fallen to -12% in September, which preceded the brief market fall, before rising again to signal to a marked turnaround in sentiment which has gathered momentum over the past two months. The index has now risen to +38%.

unnamed (91)

The biggest drivers of the market in the near-term are considered to be equity fundamentals and shareholder returns, the former viewed as the most supportive since August and the latter seen as more supportive than at any time over the 14-month survey history.

However, November also saw investors’ expectations of market support from both central bank and fiscal policy lift higher, having sunk in both cases to survey lows in October. Similarly, the macro environment is also seen as more positive for equities than viewed in October, with both the US and global economies set to provide the biggest contributions to returns since July, coinciding in particular with signs of the COVID-19 Delta wave easing.

With the S&P 500 reaching new highs, valuations against historical levels meanwhile remain by far the largest perceived anchor on the market, and is the only factor not to see an improving trend in November.

The political environment is again perceived as a net drag on returns, albeit slightly less so than in October, reflecting concerns over domestic budget spending as well as broader geopolitical issues and China’s tech regulation.

In terms of sector preferences, financials have retained the most-favored spot in November for a third successive month having seen the biggest positive shift in sentiment over the past year, followed by healthcare. However, it was tech stocks that enjoyed the largest upswing in favorability compared to October, with sentiment rising to the highest since February.

Economy hopes meanwhile lifted sentiment towards consumer discretionary, industrial and basic materials, though in some cases inflation and supply line worries continued to constrain appetite. Utilities, real estate and consumer staples are seeing ongoing bearish sentiment.

These improving factors coincide with a strong Q3 earnings season which has led investors to revise up their expectations of Q4 earnings on average.

The Q3 results so far have prompted 32% of investors to ramp up their expectations of Q4 earnings, according to the latest IMI poll, outnumbering the 10% that have revised down their expectations by three-to-one.

The net upward revision of +22% is lower than the reading of +30% seen back in August, but nevertheless is a strongly positive reading.

The overall net upward revision to Q4 earnings estimates tallies with the substantial jump in risk appetite recorded by the November IMI survey and coincides with equity fundamentals being the strongest expected driver for near-term market returns in the latest poll. (…)

Nordea offers mitigating info to the earnings optimism:

Nordea/Macrobond (via The Market Ear)