
This a.m.: 35,224
Virus Rescue Plan Stalls When Democrats Block McConnell’s Offer Talks between Schumer, Mnuchin continue on $2 trillion plan
-
Monday Morning Coronavirus Package Re-Vote Rescheduled For Noon McConnell says Democrats are “playing Russian roulette with the market.”
-
Germany Approves $800 Billion Package to Counter Virus Impact
That is almost $10k per habitant. U.S. equivalent: $3.3T package.
Iran reported 1,411 new cases and 127 new deaths in the past 24 hours. The country has 23,049 total cases and 1,812 people have died, while more than 8,000 have recovered so far. The health ministry said the average age of Iran’s coronavirus patients was 59, and the average age of those who died was 64. About 60% of the reported cases and deaths were men, the ministry reported.
U.K. Prime Minister Boris Johnson warned Britons they face “tougher measures” to fight the outbreak, including a potential full lockdown if they continue to ignore calls to stop social gatherings.
U.S. President Donald Trump said his administration will make a decision as to “which way we want to go” regarding coronavirus measures after a 15-day period. “WE CANNOT LET THE CURE BE WORSE THAN THE PROBLEM ITSELF,” Trump said in a tweet.
Hmmm…
Top Economists See Echoes of Depression in U.S. Sudden Stop
(…) as business activity halts and layoffs surge, some prominent economy watchers — including former White House chief economists Glenn Hubbard and Kevin Hassett and former Federal Reserve Vice Chairman Alan Blinder — have drawn comparisons to the Great Depression, though they’ve stopped well short of forecasting another one.
Former International Monetary Fund chief economist Maury Obstfeld said the world hasn’t seen a synchronized interruption in economic output in decades. (…)
JPMorgan Chase & Co. expects gross domestic product to shrink at an annualized rate of 14% in the April-June period while Bank of America Corp. and Oxford Economics both see a 12% drop. Goldman Sachs Group Inc. sees a 24% plunge.
In a Bloomberg interview on Sunday, Federal Reserve Bank of St. Louis President James Bullard predicted the unemployment rate may hit 30% in the second quarter because of shutdowns to combat the coronavirus, with an unprecedented 50% drop in GDP.
(…)
“Unless this virus miraculously disappears from the population over the course of the next few months, it is a reasonable scenario that we might be in this lockdown setting for quite a while, measured in quarters,” said Harvard University professor James Stock, who is a member of the National Bureau of Economic Research panel that dates the timings of recessions.
If everybody stays home for six months, “it is going to be like the Great Depression,” Hassett, who’s returning to the White House to advise on economic matters, told CNN on Thursday. (…)
It was policy mistakes — particularly by the Fed — that turned the contraction nearly a century ago into a depression.
“I am fearful of that if we don’t do the right policy,” said Hubbard, now at Columbia Business School. (…)
Unlike nearly a century ago, the Fed has acted fast, cutting interest rates effectively to zero, restarting quantitative easing and resurrecting emergency financing facilities it used during the financial crisis. (…)
Some analysts trying to project the economy’s path cite the 1918 influenza pandemic that claimed an estimated 50 million lives worldwide.
In a recent presentation to a virtual Brookings Institution conference, economist Robert Barro said that countries back then typically suffered a 6% reduction in GDP, about in line with that of the last recession but far smaller than in the Great Depression.
He described his findings as an upper-bound estimate of the economic impact from the coronavirus. Global health systems are better equipped to handle contagion now, but the world is more interconnected, Barro said.
“We think of a depression as a recession that is very, very deep and very, very long,” said Blinder, now a Princeton University professor. “That’s the kind of thing that could happen” should infections peak only temporarily then return in the fall.
-
Goldman Sachs sees 1% drop in global GDP due to ‘coronacrisis’ a sharper economic decline than in the year following the 2008 global financial crisis.
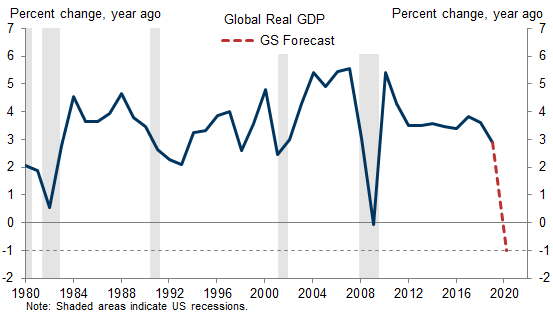
(…) Based on the hard data for January/February activity in China, we now estimate that Q1 real GDP there contracted 42% in terms of the quarter-on-quarter annualized rate (qoq ar). With lockdowns and social distancing becoming pervasive elsewhere, we expect real GDP in the advanced economies to contract very sharply in Q2, including a 24% drop in the United States that would be 2½ times as large as the previous postwar record. (…)
The overall easing of fiscal policy now underway in advanced economies is likely to be the biggest of the postwar period. It is hard to be precise about the global numbers because many countries are still finalizing their responses, but the US seems to be on track for a massive 6-7% of GDP easing in 2020 alone; this would be considerably bigger than President Obama’s 2009 Recovery Act and will almost certainly push the federal budget deficit to a postwar high relative to GDP. The biggest components of the package—or at least the Republican Senate version of it—are the business interruption loans for small firms noted above, other forms of aid for directly affected industries, and $1,200 rebate checks for every low- and middle-income taxpayer. (…)
So will it work? Not in the sense of preventing a dramatic near-term contraction, which mostly reflects a physical constraint on economic activity rather than a lack of income or access to credit. But the policy easing is nevertheless very important. The fiscal measures should relieve financial distress—especially among lower-income households—and limit at least to some degree the negative multiplier process in which lower income feeds into lower spending and back into lower income even after the health crisis has passed. The monetary measures are designed to help keep the financial system intact and thus able to play its role in extending credit, both through the crisis and after the recovery has started. This remains a challenging task, but it is helped by the fact that the banking system (especially in the US) is on a much better capital and liquidity footing than prior to the GFC.
When will the recovery start and what will it look like? The timing depends mostly on progress in combating the disease. We don’t have much expertise in this area, but our working assumption is that the lockdowns and other measures will succeed in slowing new infections within a few months of their initial adoption, as they seem to have done in China. If so, the physical constraint on economic activity should gradually loosen toward the end of Q2, allowing GDP to start rising again in Q3. However, the risks to this forecast are skewed to the later side, mainly because it might take longer to slow new infections. With regard to the shape, Exhibit 2 shows that the normalization in our forecast is not particularly rapid. In fact, even by the end of 2020, GDP remains 5% below the pre-virus trend because we assume that some types of economic activity only come back slowly and because the negative multiplier effects via the labor market deterioration are likely to weigh on the recovery for a while. But even under these conservative assumptions, Exhibit 2 implies growth rates of more than 10% in annualized terms, which would qualify as a very strong recovery under any normal set of circumstances. Of course, the current set of circumstances is anything but normal because the constraint on economic activity is primarily physical, not financial. That means a much faster downturn but probably also a faster recovery.
(…) if the Euro area decided to view itself as an economic nation state—at least for the time of the outbreak and its aftermath—it would actually be in quite a strong position. Last year, the general government deficit stood at ½% of GDP in the Euro area as a whole (and 1½% excluding Germany) compared with 7% in the United States. Moreover, the ECB’s ability to buy Euro-denominated debt is just as unlimited as the Fed’s ability to buy Treasuries. (In some ways, the ECB is in a better position than the Fed because it is allowed to buy a much wider range of assets.) Policymakers are therefore more than able to send an even more unambiguous “whatever it takes” signal than last week—and we expect they ultimately will.
A Washington Liquidity Infusion The Senate virus bill may help the economy stave off a depression.
(…) By our [WSJ] deadline, the Senate had not reached a final deal. But the bipartisan draft bill and summaries we’d seen on Sunday afternoon were a major improvement on the state of play on Friday. The overall cost is murky, though it will be in the multi-trillions of dollars, and that includes hundreds of billions in subsidy payments to individuals to buy broad political support.
The version we examined is nonetheless worthy of Senate passage—not least to avoid House Speaker Nancy Pelosi making it worse. She and Senate Minority Leader Chuck Schumer were blocking a deal late Sunday with more demands from their non-virus-related policy wish list.
The window for providing liquidity to stressed businesses is closing faster than many realize. Markets face another tumultuous week, with many industries hard-pressed to find financing. Real-estate investment trusts, with investments in shopping malls that have few customers as people stay home, are one problem to watch. Non-bank financial institutions are another.
The most urgent need is for the Treasury to have more money to backstop the Federal Reserve as it stands up one or more facilities to provide liquidity. The Senate bill evolved for the better on this point over the weekend. The bill appropriates up to $425 billion for the Treasury’s Exchange Stabilization Fund that backs Fed facilities under Section 13(3) like the one launched last week for money-market funds. (There’s another $75 billion for airlines and firms deemed crucial to national security.) This can be leveraged up to well over $1 trillion in lending power to calm markets.
As important, the Senate language shows the Treasury and Fed will be able to provide this money to all comers who don’t qualify for the bill’s small-business lending provision. One holdup is Democratic demands to attach more burdens on businesses that borrow from the Fed, such as dictating union board members or limiting executive pay.
There should be as few strings as possible because the point is to coax distressed companies to use the facility before they are on the verge of failure. The point is to prevent bankruptcy or default, not hope to salvage companies when they’re about to fail. Strings-free loans will encourage still-healthy firms to participate and prevent further economic harm.
The bill does block companies that take direct loans from buying back stock for the duration of the loan. (…) Democrats want the buyback limits to continue forever, which is purely punitive. (…)
A second liquidity provision provides about $350 billion for small businesses of fewer than 500 employees, and that too evolved for the better. Businesses will have access to loans of up to $10 million for working capital like paying employees and keeping the lights on. The portion of the loan that finances employees will be forgiven if workers aren’t laid off and don’t see a major reduction in pay. (…)
The main rub here will be bureaucratic, since the loans will be administered through the Small Business Administration’s 7(a) program. The SBA has neither the systems nor the employees to do this quickly or efficiently. With that in mind, the bill attempts to streamline the bureaucratic traps so some 800 or so SBA-approved banks and other lenders can move the money fast. (…)
This liquidity panic isn’t the result of bad business decisions. It’s the result of government orders to save lives. The loans are designed to keep employers alive during this forced shutdown so employees will still have jobs when it’s over. The Trump Administration still needs a Phase Two strategy soon to move past the shutdown, and Democrats need to end their partisan obstruction lest they send the economy into a far deeper recession.
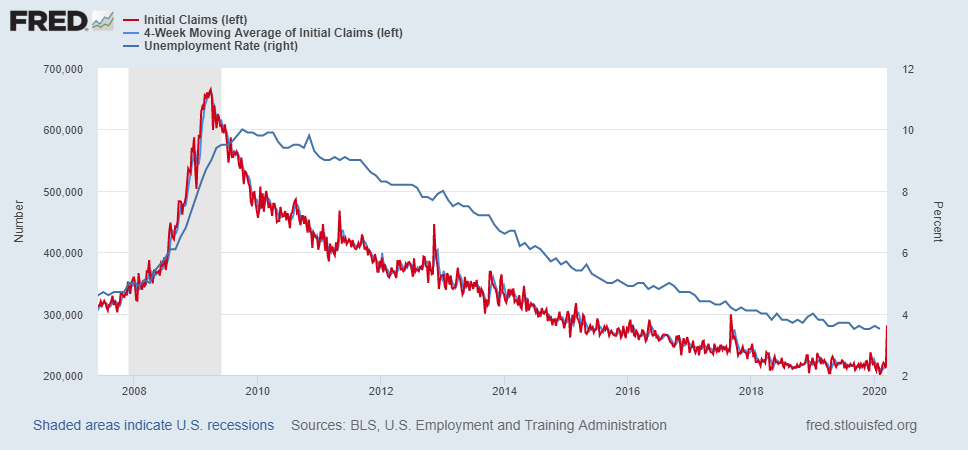
Coronavirus-Triggered Downturn Could Cost Five Million Jobs Economic forecasts turned bleak as it became clear that a pandemic would now affect life in the U.S. far more than originally understood.
Coronavirus Hits Already Frail U.S. Farm Economy The new coronavirus is dealing another blow to the struggling U.S. agricultural sector, driving down crop and livestock prices and threatening labor shortages for farms.
Goldman spends $1bn to shore up two money market funds Coronavirus crisis triggers rush of selling by institutional investors
US subprime mortgage specialist seeks buyers for $1bn of assets Fund manager AlphaCentric suffers heavy outflows on coronavirus fears
How Long Will the Coronavirus Lockdowns Go On? Soon the U.S. will be able to do 75,000 tests a day. That will make changes in strategy possible.
(…) Here’s what the priorities should be in the coming weeks, with a focus on preventing new sparks of the virus from turning into the fires of New York and Seattle.
(…) the U.S. will need widespread testing to know where and to what extent the virus is spreading. Testing capacity has increased significantly in the past few weeks thanks to relentless efforts from public, academic and private labs such as Quest and LabCorp. Producers of testing kits are also working overtime. A new test developed by Cepheid can be deployed in a doctor’s office.
By the end of next week, the U.S. will have the capacity in place to screen more than 75,000 people a day. South Korea tested 1 in 160 of its people and deployed technology to identify people who were infected and trace contacts. The U.S. should do the same.
Another step: serological surveillance, which means blood tests to detect antibodies developed to fight the novel coronavirus. These antibodies confer immunity and can reveal whether a person has been exposed. If a sizable portion of a local community has some protection, authorities can be more confident in relying on less invasive measures. Once deployed, serological tests are cheap, straightforward, and easy to scale.
Most important is developing a therapy to treat Covid-19 or perhaps prevent people from contracting it. America is home to a vast, dynamic life-science industry. This is its moment. This is why decades of drug investment and development matter so much. (…)
Perhaps the most promising option for now is antibody drugs engineered by biotech companies that target features on the virus’s surface. This strategy was used with success against Ebola. These medications can be given as a prophylaxis to prevent infection for doctors or older populations at high risk of exposure, and can also be used on infected patients. Regeneron developed one such treatment against Ebola. The company has a product in the works to target Covid-19 that could be ready as soon as this summer.
Regulators need to innovate as well. The Food and Drug Administration should leverage “master protocols,” which allow providers to test multiple promising therapies in the same large trial. Doctors caring for Covid-19 patients are about to be overwhelmed. They won’t have time to deal with the administrative burdens of enrolling in a clinical trial. This was a problem in China. Regulators should create simple, standardized templates for enrollment and monitoring. Electronic data collection can ease the burden on hospitals.
For the most promising drugs, we should scale up manufacturing before we know for sure if they work. That means producing millions of doses while trials are under way. Sen. Steve Daines (R., Mont.) has suggested adding a provision to this effect to one of the relief bills in Congress. We have to be ready to distribute a drug on a massive scale as soon as it is proved safe and effective.
People will suffer and die in the coming weeks. For many others, the U.S. can still turn the coronavirus into a manageable threat. With the right mix of controlling transmission, expanding testing and deploying promising drugs, American ingenuity can beat back this pathogen.
THE COMING SLICK DEAL
Some U.S. Energy Officials Want Saudis to Ditch OPEC A push is on for the Trump administration to create an oil alliance with Saudi Arabia
A group of Energy Department officials are pushing the Trump administration to forge an oil alliance with Saudi Arabia, a partnership supporters say could join the world’s two largest oil-producing nations and pave the way for the Saudis to leave OPEC, according to people familiar with the situation.
Backers of the plan say it would help stabilize global crude markets, preventing more crashes like the one that has led to prices plunging 60% since January. It also could head off potentially stronger ties between the Saudis and Russia and reaffirm the kingdom’s longstanding alliance with the U.S., according to the people.
The plan faces major obstacles. The partnership likely would mean a much more active role for the U.S. government in global oil markets, which could raise objections from oil-industry executives and lawmakers who have championed free trade.
The concept is being discussed among Energy Department officials, and it hasn’t been endorsed by department leaders or the White House, the people said, nor has it been presented to the Saudis. (…)
Several U.S. oil companies and their lobbyists have pressed the administration and Congress for intervention to resolve the price war. (…)
Crude prices at two-decade lows have dozens of U.S. oil companies facing bankruptcy. In the short-term, the administration is facing immense pressure from the energy industry and members of Congress to get Saudi Arabia to stand down and cut oil output. (…)
It wouldn’t include U.S. government coordination of oil output now controlled by the private sector, one administration official said. But it could pledge the country would more actively use national reserves and economic stimulus to blunt price spikes and dips, or give Saudi Arabia some legal indemnities on its oil-market activities, the person said. Officials are considering many options.
Energy Department officials see a window of opportunity with Russia and Saudi Arabia now at odds, and want to move before the two nations patch up their differences, administration officials said.
And in its early stages it has already drawn ire from State Department officials who feel it is unworkable and unlikely to offer the Saudis anything they would want, according to several people familiar with the matter.
“I’m extremely skeptical,” said Matthew Reed, an analyst at Washington-based consulting firm Foreign Reports. “The other 12 members of OPEC (combined) produce more than U.S. and the Saudis aren’t about to give up on 60 years of cooperation. It’s a dysfunctional family, but it’s still family. OPEC is their baby.” (…)
Everybody currently needs and wants higher oil prices. My sense is that the U.S. thinks that Putin will want to prevent a US-SA deal that would isolate Russia. In this face-saving exercise, a “voluntary” U.S. production cut would meet Russia’s and the Saudis’ goals and bring much needed relief to the oil industry, in its largest sense, and, importantly, to the whole credit complex which has been destroyed by the prospects of widespread bankruptcies.
Read this next piece carefully. You don’t need to be an expert at reading between the lines to see what’s coming: a slick ménage à trois. (my emphasis)
-
OPEC, U.S. Shale Producers Open Talks Amid Oil Rout An industry regulator in Texas is aiming to stabilize global crude prices by starting a dialogue with OPEC’s secretary-general about curbing U.S. production.
U.S. oil industry regulators opened a dialogue with OPEC in talks that could help foster a truce between the world’s three largest oil producers and potentially resolve a Saudi-Russian price war that has devastated oil markets in recent weeks, according to people familiar with the matter.
Mohammed Barkindo, secretary-general of the Organization of the Petroleum Exporting Countries, spoke Friday with Ryan Sitton, the Texas railroad commissioner who oversees the U.S.’s biggest oil patch, these people said.
“Just got off the phone with OPEC SG Moh[ammed] Barkindo. Great conversation on global supply and demand,” Mr. Sitton said on Twitter. “We all agree an international deal must get done to ensure economic stability as we recover from COVID-19.“ The Texan official said the OPEC chief had invited him to the next meeting of the organization in June.
U.S. antitrust laws prevent a formal deal and there is no suggestion the two sides would coordinate on production decisions. But the Texas regulator is considering curtailing output in America’s largest oil-producing state for the first time in decades, people familiar with the matter have previously said.
Mr. Sitton said he would gauge international reaction to the idea of production cuts before deciding how to proceed. “I’m not advocating for Texas to do anything on its own,” he said in an interview.
Meanwhile, Wayne Christian, the Texas commission’s chairman, said he has a number of reservations about a production curtailment. (…)
U.S. shale companies have complained to Mr. Barkindo about collapsing oil prices and he has also spoken to Frank Fannon, the senior State Department official in charge of energy matters, according to Saudi officials. [!] (…)
A decision by American producers to reduce output would help the Kremlin claim a victory and spur Russia to resume talks with Saudi Arabia, Saudi officials said.
Saudi officials expect Russia will ultimately return to the table as lower crude prices dent its economy, but only if it can present the oil diplomacy as a face-saving move, according to officials in the kingdom.
A Saudi official said “the perfect [scenario] would be the U.S. giving their word over this and that would make it easier to convince everyone to cooperate.”
Separately, the U.S. is considering other avenues to alleviate the pressure on American oil producers. The Trump administration is considering a diplomatic push to get the Saudis to cut oil production in tandem with threats of sanctions on Russia, people familiar with the matter said. (…)
In Russia, oil companies are also struggling with lower crude prices. Many producers there could begin hemorrhaging cash if prices remain below $30 a barrel and some, like state-run giant Rosneft, ROSN -6.08% are also stifled by U.S. sanctions tied to the annexation of Crimea. (…)
Russia would like to see higher oil prices and is always ready to talk, Kremlin spokesman Dmitry Peskov said this week, “especially in such dramatic times.” (…)
Saudi Arabia won’t be able to keep up its price war for too long, say officials familiar with the matter. The kingdom has been forced to cut its budget but needs benchmark oil prices over $60 a barrel to sustain an ambitious reform program. As part of its announced price-war plan it is set to boost supplies to customers by 2.5 million barrels a day to offset the effect of lower prices. But that level won’t be sustainable beyond June, Saudi officials said.
The price war and ensuing oil-market rout mean that when the Saudis and OPEC meet again, the group will likely seek production cuts much larger than the ones Russia refused earlier this month, officials in the cartel said. That is because demand is set to collapse globally as the impact of the outbreak moves from East Asia to Western Europe and the U.S.
“If there is a meeting a significant cut is needed. We are way past the cut we wanted a few weeks ago,” said a senior Saudi official.
The cartel may propose cumulative, collective cuts of six million barrels a day, rather than the 3.6 million barrels a day it was ready to accept earlier this month, said one non-Saudi OPEC official.
“Russia would have to cut more than the cosmetic cuts they have been getting away with for a very long time,” said the Saudi official.
The Worst of the Global Selloff Isn’t Here Yet, Banks and Investors Warn Wall Street is only now coming to grips with the dislocation being wrought by the coronavirus
(…) Wall Street is only now coming to grips with the dislocation being wrought by the virus. Analysts at Goldman Sachs Group Inc. said this past week they expect U.S. economic output to tumble 24% in the second quarter, one of the worst readings on record and potentially foretelling a U.S. recession even if growth picks back up in the second half of the year. (…)
“The ultimate impact of the virus on economies and markets is highly speculative at this time since there is so much we do not know about how the outbreak will actually evolve from here,’’ said Rick Lacaille, global chief investment officer of State Street Global Advisors. “We need clarity on many fronts.” (…)
The firm [GS] forecasts the S&P 500 could be in for a 41% fall from peak to trough. Bank of America Corp. believes the selloff might not ease until the S&P 500 hits 1800—a 47% drop from its February record. And Credit Suisse Group AG , which notes stocks didn’t hit their trough during the SARS pandemic in 2003 until a week after the number of new infections peaked, estimates the S&P 500 could be in for a 35% drop overall. (…)
To put a floor on the current market rout, some of the world’s biggest investors say they need three things: better information on the scale of the coronavirus pandemic, powerful support from governments and more forceful intervention in markets. (…)
Investors need “clarity on the ultimate scale of the problem and evidence that the infection’s curves are bending globally,” said Jean Boivin, head of BlackRock Investment Institute. Credible news on development of a vaccine and treatments would also help restore confidence, he said. (…)
“Market participants need to feel they are backstopped without question,’’ said State Street’s Mr. Lacaille. “Arguably this is what the Fed and Treasury Department have tried to signal and achieve, turning from messaging into action, but it seems there is a leap of faith needed by the market too.’’
WHEN ZOMBIES MEET A BLACK SWAN
WeWork’s Board Prepares for a Fight as SoftBank Gets Cold Feet
That concept looks dead right now…

 Trump Writes to North Korean Leader in Midst of Coronavirus Emergency North Korea says Trump offered to help Kim Jong Un address virus
As much as I looked, I could not find any article suggesting Trump offered virus help (!) to any other country like South Korea, Italy, Germany. Oh! Sorry, yes, help was offered to Iran but flatly rejected. Just saying…
-
Trump says US willing to help Iran with coronavirus State Department offers unspecified help to hard-hit country via Swiss diplomatic channel
-
With Iran Ravaged by Virus, U.S. Is Pressured to Ease Sanctions So far, the Trump administration isn’t budging.



 OPEC + + ?

