The enemy of knowledge is not ignorance, it’s the illusion of knowledge (Stephen Hawking)

It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so (Mark Twain)

Invest with smart knowledge and objective odds

THE DAILY EDGE: 31 JANUARY 2020

U.S. Economy Heads Into 2020 With Steady Growth Fourth-quarter growth of 2.1% reflected boost from trade as exports increased; pace of consumer spending slows

Year-over-year growth of 2.3% was the slowest pace since 2016, but in line with the average pace that has marked the expansion that began in mid-2009. (…) The 2.3% year-over-year growth in 2019 was well below the 3.1% level that the White House projected. (…)

image

Consumer spending rose at a 1.8% annual rate in the fourth quarter of 2019 from a 3.2% pace the prior quarter, and business investment dropped for the third quarter in a row, while residential investment picked up. (…)

Overall private-sector inventories subtracted 1.1 percentage point from the fourth quarter’s growth rate. A decline in retail inventories, notably at motor-vehicle dealers, came as the United Auto Workers union nationwide strike at General Motors Co. ran through most of October.

Meantime, net exports added 1.48 percentage point to the quarter’s 2.1% growth rate, the largest contribution since the second quarter of 2009. Exports rose at a 1.4% annual rate and imports dropped at an 8.7% pace. (…)

The fourth quarter GDP numbers are notable because of the outsized contribution from net exports and government spending. I inserted black rectangles in this charts to highlight the trend in real private final sales (GDP ex-gov, ex-net exports), showing the declining momentum of the past 2 years. Biz investment has completely stalled while the contribution from consumer spending has gotten gradually smaller.

image

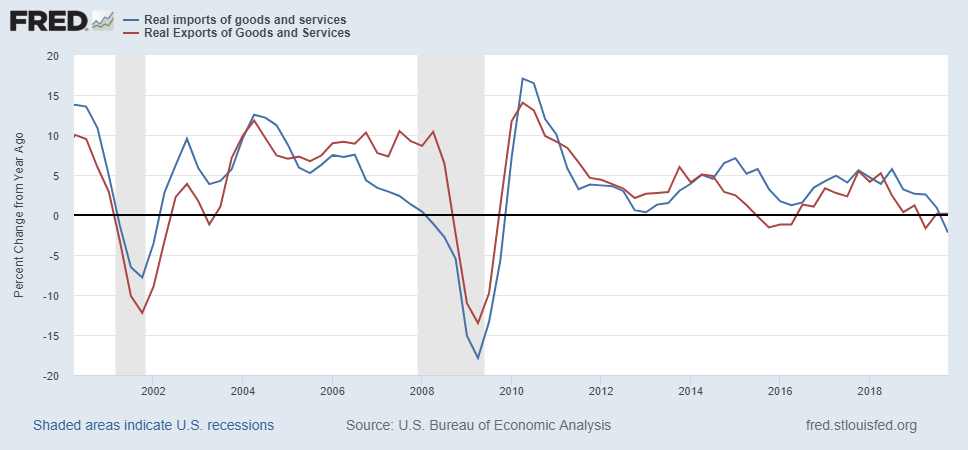
Net exports had a particularly outsized contribution in Q4 (1.5 points) but that was only because real imports slumped 8.7% annualized in Q4, the worst since the 2009 recession, and “adding” 1.3 points to Q4 GDP growth rate. Real imports in Q4 were down 2.2% YoY with no offset from exports. This is the first time U.S. real imports decline YoY outside of recessions since 1952!
fredgraph (53)

Moreover, imports of consumer goods collapsed 25% a.r. in Q4! Merely an inventory correction? This is not just American consumers as U.S. exports of consumer products contracted at a 13% annualized rate in Q4 (autos: –24% a.r.)

U.S. real exports have been flat for 2 years. Meanwhile, as these KKR charts show, China has diversified its export markets and gained significant market share since mid-2018:
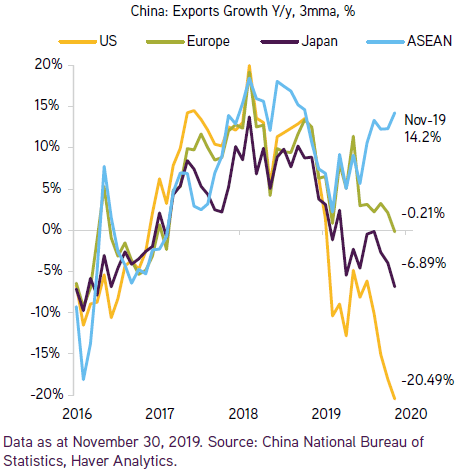
 image image

Speaking of the important, if not crucial, U.S. consumer, this morning’s Personal Income and Outlays release was not encouraging. Real disposable income declined in 2 of the last 3 months and was flat overall in Q4. Americans dipped a little into their savings and grew real spending 0.1% MoM in December and +1.6% annualized in Q4 (yesterday’s GDP pegged it at +1.8%). Even real expenditures on Services were weak at +2.0% annualized in Q4 after +2.2% in Q3 and +2.8% in Q2.image

Eurozone Growth Hits 6-Year Low as Key Automobile Industry Struggles The eurozone’s economy slowed sharply in 2019 as factories faltered amid weak overseas demand and its key automobile industry struggled to get to grips with a cooling market and the costs of developing a new generation of electric cars.

(…) The European Union’s statistics agency said Friday the eurozone’s gross domestic product—the value of all goods and services produced across the economy—grew 1.2% last year, its weakest expansion since 2013, when the currency area was emerging from its twin government debt and banking crises. (…)

Eurozone GDP rose at an annualized rate of just 0.4% in the three months through December, its weakest expansion since the first quarter of 2013. That slowdown was partly due to a surprise contraction in France, which had performed more strongly in the previous three quarters and grew by 1.2% over the year as a whole. By contrast, Germany’s economy grew by just 0.6% in 2019, while Spain’s economy expanded by 2%. (…)

Speaking Saturday in London, U.S. Treasury Secretary Steven Mnuchin urged Germany in particular to act.

“There are countries that have opportunities to expand fiscal on top of monetary,” he said. “Monetary cannot be the only economic tool.”

However, it is unlikely that eurozone governments will deliver the stimulus for which the ECB and other bodies such as the IMF have called. Their plans for 2020 foresee only a modest increase in spending, and reflect the difficulty of directing budgets controlled by national governments toward the eurozone’s broader purpose.

Mike Pompeo calls Chinese Communist Party the ‘central threat of our times’
  • Pompeo in London for talks with British PM Boris Johnson about Huawei’s inclusion in UK’s 5G network providers

  • Pompeo restates US stand that Huawei systems could transfer national security information to Chinese intelligence agencies

(…) Despite the US campaign urging its allies to ban Huawei, Britain has chosen to let Huawei take part in noncore components of its 5G network, though it has capped Huawei’s market share at 35 per cent. Pompeo has called on the government to review its decision. (…)

The European Commission also stopped short of a blanket ban the next day, saying EU member states could exclude – or simply restrict – high-risk 5G vendors like Huawei from core parts of their telecoms networks. (…)

EARNINGS WATCH

As of Wednesday evening, we had 193 S&P 500 company, a 71% beat rate (19% miss rate) and a +4.4% surprise factor. All 11 sectors but one (Industrials at –5.6%) show a positive surprise factor. The 193 companies show an aggregate earnings growth rate of 4.4% on revenues up 2.4%. Margins up!

Q4 earnings are now seen up 0.7% (+3.5% ex-Energy).

Impressive!

Governments launch rewrite of international tax rules

The rise of Amazon (AMZN.O), Facebook (FB.O) and Google (GOOGL.O) has strained existing rules to breaking point because big tech companies can book profits in low-tax countries like Ireland no matter where their customers are located.

Tax officials from 137 governments agreed at a meeting in Paris to launch negotiations on new rules for where tax should be paid and what share of profit should be taxed when big digital and other consumer-facing businesses do not have a physical presence in the market, the OECD said. (…)

“It’s moving fast because what is at stake is a massive trade war,” OECD head of tax policy Pascal Saint-Amans told journalists in Paris.

“This is what we see on a daily basis with the interaction between France and the U.S. and with the interaction between the U.S and the countries that have said they would launch digital services taxes,” he added.

(…) but countries agreed to not deal with it until the technical work was done, Saint-Amans said.

The effective tax rate of S&P 500 companies has been slipping well before tax reform and is now significantly lower than the 21% U.S. statutory corporate tax rate…

image

An Ode to Luck: Revisiting my Tesla Valuation

If you care, this is from Aswath Damodaran, a Professor of Finance at the Stern School of Business at NYU.
THE DAILY EDGE: 30 JANUARY 2020

U.S. Pending Home Sales Decline Throughout the Country

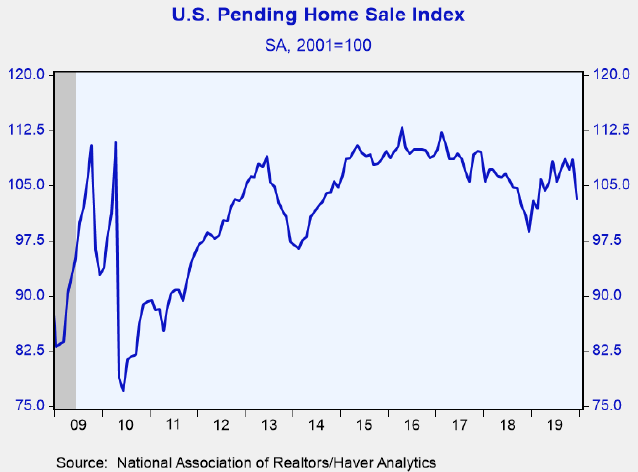
U.S. pending home sales fell 4.9% (+4.6% y/y) during December, according to the National Association of Realtors (NAR). The shortfall was the second in the last three months. During all of 2019, the average index level of 105.7 was 1.0% higher than in 2018 when the index declined 4.0%.

Sales declined in each region of the country last month. They fell 5.5% (+7.4% y/y) in the South, the third consecutive monthly decline. In the West, sales were 5.4% lower (+7.0% y/y) and have moved irregularly sideways for almost a year. Midwest sales fell 3.6% (+1.3% y/y), the second decline in three months. Sales in the Northeast declined 4.0% (-0.1% y/y) to the lowest level since May.

 image image

Fed Holds Benchmark Rate Steady All 10 members of the Fed’s rate-setting committee voted to hold the fed-funds rate in a range between 1.5% and 1.75% and reaffirmed the Fed’s make-no-moves posture.

“We’re comfortable with our current policy stance and we think it’s appropriate,” Fed Chairman Jerome Powell said at a news conference after the central bank announced its decision.

But his comments suggested that lingering risks to the global economy and difficulty sustaining inflation at the Fed’s 2% target meant that if Fed officials were to change rates, they would be more likely to cut them than to raise them. (…)

“We have seen this dynamic play out in other economies around the world and we’re determined to avoid it here in the United States,” he said. Mr. Powell later said the review was designed to address how “ongoing powerful, global disinflationary trends” have hampered central banks around the world. (…)

The Fed’s postmeeting statement Wednesday offered a mixed assessment of the economic outlook. It described consumer spending growth as moderate, a downgrade from “strong” in December, and said business investment had remained weak. (…)

ONLY AROUND RICHMOND?

Richmond Fed’s Regional Surveys of Business Activity:

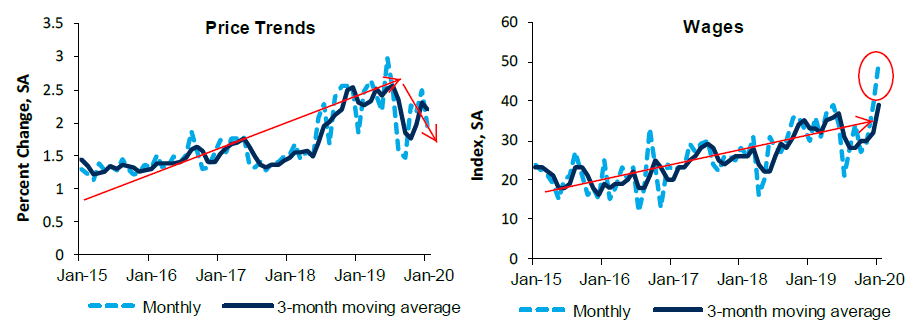
Survey results suggest strong wage growth among service sector firms in January, as this index rose to an all-time high of 50. Measures of employment and the average workweek also indicated growth, but firms reported difficulty finding workers with the necessary skills. They expected this struggle to persist but wages and employment to grow in the near future.

The average growth rates of both prices paid and prices received by survey participants fell in January, as growth of prices paid continued to outpace that of prices received. Respondents expected both growth rates to slow further in the coming months.

Fifth District Survey of Service Sector Activityimage

China first quarter growth may dip below 5% as virus spreads: government economist

(…) Zhang, an economist at the Chinese Academy of Social Sciences – a top government think tank – said his forecast was based on the assumption that the outbreak will peak in early to mid-February and end by the end of March.

Zhang is among many government economists and, while the Academy’s views often serve as a recommendation for Chinese policymakers, his views may not fully align with those of the government, which has yet to issue any assessments. (…)

In response, the government is likely to step up policy support, which could boost the annual budget deficit as a share of GDP to over 3% in 2020, he said. (…)

German Unemployment Falls as Industry Outlook Starts to Brighten

The number of people out of work dropped by 2,000 in January to 2.277 million, defying economist predictions for an increase. The jobless rate held at 5%, near a record low. (…)

Germany’s government raised its growth projection for this year to 1.1% and sees momentum accelerating further in 2021. Even though that’s an improvement from 2019, when output expanded at the weakest pace in six years, Economy Minister Peter Altmaier said Wednesday that rates at those levels are hardly satisfactory. (…)

Eurozone economic sentiment jumps as unemployment reaches new decade low

Compared to the other eurozone surveys that have come out this month, the ESI was surprisingly upbeat with an increase to 102.8 from 101.3. German and French industry, in particular, became a lot more optimistic about the outlook and somewhat less pessimistic about recent production developments. These are signs that the bottom in manufacturing is now getting close.

One has to be cautious in interpreting these numbers though as uncertainty around the impact of the coronavirus on the global economy is mounting. That has not been factored into these results just yet, meaning that the revival of optimism could be short-lived. (…)

What the Middle East Peace Plan Really Means

(…) the Deal of the Century is remarkable for the overwhelming support it has among Gulf Arab states. Saudi Arabia, the United Arab Emirates, Egypt, Bahrain, Qatar and Morocco have all endorsed the proposal, though they have offered nothing specific about what they would do to see it through. Still, their collective rush to champion the deal is notable for what the breach between Arab Gulf states and the Palestinian Authority signifies: the new geopolitical reality emerging in the Middle East, one arrayed against the actions of Turkey and Iran.

(…) Put simply, the expansion of Iranian influence has become the security priority to which all other foreign policy issues take a back seat. The same could be said in response to Turkey, which has been aggressively advancing its interests in Syria and the Eastern Mediterranean. (…)

In that sense, the “Deal of the Century” is not about an Israel-Palestine peace; it’s about reconfiguring the alliance structure of the Middle East. Sunni Arab countries are beginning to pivot from foreign policies grounded in post-WWI realities and nationalisms stemming from 20th-century colonial mandates that defined the regional balance of power. Now they are becoming more visible in redefining regional geopolitics and aligning with former adversaries, grounded in new, emerging security threats. (Geopolitical Futures)

EARNINGS WATCH

We now have 143 S&P 500 companies in, a 71% beat rate (20% miss rate) and a +4.0% surprise factor. Aggregate earnings of those 85 companies are up 5.2%, much better than at the same time during Q3’19.

Pointing up The 22 IT companies having reported so far sport a 100% beat rate on earnings and 86% on revenues (S&P 500 avg: 65%). Their surprise factor is +8.9% on earnings and +2.9% on revenues (+0.7% avg). IT companies are 24% of the S&P 500 market cap and 20% of earnings. Analysts are now expecting IT earnings up 5.4% in Q4, from +0.5% on Jan. 1.

Q4’19 earnings are now seen unchanged (+2.7% ex-Energy). Q1’20 estimates are +5.6%, down from +6.3% on Jan. 1.

FYI from Goldman Sachs:

The EURO STOXX 50 derives 10% of its revenues from China, roughly twice as much as S&P 500 companies (6%). For some indices, such as the DAX, as much as 15% of company revenues come from China. In terms of sector exposure, Luxury stocks, Basic Resources and Autos are the most exposed (exhibit 2). Our China exposure basket, GSSTCHNA, generates about 25% of its revenues in China.

2. The exposure of the EURO STOXX 50 to China is about twice that of the S&P 500. Data available on request.

TECHNICALS WATCH

  • NDR Crowd Sentiment Poll
SENTIMENT WATCH
  • Bonds continue to see historic inflows

The week ended Jan. 8 saw the largest inflows to bonds ever recorded and the following week (which ended Jan. 15) saw the fourth highest total on record. Those two weeks combined set a record for bond inflows during a two-week period, according to Lipper data. (Axios)

image

The world’s business elite is convinced that Donald Trump will win a second term in the White House in November, and investors seem to believe there’s little risk they will end up victims of the U.S. election.

In reality, investors face triple uncertainty about the outcome—and should be concerned. The election is highly likely to be close, because modern America is split down the middle—and that makes it inherently uncertain. The Democratic candidate isn’t yet chosen, and could be radical. And a victory by Mr. Trump might not provide the relief that investors expect. (…)

So far, markets have stayed sanguine. Shares have had a great run interrupted only by the fears from the Wuhan virus in the past few days. There’s little sign that investors are scared of anything on the political front.

They should be: The prospect of a socialist-leaning White House would surely hurt stocks in the short run, while Mr. Trump could hurt stocks for longer with a new trade war. CEOs and investors are too sure both of Mr. Trump’s prospects and that their share prices would do as well in his second term as they did in the first.

KKR’s views:

While all presidential elections are important, 2020 could be particularly consequential, as both a referendum on President Trump’s disruptive leadership and a harbinger of future direction for U.S. policy and politics. (…)

The historical context for this election is also important to keep in mind. Since 2015, insurgent candidates have won overwhelmingly across the world. This trend goes back further in the U.S. where, over the past 20 years, U.S. voters have increasingly voted against incumbents in favor of opposition parties. President Trump was elected as the ultimate insurgent, but today he is the incumbent. He will benefit most from a strong economy (since 1924, the only incumbent President’s defeated for re-election faced a recession in the two years prior to the vote). Recent tensions with Iran could help the President as historically Americans rally around their Commander in Chief during times of global crisis. Focus on Iran could also reduce coverage of and miniaturize impeachment proceedings against President Trump. Also, the power of any sitting President to set policy, build his party machine and make news is not to be underestimated, particularly when coupled with a unified GOP and President Trump’s remarkably effective communications and marketing skills.

On the other hand, President Trump, who has never achieved a 50% approval rating, has also mobilized and unified his critics. Remember the Trump GOP machine has lost many elections in 2017, 2018 and 2019. Consistent with the backdrop of a more politically charged environment, the 2018 midterms saw the highest eligible voter turnout in 104 years, and many of the 2019 off-year elections also produced historic turnout. Hence, our view is that President Trump will have more difficulty winning the popular vote. However, we all know that American Presidents are elected by the Electoral College, which means fewer than 10% of eligible voters in seven states — Florida, Michigan, Minnesota, North Carolina, Pennsylvania, Wisconsin, and Arizona — will select the next President of the United States. Within those states, pay particular attention to white working class men and suburban female voters.

U.S. Senate elections will also be important as the closely divided Senate will have a critical voice on new policy. The GOP’s four seat majority is potentially in peril, as several Republicans in Democratic leaning states face serious challengers. Prediction markets may underestimate this possibility, in our opinion. (…)