Did you know there is a moose calling championship? During the three-day event, 50,000 applicants replicate the eerie sound a moose makes during mating season in the hope of winning one of the few available hunting permits.
The contest entails callers to demonstrate their skills to the judges who vote on the moose caller who shows and demonstrates the best or most innovative moose calling techniques. (…)
It was like Kevin was in a trance. Although he was on a stage he wasn’t in his own mind… he was out on a moose hunt.
The audience sat through the performance but really wasn’t showing much emotion towards Kevin and his moose calling. I could imagine some saying “We’ve seen this stuff before!”
Then the unforeseen happened! Kevin’s 5 year old daughter, wearing her hunter blaze orange hunting gear got up on stage with her POP Gun and SHOT the moose. The audience apparently erupted in applause with shouting and whistling.
Kevin won the Moose Calling Championship for 2012 (his third straight win) in Maine and was awarded $1000.00. (…)
The championship being held just prior to the opening of the hunting season, the moose population traditionally renounces appearing at the contest to cast its expert opinion.
Another contest is more interested in the quantity of calls than in quality. You will all be happy to know that Guinness World Records has confirmed that Main Street Skowhegan and the Town of Skowhegan set the new world record for the most people moose calling simultaneously! The record was established on June 9, 2018, at the 2018 Skowhegan Moose Festival when 1,054 people participated in the world record attempt led by Registered Maine Guide Roger Lambert.
All the same for recession calling. It seems that 2019 will set a new record for the number of simultaneous recession calls. Time will tell if a recession will succumb to the calls and timely show up on stage.
Callers must be even sharper this time given that Jerome Powell seems uninterested to use his POP gun and abruptly end the contest.
A reader pointed to a recent Bloomberg op-ed from Danielle DiMartino Booth declaring that (my emphasis)
According to historic payroll data and the National Bureau of Economic Research, every time the three-month average unemployment rate exceeded its six-month average at cycle peaks over the past 50 years — like it did in January — the U.S. economy has experienced a recession. In a 2016 speech to the International Monetary Fund, then Federal Reserve Bank of New York President — and current Bloomberg Opinion contributor — William Dudley corroborated the historic pattern citing research first conducted earlier in his career at Goldman Sachs:
“History shows it is very difficult to push the unemployment rate back up just a little bit in order to contain inflation pressures. Looking at the post-war period, whenever the unemployment rate has increased by more than 0.3 to 0.4 percentage points, the economy has always ended up in a full-blown recession with the unemployment rate rising by at least 1.9 percentage points.”
Fact checking DiMartino Booth’s claim: obviously, the 3m average exceeds the 6m average much more often than there are recessions.
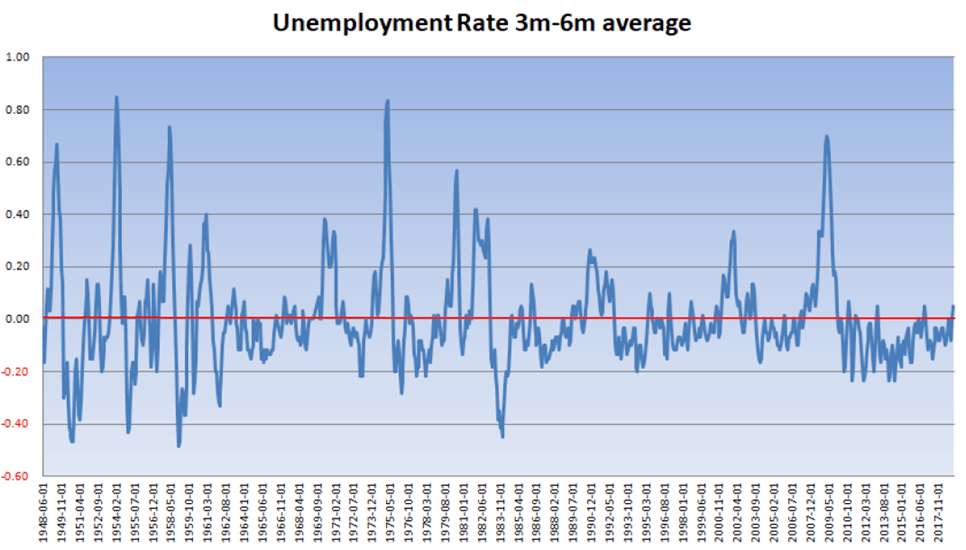
But if you read too rapidly, you missed the key part of her claim: “every time the three-month average unemployment rate exceeded its six-month average at cycle peaks over the past 50 years, the U.S. economy has experienced a recession.” We can all easily agree that every time we reached cycle peak the economy has experienced a recession not long after. The challenge remains to correctly call the darn cycle peak.
Perhaps if there are enough calls, the peak will graciously appear.
This next chart includes the unemployment rate in red (inverted right axis). Of course, once you have identified the actual peak, you can watch when the 3m average exceeds the 6m average to conclude that the cycle has effectively ended and “make your call”. But how many times will you have called the peak before the actual peak really happens? The call looked good on October 2016 when the unemployment rate rose from 4.8% to 5.0%. Oups! Not good enough. How about 1995, 1997, 1998? The recession began in March 2001. Or 1963, 1967, well before the recession started in December 1969?

The other twist is to have Bill Dudley, “then Federal Reserve Bank of New York President” having “corroborated the historic pattern”. At least she did cite Dudley correctly who, if I read well, is not exactly corroborating the “historic pattern” as described by DiMartino Booth:
Looking at the post-war period, whenever the unemployment rate has increased by more than 0.3 to 0.4 percentage points, the economy has always ended up in a full-blown recession with the unemployment rate rising by at least 1.9 percentage points.
David Rosenberg used the same Dudley pattern in early February to support his recession call which prompted me to comment in the Feb. 4 Edge and Odds:
David Rosenberg highlights the fact that the unemployment rate, at 4.0%, is up 0.3% from its 3.7% cycle low and that “the mean, median and mode is for the jobless rate to rise 0.4 of a point from the low by the time the recession hits. We are now three-quarters there. Data back to 1950 shows that at no point in the past did we see a 0.6 point increase off the trough without seeing a NBER-defined recession.”
This is true with the only possible exception being June-Nov. 1959 when the U3 rate rose 0.8 points before falling back to a new low in Feb. 1960, two months before the recession (!). However, there have been six occasions since 1950 when the U3 rate rose 0.4 or 0.5 points without being followed by a recession.
I sure wish calling recessions were that easy.
But DiMartino Booth added some meat to her cracked bone:
To Dudley’s point, the odds that layoffs will continue rising are high. As per January data from Challenger, Gray & Christmas, layoffs have risen over the prior year for six straight months. Economists would characterize that as an established trend. Retail and more recently, energy, have been some of the weakest sectors. Media is another sore spot.
Facts are:
- There were other periods of “established trends” in CGC data: layoffs rose during 4 consecutive quarters between Q3’11 and Q2’12, and again during 3 consecutive quarters between Q1’15 and Q3’15. And yet, employment kept rising and the unemployment rate kept declining.
- Retail layoffs have indeed been bad (42% of all announced layoffs in January) but she omitted to mention that most of January’s retail layoffs were “related to Gymboree’s plan to liquidate remaining stores in the U.S. and Canada, costing a reported 10,000 jobs”. Also omitted was CGC’s other comment that “Lowe’s announced it would hire 50,000 seasonal workers for the spring, as well as 10,000 permanent roles and 6,000 managers”.
Actually, CGC also points out that “retail is going through a transformation that may cost many jobs, but is also creating many jobs”. Brick and mortar jobs lost are more than offset by internet retailing. The BLS numbers on retail trade hires also has its own established trend:

As I mentioned last week, recent trends in aggregate hours worked do not suggest strongly rising layoffs:

But perhaps if we keep calling, something will eventually show up.


